



Lubricant Anti-Wear Agents Market Size, Key Companies, Company Market Share, Production Capacity, Raw Material Pricing, Export & Import Analysis, Manufacturing Cost, Competitive Positioning, and Demand Forecast
Vidyesh Swar, a Chemical and Materials Industry Expert, estimates the lubricant anti-wear agents market at USD 836.36 million in 2026 to USD 1,091.26 million by 2035, growing at a CAGR of 3%. Major lubricant anti-wear agents market companies such as Lubrizol, Infineum, Chevron Oronite are competing across key material and application segments, including type, application and region.
Source: https://www.precedenceresearch.com/lubricant-anti-wear-agents-market
 Get a Sample
 Report Description


Lubricant Anti Wear Agents Market Size, Demand, and Trends Analysis 2035
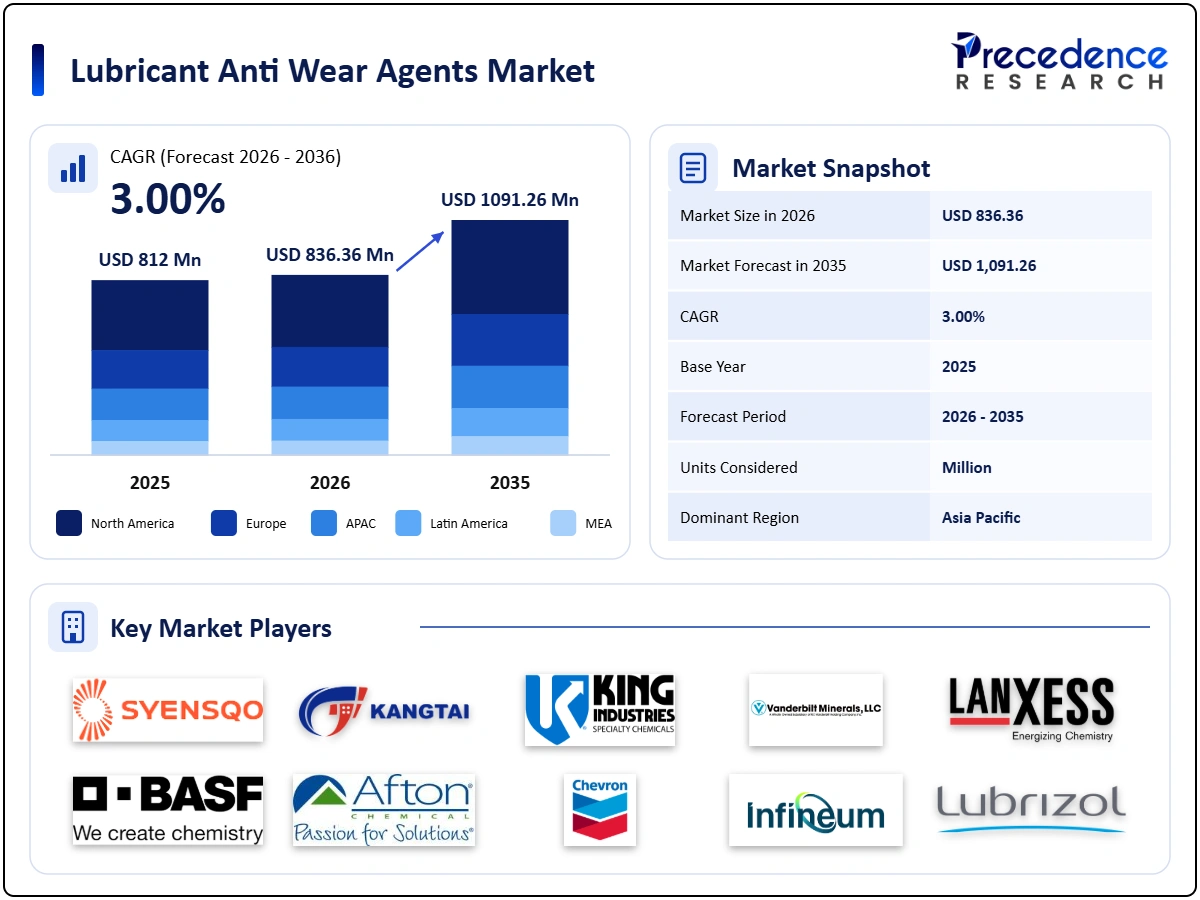
The lubricant anti-wear agents market is forecasted to expand from USD 836.36 million in 2026 to USD 1,091.26 million by 2035, growing at a CAGR of 3% from 2026 to 2035.
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 812.00 million
- Estimated market size in 2026: USD 836.36 million
- Projected market size by 2035: USD 1,091.26 million
- CAGR (2026-2035): 3.00%
Regional Market Spotlight
- Asia Pacific led the market with a 39.60% (USD 321.55 million) share in 2025 and is projected to be the fastest-growing region, at a CAGR of 3.59% from 2025 to 2035.
- North America accounted for 24.20% (USD 196.50 million) of the market in 2025.
- Europe accounted for 20.40% (USD 165.65 million) of the market in 2025.
Segmental Spotlight
- By type, ZDDP accounted for 61.80% (USD 501.82 million) in 2025.
- By application, Engine Oil accounted for 52.40% (USD 425.49 million) in 2025.
Lubricant Anti-Wear Agents Market Size and Forecast, 2025-2035 (USD Million)
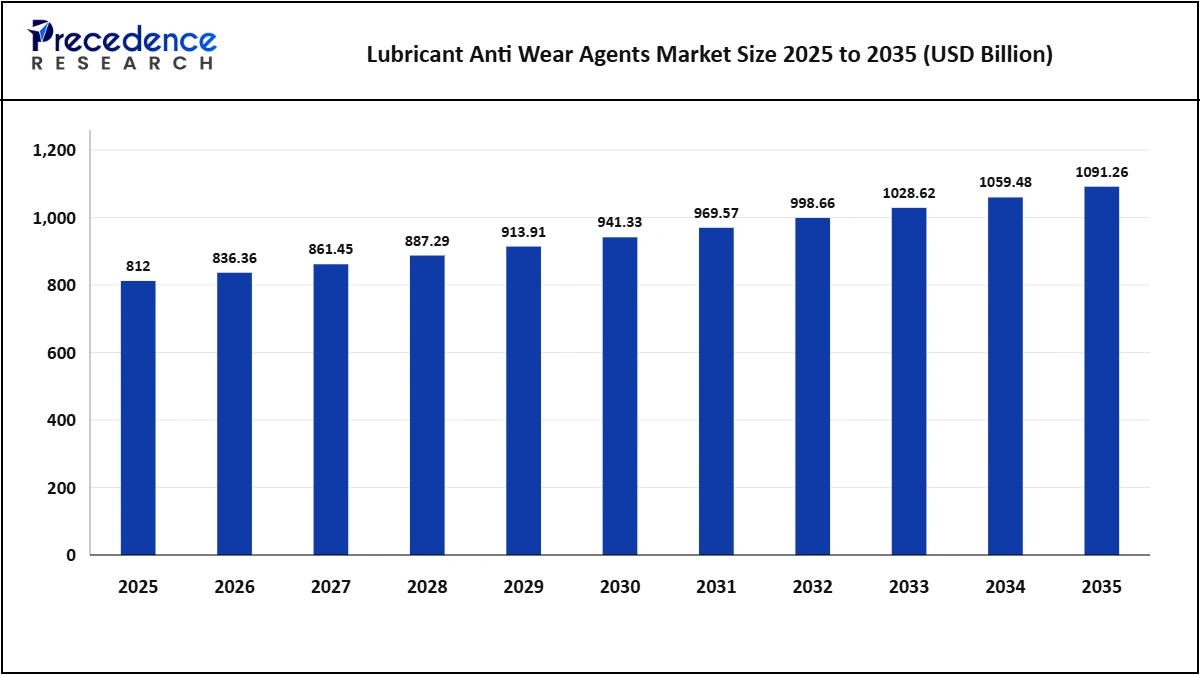
Note: 2025 is the base year; 2026–2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
The lubricant anti-wear agents market is projected to grow from USD 812.00 million in 2025 to USD 1,091.26 million by 2035 because nearly all engine, gear, hydraulic, and industrial lubricants contain anti-wear additives to protect metal surfaces, so demand follows global lubricant production. Changes in engine oil formulations and premium industrial fluids increase the treat rate and value, which is why the market is projected to reach USD 941.33 million by 2030, growing at a CAGR of 3.00%.
- Analyst View: We built the estimate from global lubricant production by application and region, the typical anti-wear additive treat rate in each lubricant type, and average prices for ZDDP and ashless chemistries. Lubricant usage levels depend on vehicle fleet size, industry operations, and drainage cycles, whereas treat rates depend on specification and formulation developments. We cross-checked the total against the additive component revenue of leading additive companies and published estimates, which places our base year slightly above comparable figures. The demand for premium grades of lubricants in Asia drives growth, while the demand for engine oils in developed markets declines.
Market Trends
- Zinc-free anti-wear additives grow in hydraulics.
- Low-viscosity engine oils need durable wear protection.
- Phosphorus limits protect emission catalysts.
- EV fluids need copper-compatible anti-wear chemistry.
- Ashless additives gain under environmental rules.
- Asian additive capacity expands.
Drivers, Restraints and Opportunities
Driver
Lubricant consumption is growing in Asia, Africa, and Latin America. Engine oils need to be wear-resistant at low viscosity, and due to longer drain intervals, more robust additives are needed. Industrial automation and construction increase hydraulic and gear oil use. Environmental regulations are responsible for the increasing need for ashless and zinc-free anti-wear additives.
Restraint
The amount of engine oil is stable or falling in developed countries due to an increase in drain intervals. Electric cars lower engine oil consumption in the long run. Regulations on phosphorus and sulfur impose restrictions on the rate of ZDDP. Volatility in the cost of raw materials influences margins.
Opportunity
Electric vehicle drivetrain fluids need new anti-wear chemistries compatible with copper and electrical components. Environmental regulations will help zinc-free industrial fluids develop. Bio-based lubricants need compatible anti-wear additives. The rising demand for lubricants in emerging markets offers volume. Premium synthetic lubricants can support higher-value additives.
Market Segmentation: 2025 Share and Value
Lubricant Anti-Wear Agents Market by Type 2025 Share
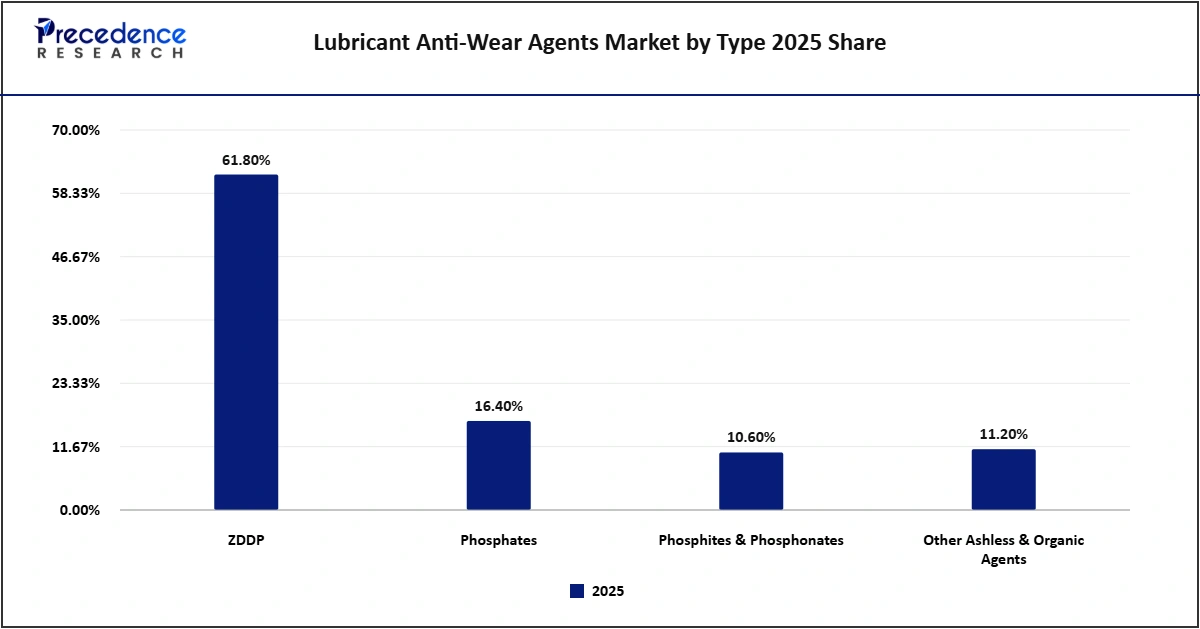
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
ZDDP accounted for 61.80% (USD 501.82 million) in 2025 because zinc dialkyldithiophosphates provide anti-wear, antioxidant, and anti-corrosion protection in a single low-cost molecule and are used in nearly all passenger car and heavy-duty engine oils and many hydraulic oils. Specifications for engine oils restrict phosphorus levels to preserve catalysts, hence maintaining ZDDP treat rates instead of removing it altogether. Phosphates, at 16.40% (USD 133.17 million), and phosphites and phosphonates, at 10.60% (USD 86.07 million), are used in ashless hydraulic, gear, and industrial fluids. Other ashless and organic agents account for 11.20% (USD 90.94 million) and are the fastest-growing type as zinc-free hydraulic fluids and electric vehicle fluids expand.
Lubricant Anti-Wear Agents Market by Application 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Engine Oil | 52.40% | USD 425.49 million |
| Hydraulic Oil | 14.80% | USD 120.18 million |
| Automotive Gear Oil | 10.20% | USD 82.82 million |
| Automotive Transmission Fluid | 8.20% | USD 66.58 million |
| Metalworking Fluid | 7.40% | USD 60.09 million |
| Grease | 7.00% | USD 56.84 million |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Engine oil accounted for 52.40% (USD 425.49 million) in 2025 because engine oils are the largest lubricant category and require robust wear protection for valve trains and bearings, with new specifications such as ILSAC GF-7 and API SQ demanding durable protection at ultra-low viscosities. Hydraulic oil accounts for 14.80% (USD 120.18 million); automotive gear oil for 10.20% (USD 82.82 million); automotive transmission fluid for 8.20% (USD 66.58 million); metalworking fluid for 7.40% (USD 60.09 million); and grease for 7.00% (USD 56.84 million). Hydraulic and transmission fluids are the fastest-growing applications as industrial demand and electrified drivetrain fluids grow.
- Analyst View: Segment values were allocated by matching lubricant volumes, treat rates, and prices to additive types and applications, using additive company revenue mixes. ZDDP leads because of its use in engine oils. We expect ashless and organic agents and hydraulic and transmission fluids to gain share.
Regional Analysis
Lubricant Anti-Wear Agents Market by Region 2025 Share
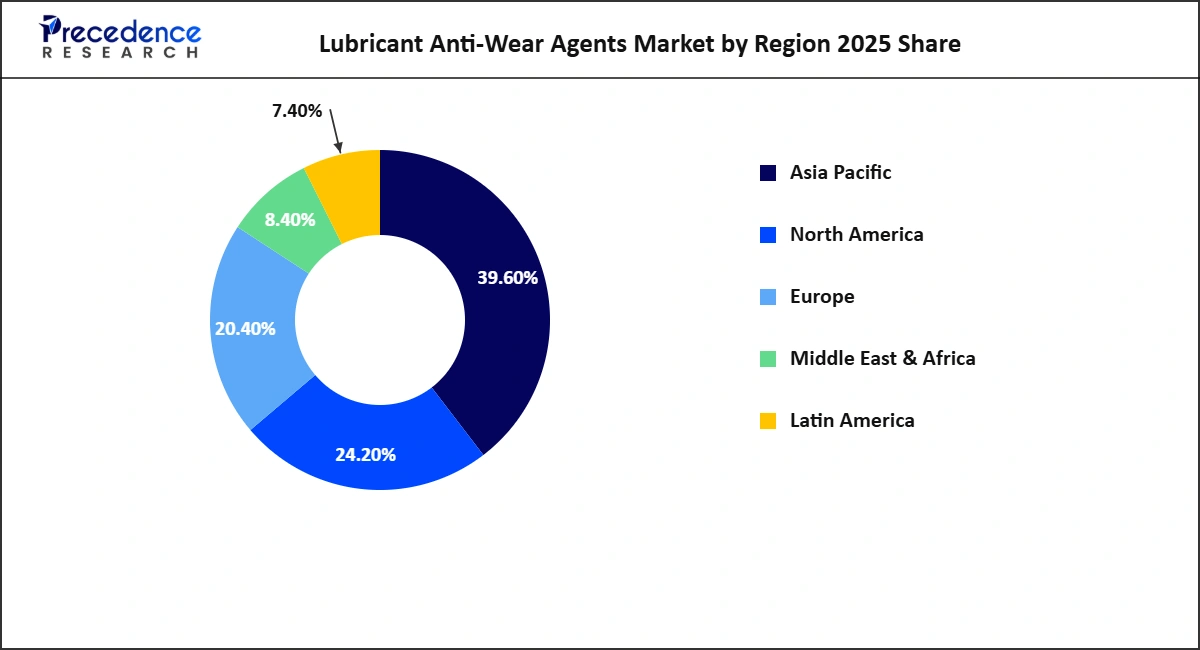
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Asia Pacific accounted for 39.60% (USD 321.55 million) in 2025, the largest share and the fastest growth, supported by large and growing vehicle fleets in China, India, and Southeast Asia, expanding lubricant blending capacity, and rising industrial lubricant use. North America, at 24.20% (USD 196.50 million), is supported by a large vehicle fleet, the launch of ILSAC GF-7 and API SQ engine oils, and heavy-duty and industrial lubricant demand. Europe, at 20.40% (USD 165.65 million), is supported by ACEA specifications, premium synthetic lubricants, and strict environmental requirements that favor ashless chemistries. The Middle East and Africa, at 8.40% (USD 68.21 million), and Latin America, at 7.40% (USD 60.09 million), are supported by vehicle and industrial lubricant growth.
Asia Pacific accounted for 39.60% (USD 321.55 million) in 2025 and is the largest and fastest-growing region. China and India are major lubricant producers and consumers. Additive companies operate large plants in Singapore, China, and India. Increasing number of vehicles leads to more oil consumption.
North America accounted for 24.20% (USD 196.50 million) in 2025. The ILSAC GF-7 and API SQ engine oil specifications began licensing in March 2025, and more than 1,800 GF-7 oils were licensed by August 2025. Heavy-duty and industrial oils add to demand.
Europe accounted for 20.40% (USD 165.65 million) in 2025. ACEA and OEM specifications require low-phosphorus, low-ash oils. Environmental rules support ashless hydraulic fluids. Germany, France, and the United Kingdom are major markets.
The Middle East and Africa accounted for 8.40% (USD 68.21 million) in 2025. Lubricant blending in the Gulf serves regional and export markets. Vehicle fleet growth in Africa adds demand.
Latin America accounted for 7.40% (USD 60.09 million) in 2025. Vehicle and industrial lubricant demand in Brazil and Mexico drives additive use.
Analyst View: Regional shares were built from lubricant volumes, treat rates, and prices in each region. Asia Pacific leads because of lubricant production scale. We assign Asia Pacific the highest growth premium because vehicle fleets and lubricant demand are growing fastest there.
Top 10 Companies in the Lubricant Anti-Wear Agents Market
| Rank | Company Name | Market-Specific Revenue (USD Million) | 2025 Share | Key Products/Business | Headquarters |
| 1 | Lubrizol | 168.00 | 20.69% | ZDDP and zinc-free anti-wear additives | United States |
| 2 | Infineum | 132.00 | 16.26% | Anti-wear components and additive packages | United Kingdom |
| 3 | Chevron Oronite | 118.00 | 14.53% | OLOA additive components and packages | United States |
| 4 | Afton Chemical | 104.00 | 12.81% | HiTEC anti-wear additives | United States |
| 5 | BASF | 42.00 | 5.17% | Irgalube ashless anti-wear additives | Germany |
| 6 | LANXESS | 34.00 | 4.19% | Additin anti-wear additives | Germany |
| 7 | Vanderbilt Chemicals | 18.00 | 2.22% | Vanlube anti-wear additives | United States |
| 8 | King Industries | 14.00 | 1.72% | NA-LUBE ashless additives | United States |
| 9 | Jinzhou Kangtai | 12.00 | 1.48% | ZDDP and additive components | China |
| 10 | Syensqo | 10.00 | 1.23% | Phosphorus anti-wear chemistries | Belgium |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Lubrizol led the lubricant anti-wear agents market with an estimated 20.69% (USD 168.00 million) of 2025 revenue, followed by Infineum at 16.26% (USD 132.00 million) and Chevron Oronite at 14.53% (USD 118.00 million). Lubrizol leads as one of the largest lubricant additive companies, supplying ZDDP and complete additive packages for engine, driveline and industrial oils, and in October 2025 it launched AH933ZF, a zinc-free hydraulic additive offering anti-wear protection with longer drain intervals. Infineum, Chevron Oronite and Afton Chemical are the other major additive package suppliers, producing large volumes of ZDDP for engine oils worldwide. BASF, LANXESS, Vanderbilt Chemicals and King Industries supply ashless anti-wear components for industrial and specialty fluids, while Chinese producers such as Jinzhou Kangtai and Syensqo add regional and phosphorus chemistry supply.
The top 10 companies were responsible for the total share of 80.30 percent (USD 652.00 million), whereas the rest of 19.70 percent (USD 160.00 million) came from regional additive manufacturers in China and India, along with specialty phosphorus chemical manufacturers. The lubricant anti-wear agents market is concentrated among four large additive package companies, because performance specifications and OEM approvals require extensive testing. Wear prevention, compliance with emissions systems, oxidation and hydrolytic stability, ashless and zinc-free alternatives, pricing, and technical service are the main areas of competition.
Recent Developments
- March 2025: API began licensing ILSAC GF-7 and API SQ gasoline engine oils, and by August 2025 more than 1,800 GF-7 products and over 2,500 SQ products had been licensed, including ultra-low-viscosity grades.
- October 2025: Lubrizol unveiled AH933ZF, a zinc-free hydraulic fluid additive capable of offering anti-wear protection, extended drain life, and better air release and foam control.
Lubricant Anti Wear Agents Market Segments
By Type
- ZDDP
- Phosphates
- Phosphites & Phosphonates
- Other Ashless & Organic Agents
By Application
- Engine Oil
- Hydraulic Oil
- Automotive Gear Oil
- Automotive Transmission Fluid
- Metalworking Fluid
- Grease
By Region
- North America (U.S., Canada, Mexico)
- Europe (Germany, U.K., France, Italy, Spain, Rest of Europe)
- Asia Pacific (China, Japan, India, South Korea, Taiwan, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East & Africa (GCC, South Africa, Rest of MEA)
Research Methodology
The lubricant anti-wear agents market refers to ZDDP, phosphate, phosphite, phosphonate, and other anti-wear additives for engine, gear, transmission, hydraulic, metalworking, and grease applications, worldwide. The 2025 base year was built bottom-up from lubricant production by application and region, anti-wear treatment rates and average additive prices, and checked top-down against the additive component revenue of leading additive companies. Segment, regional and company values were allocated from additive types, applications and regional demand. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: Overall Market
The lubricant anti-wear agents market is a mature, slow-growing market tied to lubricant production, with value growth from new specifications and ashless chemistries. Demand forecasts are linked to the amount of lubricants consumed, their treatments, and costs; thus, the forecast varies in correlation with the car fleet, industry performance, and formulation advancements. The main drivers are EVs liquids and zinc-free industrial oils; the risks involve lower engine oil volumes and phosphorus limitations.
Sources and References
- National Oil & Lube News. "American Petroleum Institute licenses over 1,800 ILSAC GF-7 engine oils". 2025-08-13. GF-7 and SQ licensing. https://www.noln.net/site-placement/latest-news/news/55309452/american-petroleum-institute-licenses-over-1800-ilsac-gf-7-engine-oils
- Business Wire. "Lubrizol launches zinc-free hydraulic additive". 2025-10-23. Lubrizol AH933ZF. https://www.businesswire.com/news/home/20251023502020/en
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample




 sales@precedenceresearch.com
 Schedule a Meeting
