



Specialties Lube Oil Refinery Market Size, Key Companies, Company Production Capacity, Manufacturing Efficiency, Capacity Utilization, Raw Material Consumption, Cost Structure, Export Trends, Company Expansion Strategies, and Competitive Landscape
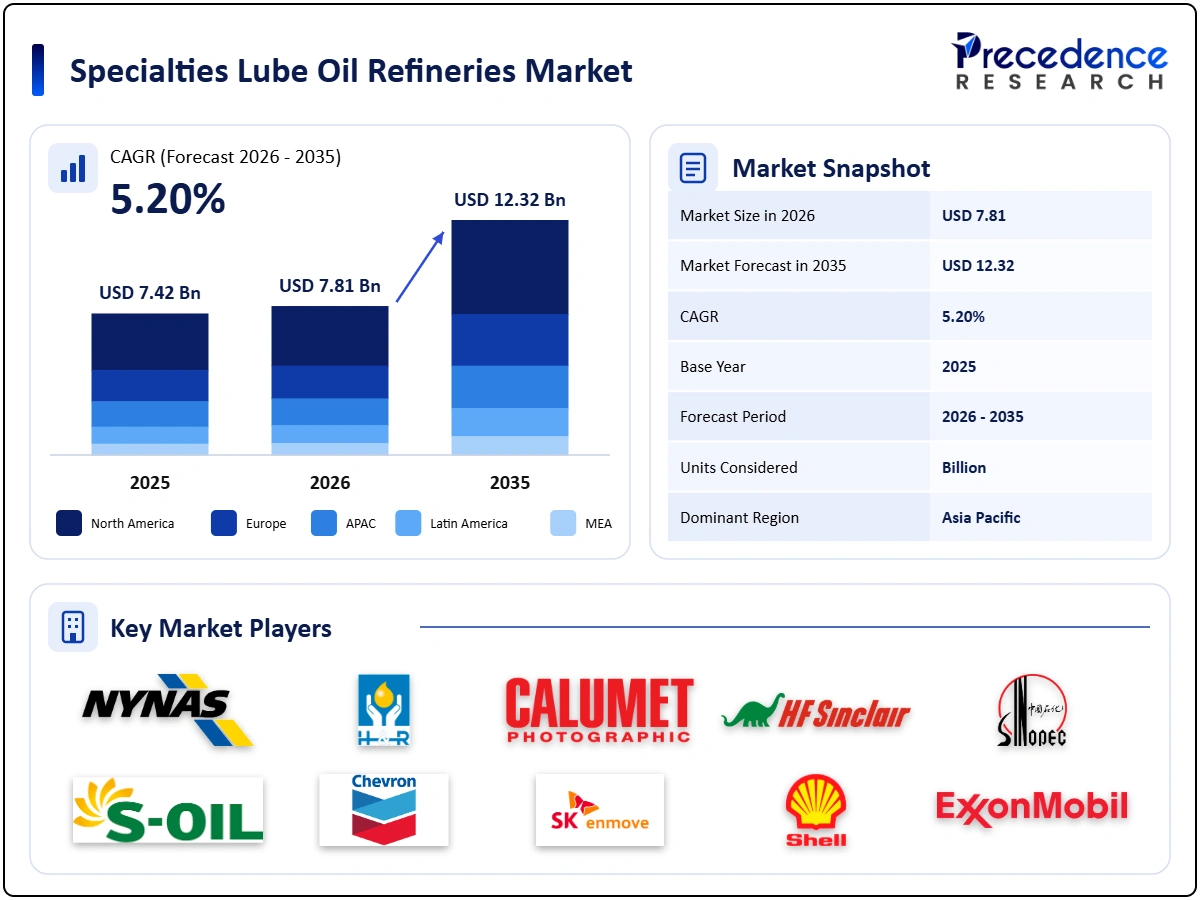
Vidyesh Swar, a Chemical and Materials Industry Expert, estimates the specialties lube oil refinery market at USD 7.81 billion in 2026 to USD 12.32 billion by 2035, growing at a CAGR of 5.20%. Major specialties lube oil refinery market companies such as ExxonMobil, Shell, SK Enmove, Chevron are competing across key material and application segments, including product, application and region.
Source: https://www.precedenceresearch.com/specialties-lube-oil-refineries-market
 Get a Sample
 Report Description
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 7.42 billion
- Estimated market size in 2026: USD 7.81 billion
- Projected market size by 2035: USD 12.32 billion
- CAGR (2026-2035): 5.20%
Regional Market Spotlight
- Asia Pacific led the market with a 41.40% share of USD 3.07 billion in 2025.
- North America accounted for 22.20% with USD 1.65 billion of the market in 2025.
- Europe accounted for 18.40% with USD 1.37 billion of the market in 2025.
- Middle East & Africa accounted for 10.20% with USD 0.76 billion in 2025 and is projected to be the fastest-growing region, at a CAGR of 6.44% from 2025 to 2035.
Segmental Spotlight
- By product, the specialty Base Oils (Group II & III) accounted for 46.40% with USD 3.44 billion in 2025.
- By application, the automotive Lubricants accounted for 38.20% with USD 2.83 billion in 2025.
Specialties Lube Oil Refinery Market Size and Forecast, 2025-2035 (USD Billion)
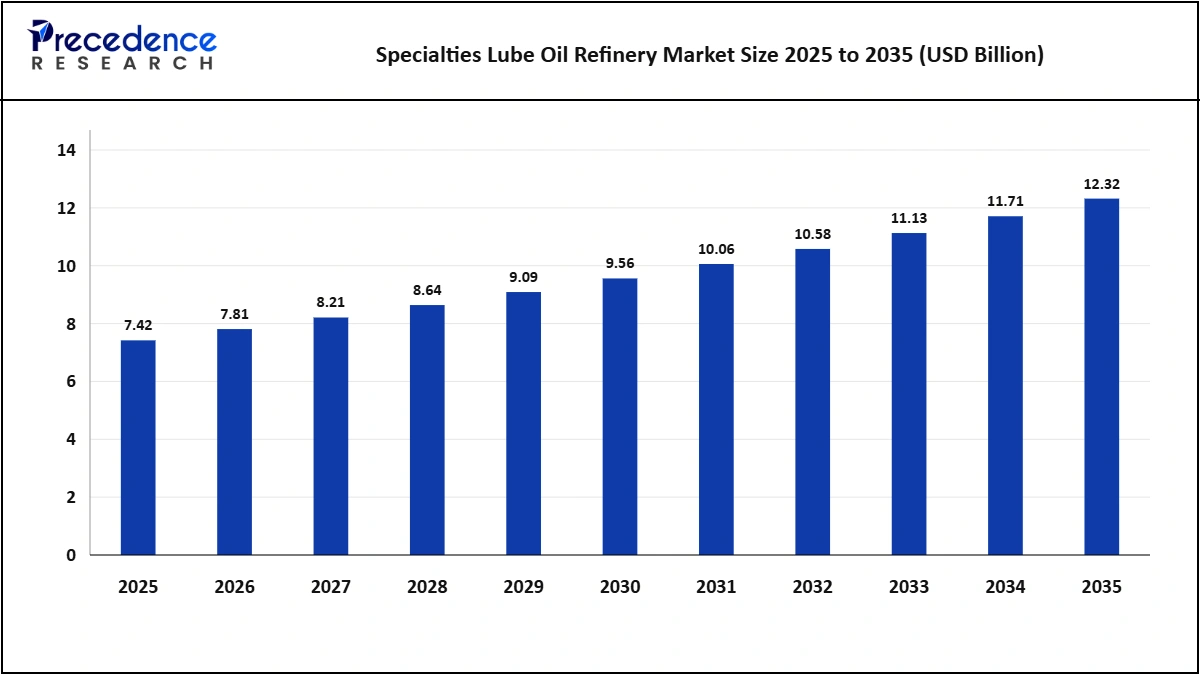
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The specialties lube oil refinery market is projected to grow from USD 7.42 billion in 2025 to USD 12.32 billion by 2035 because lubricant blenders, consumer product makers, and industrial users need specialty base oils, white oils, waxes, and process oils that only dedicated lube refineries can produce. Group III base oils for low-viscosity engine oils carry premiums over conventional base stocks, lifting the market to USD 9.56 billion by 2030 and sustaining a CAGR of 5.20% from 2026 to 2035.
- Analyst View: We built the estimate from specialty product output of lube oil refineries by product and region, multiplied by average selling prices for Group II and Group III base oils, white oils, waxes, process oils and other specialties. Output reflects base oil plant capacities and utilisation, Group I closures and new Group III projects, and demand from lubricants, consumer products, packaging and rubber.
The total was cross-checked against the specialty and lubricant segment revenue of leading refiners and against published estimates, which places our base year slightly above the comparable figures. The growth rate reflects premium base oil and white oil growth, moderated by Group I capacity closures and flat lubricant volumes in mature markets.
Market Trends
- Refiners convert fuel units to Group III base oils.
- Group I capacity closes in Europe and North America.
- New US Group III plants reduce import reliance.
- White oil demand grows in personal care.
- Lubricant businesses are spun off or partnered.
- Low-viscosity engine oils favour Group III stocks.
Drivers, Restraints and Opportunities
Driver
Engine oil specifications favour high-viscosity-index Group II and Group III base oils. Refiners seek higher margins by converting fuel capacity to specialties. White oil demand grows in cosmetics, pharmaceuticals and food. Wax demand continues in packaging, candles and rubber. Lubricant demand grows in Asia, the Middle East and Africa.
Restraint
Electric vehicles will reduce engine oil demand over time. Group I closures reduce supply of some specialties such as bright stock and aromatic extracts. Specialty projects require large capital investment. Crude price volatility affects margins. Long drain intervals reduce lubricant volumes.
Opportunity
Group III and Group III+ base oils can grow with premium and EV fluids. Re-refined base oils offer circular supply. White oils and waxes for consumer products can expand. Gulf and Asian refiners can grow specialty exports. Partnerships between refiners and lubricant marketers can secure long-term demand.
Market Segmentation: 2025 Share and Value
Specialties Lube Oil Refinery Market by Product 2025 Share
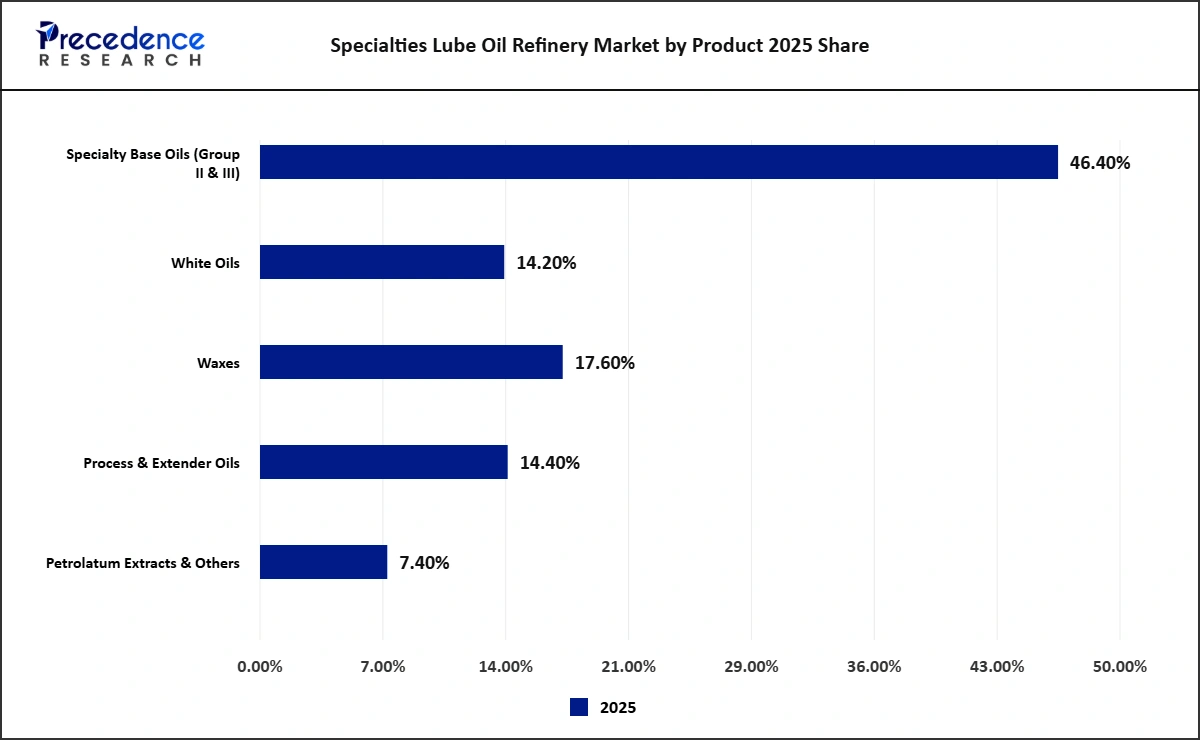
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Specialty base oils accounted for 46.40% with USD 3.44 billion in 2025 because Group II and Group III base oils are required for modern low-viscosity engine oils and premium industrial lubricants, and new specifications such as ILSAC GF-7 and API SQ favour high-viscosity-index stocks. Group III is the fastest-growing product as refiners add hydrocracker-based capacity in Europe and the United States. Waxes, at 17.60% with USD 1.31 billion, serve packaging, candles, rubber and hot melts. Process and extender oils account for 14.40% with USD 1.07 billion, white oils for 14.20% with USD 1.05 billion, and petrolatum, extracts, and others for 7.40% with USD 0.55 billion.
Specialties Lube Oil Refinery Market by Application 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Automotive Lubricants | 38.20% | USD 2.83 billion |
| Industrial Lubricants | 19.40% | USD 1.44 billion |
| Personal Care & Pharmaceuticals | 12.60% | USD 0.93 billion |
| Packaging, Candles & Consumer Products | 14.20% | USD 1.05 billion |
| Rubber, Polymers & Others | 15.60% | USD 1.16 billion |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Automotive lubricants accounted for 38.20% with USD 2.83 billion in 2025 because engine oils and transmission fluids use the largest volumes of premium base oils. Industrial lubricants account for 19.40% with USD 1.44 billion, personal care and pharmaceuticals for 12.60% with USD 0.93 billion, packaging, candles and consumer products for 14.20% with USD 1.05 billion, and rubber, polymers and others for 15.60% with USD 1.16 billion. Personal care and pharmaceuticals are the fastest-growing applications for high-purity white oils.
- Analyst View: Segment values were allocated by matching specialty output volumes and prices to products and applications, using refiner revenue mixes. Specialty base oils lead because of premium lubricant demand. We expect Group III base oils and white oils to gain share as Group I capacity declines.
Regional Analysis
Specialties Lube Oil Refinery Market by Region 2025 Share
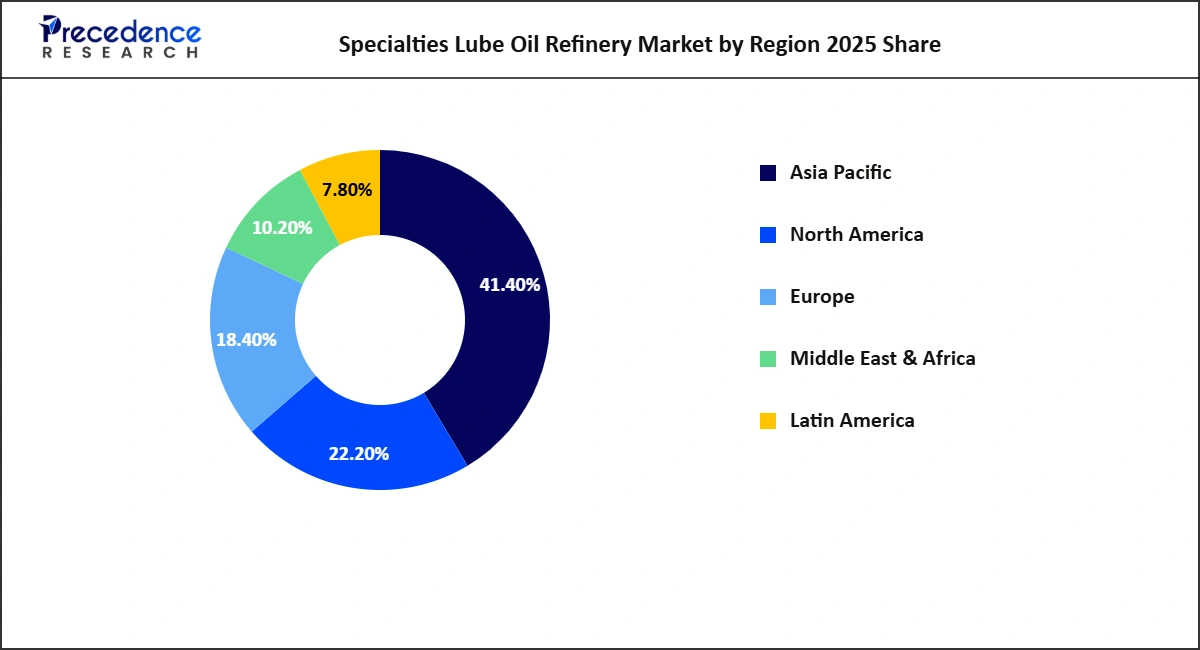
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Asia Pacific accounted for 41.40% with USD 3.07 billion in 2025, supported by Group III leaders in South Korea, large Group II plants in Singapore and China, strong lubricant demand, and exports to other regions. North America, at 22.20% with USD 1.65 billion, is supported by Group II capacity, specialty naphthenic and white oil refiners, and new Group III projects. However, the region remains a net importer of Group III.
Europe, at 18.40% with USD 1.37 billion, is supported by specialty refiners and repurposing of fuel refineries for Group III, while Group I closures reduce conventional output. The Middle East and Africa, at 10.20% with USD 0.76 billion, is the fastest-growing region, driven by Group III capacity in the Gulf, while Latin America accounts for 7.80% with USD 0.58 billion.
Asia Pacific accounted for 41.40% with USD 3.07 billion in 2025. South Korean refiners such as SK Enmove and S-Oil are major Group III exporters. Singapore and China host large Group II plants. Growing vehicle fleets increase lubricant demand.
North America accounted for 22.20% with USD 1.65 billion in 2025. Group III made up only about 4% of the region's base oil capacity in 2025, so imports from Asia remain important. Chevron's Pascagoula Group III unit is scheduled to start in late 2026 and ExxonMobil's Baytown plant in 2028. HF Sinclair plans to spin off its lubricants and specialties segment and signed a Group III supply deal with SK Enmove in 2026.
Europe accounted for 18.40% with USD 1.37 billion in 2025. Shell is repurposing the Wesseling hydrocracker in Germany to produce about 300,000 tonnes per year of Group III base oils later this decade. Group I closures reduce conventional supply. Specialty refiners produce white oils and waxes.
The Middle East and Africa accounted for 10.20% with USD 0.76 billion in 2025 and is the fastest-growing region. Gulf refiners produce Group III base oils for export. New refining complexes add specialty capacity.
Latin America accounted for 7.80% with USD 0.58 billion in 2025. Brazil and Mexico import much of their premium base oil. Regional refiners produce Group I base oils and waxes.
Analyst View: Regional shares were built from specialty output, capacity, and prices in each region. Asia Pacific leads because of Group II and Group III capacity. We assign the Middle East and Africa the highest growth premium because new Group III and specialty capacity is expanding fastest there.
Top 10 Companies in the Specialties Lube Oil Refinery Market
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | ExxonMobil | 1.08 | 14.56% | EHC Group II and Group III base oils, waxes | United States |
| 2 | Shell | 0.86 | 11.59% | Group III and GTL base oils | United Kingdom |
| 3 | SK Enmove | 0.62 | 8.36% | YUBASE Group III base oils | South Korea |
| 4 | Chevron | 0.58 | 7.82% | Group II base oils | United States |
| 5 | S-Oil | 0.42 | 5.66% | Ultra S Group III base oils | South Korea |
| 6 | Sinopec | 0.40 | 5.39% | Base oils and waxes | China |
| 7 | HF Sinclair | 0.36 | 4.85% | Base oils, white oils and specialties | United States |
| 8 | Calumet | 0.30 | 4.04% | Specialty oils, waxes and white oils | United States |
| 9 | H&R Group | 0.28 | 3.77% | Waxes, white oils and process oils | Germany |
| 10 | Nynas | 0.26 | 3.50% | Naphthenic specialty oils | Sweden |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
ExxonMobil led the specialties lube oil refinery market with an estimated 14.56% with USD 1.08 billion of 2025 revenue, followed by Shell at 11.59% with USD 0.86 billion and SK Enmove at 8.36% with USD 0.62 billion. ExxonMobil leads with large Group II and Group III base oil capacity and specialty wax production, and is building a 400,000-tonne-per-year Group III plant at Baytown due in 2028. Shell produces Group III and gas-to-liquids base oils and is repurposing its Wesseling hydrocracker for Group III, while SK Enmove is the largest Group III producer with its YUBASE brand and a 2026 supply and distribution partnership with HF Sinclair in North America. Chevron, S-Oil, Sinopec, HF Sinclair, Calumet, H&R Group and Nynas compete in base oils, white oils, waxes and specialty naphthenic and process oils.
The top 10 companies accounted for an estimated 69.54% with USD 5.16 billion of 2025 revenue, while the remaining 30.46% with USD 2.26 billion was shared among national oil company refiners, regional Group I producers and white oil and wax specialists. The specialties lube oil refinery market is concentrated among integrated refiners with hydroprocessing capability, and competition centres on base oil quality, Group III availability, product purity, supply reliability, logistics and price. Capacity is shifting from Group I to Group II and Group III, and lubricant businesses are being restructured through spin-offs and long-term supply partnerships.
Recent Developments
- In August 2026, SK Enmove agreed to supply Group III base oils to HF Sinclair's Lubricants and Specialties segment over several years, with HF Sinclair becoming SK Enmove's exclusive distributor in key North American markets.
- In July 2026, HF Sinclair announced plans to spin off its Lubricants and Specialties segment as a publicly traded company and to retire much of its Group II/III base oil unit in Ontario by 2027.
Specialties Lube Oil Refineries Market Segments
By Product
- Specialty Base Oils (Group II & III)
- White Oils
- Waxes
- Process & Extender Oils
- Petrolatum, Extracts & Others
By Application
- Automotive Lubricants
- Industrial Lubricants
- Personal Care & Pharmaceuticals
- Packaging, Candles & Consumer Products
- Rubber, Polymers & Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Research Methodology
The specialties lube oil refinery market was defined as specialty base oils, white oils, waxes, process oils, petrolatum, and extracts produced by lube oil refineries worldwide. The 2025 base year was built bottom-up from specialty output by product and region and average selling prices, and checked top-down against the specialty and lubricant segment revenue of leading refiners. We allocated segment, regional, and company values from products, applications, and regional demand.
Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: Overall Market
The specialties lube oil refinery market is shifting toward premium base oils and high-purity specialties as refiners restructure capacity. Our estimate links demand to specialty output volumes and prices, so the forecast follows lubricant specifications, consumer product demand and capacity changes. The main upside comes from Group III and white oils, while the main risks are EV-driven engine oil decline and capital costs.
Sources and References
- Offshore Technology. "Shell to repurpose Wesseling refinery for base oils". 2024-01-29. Wesseling Group III. https://www.offshore-technology.com/news/shell-wesseling-germany/
- Argus Media. "HF Sinclair, SK Enmove partner on base oil supply". 2026-08-03. SK Enmove and HF Sinclair. https://www.argusmedia.com/en/news-and-insights/latest-market-news/2860208-hf-sinclair-sk-enmove-partner-on-base-oil-supply
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
