



Loader Market Size, Key Companies, Company Market Share, User Adoption, Technology Deployment, Revenue Growth, Competitive Positioning, and Demand Forecast
Laxmi Narayan, who specializes in the machinery and equipment industry, assesses the loader market at USD 39.08 billion in 2026 and expects it to reach USD 56.87 billion by 2035, expanding at a CAGR of 6.8%. loader market companies including Caterpillar Inc., Volvo Construction Equipment AB, Hitachi Construction Machinery Co., Ltd, Hyundai Heavy Industries Co., Ltd. remain prominent players, with demand concentrated across segments such as By Loader Type, By Payload Capacy, By Application, and By Region.
Source: https://www.precedenceresearch.com/loader-market
 Get a Sample
 Table Of Content


What is the Loader Market Size?
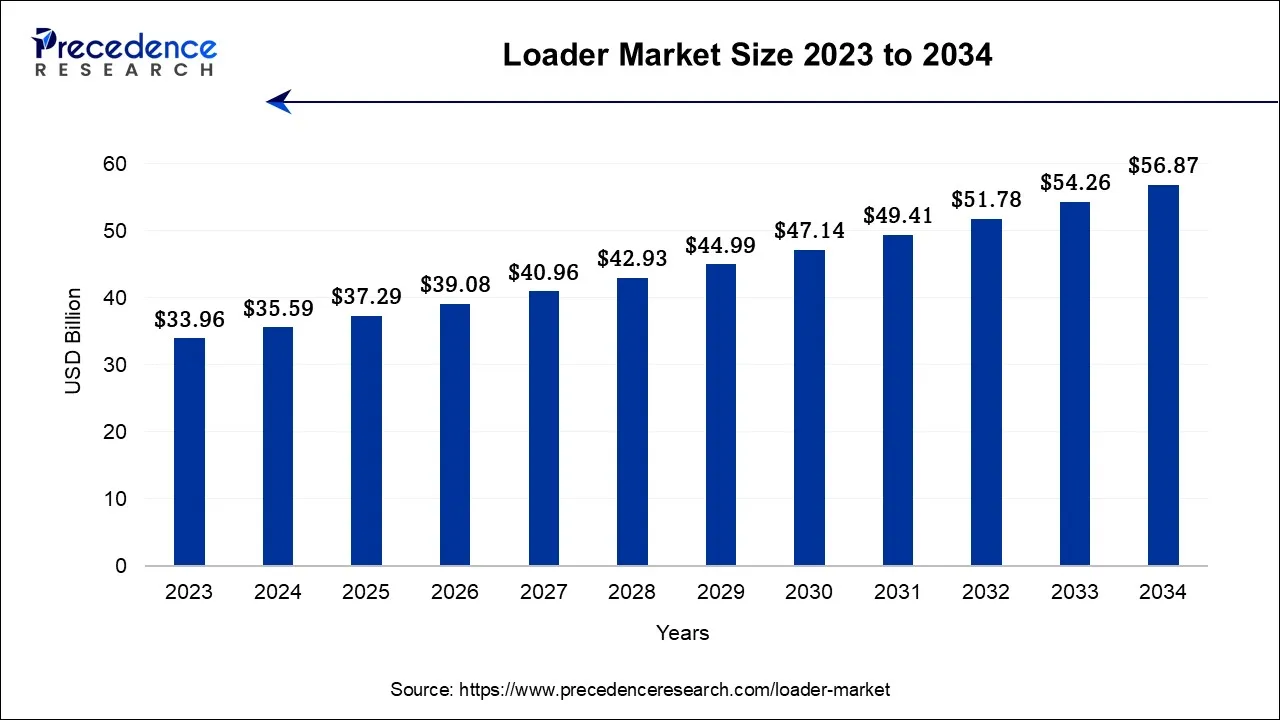
The global loader market size is expected to be valued at USD 39.08 billion in 2025 and is anticipated to reach around USD 56.87 billion by 2034, expanding at a CAGR of 6.8% over the forecast period from 2026 to 2034.
Market Highlights
- Asia-Pacific has held the highest revenue share of 39% in 2025.
- Europe region is estimated to observe the fastest expansion between 2025 and 2034.
- By Loader Type, the wheeled loader segment contributed 32.1% of revenue share in 2025.
- By Loader Type, the hardware segment is expected to expand at the fastest CAGR of 6.2% between 2025 and 2034.
- By Payload Capacity, the 6-10 tons segment captured the largest market share of 29% in 2025.
- By Payload Capacity, the 3-5 tons segment is expected to grow at the fastest CAGR over the projected period.
- By Application, the construction segment contributed 36.8% of revenue share in 2025.
- By Application, the waste management segment is anticipated to grow at the fastest CAGR over the projected period.
Market Size and Forecast
- Market Size in 2025: USD 37.29 Billion
- Market Size in 2026: USD 39.08 Billion
- Forecasted Market Size by 2034: USD 56.87 Billion
- CAGR (2025-2034): 6.80%
- Largest Market in 2024: Asia Pacific
- Fastest Growing Market: Europe
Market Overview
The loader market refers to the industry involved in the manufacturing, distribution, and sale of heavy equipment loaders. Loaders are versatile construction machines used for material handling, excavation, and loading tasks.
The market encompasses various loader types, including wheel loaders, skid steer loaders, and track loaders, serving sectors like construction, mining, agriculture, and logistics. It is characterized by continuous technological advancements, emissions regulations compliance, and a global presence, as loaders are essential equipment in various infrastructure and industrial applications.
The loader market is influenced by factors like urbanization, infrastructure development, and sustainability concerns, with an increasing focus on eco-friendly and efficient loader technologies.
Loader Market Growth Factors
- Construction and infrastructure development projects rely heavily on loaders for tasks like digging, earthmoving, and material handling, leading to a significant surge in market demand. As urbanization continues worldwide, the need for construction equipment, including loaders, remains high.
- Similarly, in the mining and quarrying industry, loaders are indispensable for excavation and transportation of materials. With global demand for minerals and aggregates, the mining sector's growth drives continuous demand for loaders, making it a vital market segment for this heavy equipment.
- Moreover, material handling and agriculture significantly boost demand in the loader market. In material handling, loaders facilitate efficient movement of goods in warehouses and logistics centers, optimizing supply chain operations. In agriculture, loaders are essential for tasks like loading/unloading crops, handling heavy materials, and clearing land.
- The mechanization of farming practices increases productivity and reduces labor requirements. These industries' reliance on loaders for improved efficiency and productivity drives sustained market demand, especially as industries seek to modernize and streamline their operations.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 37.29 Billion |
| Market Size in 2026 | USD 39.08 Billion |
| Market Size by 2034 | USD 56.87 Billion |
| Growth Rate from 2025 to 2034 | CAGR of 6.80% |
| Largest Market | Asia-Pacific |
| Base Year | 2025 |
| Forecast Period | 2025 to 2034 |
| Segments Covered | Loader Type, Payload Capacity, Application, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Market Dynamics
Drivers
Technological advancements and emissions regulations
Technological advancements are a significant driver of market demand in the loader industry. Integration of advanced technologies like GPS for precise navigation, telematics for remote monitoring, IoT connectivity for data analysis, and automation for increased efficiency and safety have revolutionized loader operations. These innovations enhance productivity, reduce operating costs, and improve operator comfort. As industries increasingly adopt these advanced features, the demand for modern, tech-enabled loaders continues to rise, sustaining market growth.
Moreover, emissions regulations drive demand in the loader market as they push manufacturers to develop advanced, safe, more fuel-efficient equipment. Compliance with stringent emission standards ensures environmental responsibility and aligns with sustainability goals. This compels industries to invest in newer, eco-friendly loaders, resulting in increased market demand for greener machinery.
Restraints
High initial cost and maintenance expenses
The high initial cost of loaders acts as a significant restraint on market demand. Potential buyers, especially smaller businesses, and contractors with limited budgets, may find it challenging to afford these capital-intensive machines. This financial barrier can lead to delayed or postponed purchase decisions, limiting market growth.
Buyers often seek alternative equipment options or used loaders, impacting sales volume, and affecting the overall market dynamics, particularly in regions with budget-conscious customers. Additionally, maintenance expenses deter market demand for loaders as they contribute significantly to the total cost of ownership. High maintenance costs burden buyers and operators, impacting profitability and return on investment. This can lead potential customers to seek more cost-effective alternatives or delay equipment purchases, slowing market growth, which restrains the demand for the loader market.
Opportunities
Customization and rental market
Customization in the loader market caters to diverse industry needs, increasing market demand. Tailored loader configurations enable buyers to choose equipment that precisely fits their specific applications, enhancing operational efficiency and productivity. This flexibility attracts a broader customer base, driving demand for loaders with personalized features and capabilities. Moreover, the rental market boosts demand for loaders as it offers a cost-effective alternative to purchasing.
Construction companies and industries often prefer renting loaders for short-term projects to minimize upfront costs and maintenance responsibilities. This dynamic expands the customer base, increasing market demand as rental companies frequently update their fleets to meet client needs, driving the purchase of new loaders. Additionally, it allows potential buyers to test different loader models before making a purchase decision, further stimulating demand.
Segments Insights
Loader Type Insights
According to the loader type, the wheeled loader segment has held a 32.1% revenue share in 2025. A wheeled loader is a type of heavy equipment used in construction, mining, and material handling. It features wheels for mobility and a front-mounted bucket or attachment for tasks such as digging, lifting, and loading materials. In the loader market, the trend for wheeled loaders includes the integration of advanced technology like GPS for precise operation, improved fuel efficiency, and reduced emissions to meet environmental regulations. Manufacturers are also focusing on operator comfort and safety through ergonomic cab designs and enhanced visibility.
The hardware sector is anticipated to expand at a significant CAGR of 6.2% during the projected period. Mini loaders, also known as compact loaders, are a type of loader characterized by their smaller size and maneuverability. They are versatile machines used in construction, landscaping, agriculture, and material handling tasks. In the loader market, the trend toward mini loaders is driven by the need for compact equipment that can access confined spaces. Technological advancements, such as improved ergonomics and enhanced safety features, have further boosted the popularity of mini loaders for various applications, including urban construction and landscaping projects.
Payload Capacity Insights
By payload capacity, the 6-10 tons segment is anticipated to hold the largest market share of 29% in 2025. In the loader market, loaders with a payload capacity of 6-10 tons represent a versatile category that caters to a wide range of applications. These loaders are commonly used in construction, mining, and material handling operations. Recent trends indicate a growing demand for fuel-efficient and eco-friendly loaders within this payload capacity range, driven by environmental regulations. Manufacturers are also integrating advanced technologies, such as telematics and automation, to enhance operational efficiency and safety in this segment.
On the other hand, the 3-5 tons segment is projected to grow at the fastest rate over the projected period. In the loader market, loaders with a payload capacity of 3-5 tons are versatile workhorses used across various industries. They efficiently handle medium to heavy-duty tasks such as loading and transporting materials in construction, mining, and logistics sectors. A notable trend in this segment is the integration of advanced technology, including telematics for real-time monitoring and automation for improved efficiency. Loader manufacturers are also focusing on enhancing operator comfort and reducing emissions to align with stringent environmental regulations, driving sustainable growth.
Application Insights
In 2025, the construction sector had the highest market share of 36.8% on the basis of the application. In the loader market, the construction segment pertains to the use of loaders in various construction activities, including earthmoving, material handling, and site preparation. A notable trend in this segment is the integration of advanced technology, such as GPS and telematics, to enhance precision and productivity. Additionally, loaders designed for compactness and maneuverability are gaining popularity, especially in urban construction projects. Sustainability is another emerging trend, with manufacturers focusing on eco-friendly loader designs to comply with environmental regulations.
The waste management segment is anticipated to expand at the fastest rate over the projected period. Waste management in the loader market refers to the utilization of loaders for efficient collection, transport, and disposal of waste materials. This application has gained prominence due to increasing environmental concerns and regulations. Loader trends in waste management include the development of specialized waste-handling attachments, such as grapple buckets and forks, to improve waste-handling efficiency. Additionally, loaders with advanced telematics and monitoring capabilities help optimize routes and reduce operational costs in waste management operations.
Regional Insights
Asia Pacific Loader Market Size and Growth 2025 to 2034
The Asia Pacific loader market size is accounted for USD 14.54 billion in 2025 and is projected to be worth around USD 22.46 billion by 2034, poised to grow at a CAGR of 6.97% from 2025 to 2034.
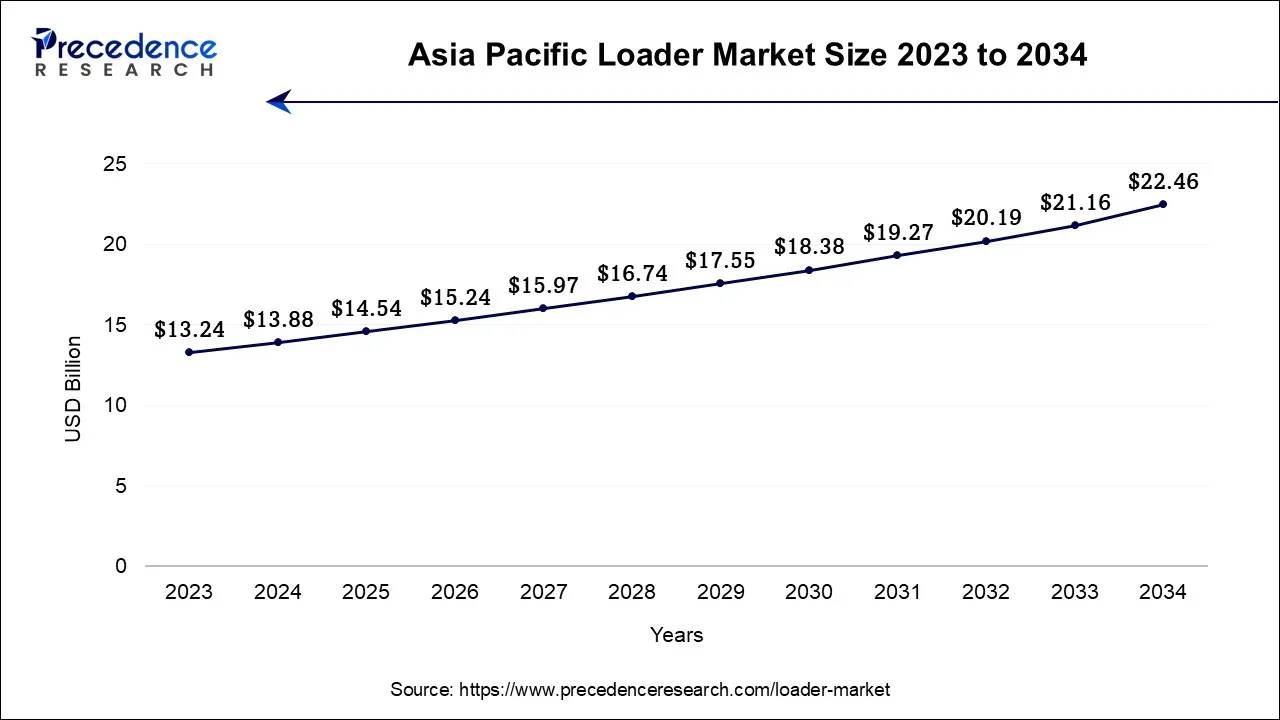
Asia-Pacific has held the largest revenue share at 39% in 2025. In the Asia-Pacific region, the loader market is witnessing robust growth due to extensive infrastructure development projects in countries like China and India. Rapid urbanization, coupled with increased construction activities, is driving demand for loaders. Additionally, the agricultural sector's mechanization and the growth of the mining industry contribute to the market's expansion. Manufacturers are also focusing on introducing technologically advanced and environmentally friendly loaders to meet evolving customer preferences and stringent regulations in the region.
China Market Trends
China's loader market is anticipated to grow significantly. Roads and bridges, railways, and urban development are the key drivers for loader demand. It has also seen expansion in the market as a result of the development of mining and material-handling operations. The government has made investments in infrastructure modernization, which are driving the use of modern construction machines. The growing need for efficient and technologically higher-performing machinery is helping upgrade equipment.
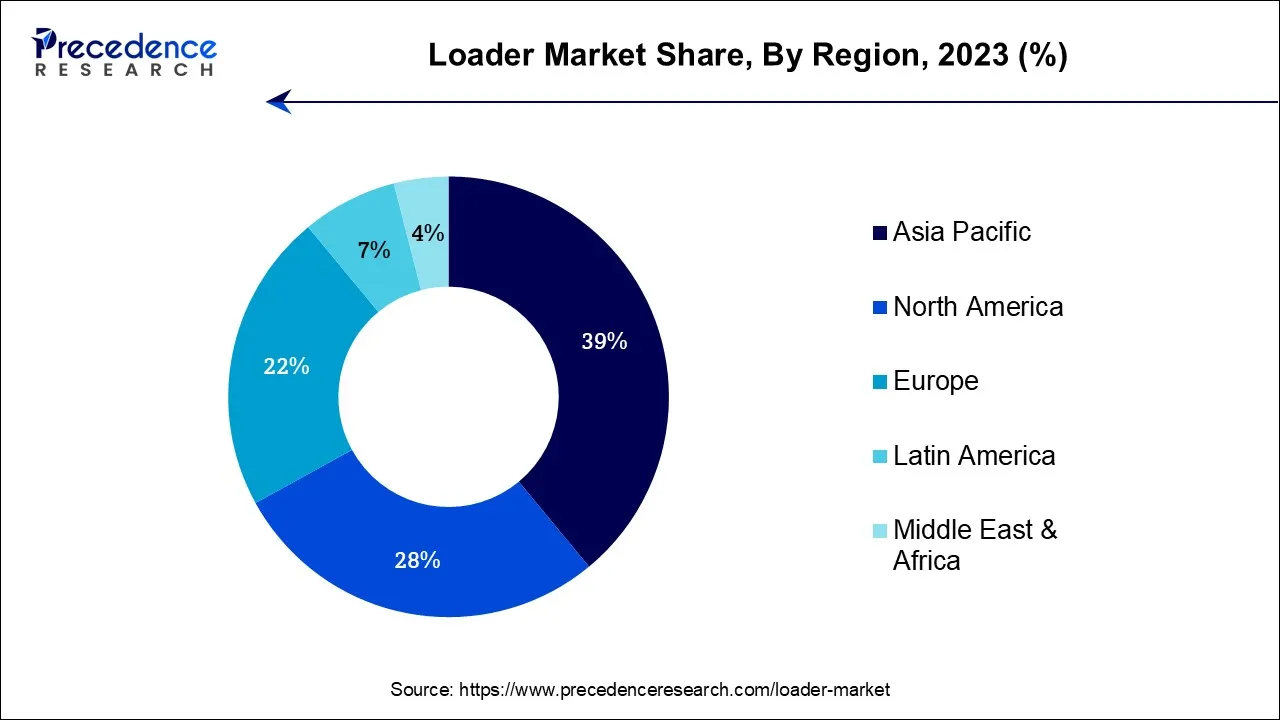
Europe is estimated to observe the fastest expansion. In Europe, the loader market is experiencing several noteworthy trends. The demand for loaders remains strong due to ongoing construction projects and infrastructure development across the continent. Additionally, there is a growing emphasis on sustainability, with manufacturers increasingly focusing on eco-friendly loader models. Technological integration, such as automation and telematics, is also on the rise, enhancing loader efficiency and operator safety. Europe's loader market reflects a commitment to modernization, environmental responsibility, and improved machinery performance.
North America is Undergoing the Fastest Growth in the Loader Market
North America is expected to grow at the fastest rate in the market. Trading in road equipment is benefiting from government spending on roads, bridges, and public infrastructure. The growth of housing and commercial building is fueling increasing loader use. New market opportunities are opening up due to the increasing popularization of electric and low-emission construction machinery.
U.S. Market Trends
U.S. market is anticipated to grow significantly due to more construction, infrastructure building, and material handling. The demand for loaders continues to rise as more residential homes, commercial and retail buildings, and industrial facilities are built. Rising emphasis on fuel efficiency, automation, telematics, and low-emission components is being addressed by the equipment manufacturers.
Advancements in the Loader Market in Europe
Europe is expected to witness significant market growth throughout the forecast period due to infrastructure spending along with construction modernization. The increasing use of automation, telematics, and smart fleet-management systems is helping to make fleet equipment more productive. The demand is also being driven by renovation of ageing infrastructure and developments in urban expansions.
Germany Market Trends
The German market is anticipated to grow significantly, driven by the country's construction and infrastructure development, manufacturing, and material handling investment. The drive towards emission reduction will be a factor in promoting the use of electric and fuel-efficient machinery. As more loaders come onto the market, manufacturers are introducing more automation, telematics, and advanced control options.
Key Trends in the Loader Market in Latin America
Latin America is expected to witness significant growth in the market due to the rising amount of infrastructure construction, mining activities, and investments. Demand for multi-purpose, versatile earthmoving equipment is growing with the expansion of roadway, residential, and commercial projects. The construction sector is benefiting from urbanisation in the main economies of the region.
Brazil Market Trends
Brazil loader market is anticipated to grow significantly due to the development of its infrastructure, its construction sector, agriculture, and mining. Equipment demand is supported by government & private investments for roads, transportation, housing, and urban infrastructure. Fuel efficiency and increasingly advanced equipment are helping to drive fleet modernization.
Growth of the Middle East and Africa in the Loader Market
The Middle East and Africa region is expected to witness significant growth in the market with investment in infrastructure, construction, mining, and the energy sector. The growth in commercial, residential, and tourism development is an additional factor promoting the market for loaders. Manufacturers are taking to the market increasingly rugged and capable loaders designed for challenging operations.
Saudi Arabia Market Trends
Saudi Arabia market is anticipated to grow significantly, as a result of numerous infrastructure, construction, tourism, and urban development projects. Investments in travel, housing, industrial facilities, and key development projects are being promoted through economic diversification initiatives. Heavy construction and material-handling equipment are also experiencing growth as a result of the expansion of mining.
Supply Chain Analysis-Loader Market
- Raw Material Sourcing: Industry experts in the provision of steel, aluminum, rubber, plastic, hydraulic components, engines, sensors, and electronic systems. Efficient sourcing organizations can ensure the quality of material provisions, cost control, continuity in provisions, and adherence to required performance and safety standards, thus guaranteeing a material environment.
- Installation and Commissioning: Installation and commissioning consist of equipment delivery, final assembly, configuring the system, inspection and calibration, and operational testing. Dealers and service personnel further provide operator training and technical support for safe, efficient, and reliable use of loaders.
- Monitoring and After-Sales Service: After-sales services comprise preventive maintenance, service department checkout, parts service, warranty, technical support, software maintenance, operator training, etc. Good service networks can contribute to equipment downtime minimization, maximum operating life span of the equipment, and greater customer satisfaction.
Competitive Landscape
The loader market is competitive, with several companies involved in this industry spanning the entire heavy industry line and specialty construction machinery firms. Some of the key players include Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment AB, John Deere, and JCB, with strong market presence across the globe. Firms have an interest in developing sophisticated loading technologies, improving fuel efficiency, automating, going electric, implementing telematics and operator safety measures to bolster their market position.
Raw material prices for market players, pollution norms and deep-seated concerns within the supply chain, the growing demand for technologically advanced equipment, and other factors are posing stringent challenges for the market players. Leading equipment brands face big prospects thanks to the rise in infrastructure spending, construction work, mining resorts, equipment replacement, and the transition to electric and autonomous equipment.
Company Profiles - Loader Market
Caterpillar Inc.
Headquarters: Irving, Texas, U.S.
Founded: 1925
Ownership: Public
- Business Overview: A world leader in the production of road, earthmoving, and excavating equipment for the construction and mining industries. The company is established for manufacturing various classes of heavy equipment, such as loaders, in the construction industry, infrastructure, material handling, quarrying, and the mining industry.
- Products: These cover loading systems such as wheel loaders, track loaders, compact track loaders, skid steer loaders, attachments, and technologies.
- Geographic Presence: Caterpillar has a presence in most areas of North America, Latin America, Europe, Asia Pacific, the Middle East, and Africa.
- Recent Developments: The updated 2026 suite of Caterpillar advanced equipment products has been constantly developed and improved, advancing to a higher level of automation, connectivity, and emissions reduction.
- Key Strategies: Product innovation, digitalisation/automation, sustainability, aftermarket services, and further developments in construction/ mining markets.
Volvo Construction Equipment AB
Headquarters: Gothenburg, Sweden
Founded: 1832
Ownership: Volvo Group
- Business Overview: Volvo Construction Equipment is one of the world's leading manufacturers of construction machines as well as part of the Volvo Group. It provides tools and solutions for construction and infrastructure, quarry & mineral, and material handling.
- Products: wheel loaders, articulated vehicles, excavators, compact machines, rigid haulers, and electric construction machines.
- Geographic Presence: Volvo CE manufactures and runs a dealer sales system in Europe, North America, Latin America, Asia Pacific, the Middle East, and Africa.
- Recent Development: Due to its development of more electric power equipment solutions and connected solutions that help to ensure more sustainable operations at construction sites, Volvo CE was able to make further progress in 2026.
- Key Strategies: Using equipment that is solutions-oriented to customers, productively improving yield, sustainable buildings, automation, electrification.
Hitachi Construction Machinery Co., Ltd.
Headquarters: Taito-ku, Tokyo, Japan
Founded: 1970
Ownership: Public
- Business Overview: Hitachi Construction Machinery is a worldwide producer of construction and mining equipment. The company offers Digital solutions and Machinery to simplify, optimize, and make equipment more productive and safe to use in operation.
- Products: It trades wheel loaders, hydraulic excavators, mining trucks, rigid dump trucks, and construction and mining equipment through its products.
- Geographic Activity: Hitachi Construction Machinery is operating and selling at various countries in the Americas, Europe, Asia, Africa, and Japan.
- Recent Development: Hitachi Construction Machinery has further developed autonomous, digital, and electrified equipment technology for various equipment systems related to construction and mining in 2026.
- Key Strategies: Digitalization, automation, electrification, productivity, after-market products and solutions for construction and mining.
Hyundai Heavy Industries Co., Ltd.
Headquarters: Ulsan, South Korea
Founded: 1972
Ownership: HD Hyundai Construction Equipment
- Business Overview: HD Hyundai Construction Equipment is the top manufacturer of construction machinery, including excavators, wheel loaders, and material handling equipment. The company has worldwide industrial, mining, agricultural, and infrastructure customers.
- Products: It is involved in the manufacturing of multiple types of material handling equipment, earth-moving machinery, such as wheel loaders, excavators, compact construction equipment, forklift trucks, etc.
- Geographic Presence: The company's sales and dealer coverage is globally spread across Asia, Europe, North America, Latin America, the Middle East, and Africa.
- Recent Development: The company has been continuing the work on smart construction machines built with the concepts of Automation, Networking, Fuel efficiency, and Electrification.
- Key Strategies: Smart construction solutions, diversification of products, technological innovation, electrification, operational effectiveness, and international market development.
SANY Group Co., Ltd.
Headquarters: Changsha, Hunan, China
Founded: 1989
Ownership: Privately held
- Business Overview: SANY Group is a top manufacturer of heavy construction equipment and industrial equipment in China. This company's business is the manufacture, development, and production of construction machinery, infrastructure development machinery, mining machines, port machines, and industrial machines.
- Products: It has a product line of wheel loaders, excavators, cranes, concrete machines, road machines, port machines, and mining machines.
- Geographic Presence: SANY has a strong international presence in Asia, Europe, North America, Latin America, as well as in the Africa and Middle East regions.
- Recent Development: SANY kept on developing intelligent, electric, and digitally interconnected construction equipment to meet the demand from around the world for efficient equipment.
- Key Strategies: Push for international expansion, intelligent manufacturing, electrification, automation, development of new products, and enhancing the global dealer and service network.
Kawasaki Heavy Industries, Ltd.
Headquarters: Tokyo, Japan
Founded: 1896
Ownership: Public
- Business Overview: Kawasaki Heavy Industries boasts five business segments: aerospace, energy, transportation, industrial machinery, and hydraulic equipment. It has hydraulic machinery operations to supply the latest hydraulic technologies and components to construction machinery companies.
- Product: The product portfolio of its includes hydraulic pumps, hydraulic motors, hydraulic valves, control systems, and hydraulic products in construction and heavy machinery.
- Geographic Presence: Kawasaki Heavy Industries operates all over the world, including in the Asia Pacific region, N.A., and E.U., as well as other markets.
- Recent Development: Kawasaki has been developing advanced hydrotechnologies to further enhance the efficiency of heavy machinery, their performance, as well as the potential for electrification, in the year 2026.
- Key Strategies: High-level energy efficiency, industry markets, electrification, automation, innovative hydraulic technology and engineering.
Terex Corporation
Headquarters: Norwalk, Connecticut, U.S.
Founded: 1933
Ownership: Public
- Business Overview: Terex Corporation is an international business, manufacturing lifting, material-processing, and special construction equipment. Its customers are in construction, infrastructure, construction utilities, recycling, aggregates, and industrial areas throughout the world.
- Products: Pumps, aerial work machines, cranes, material processing machines, conveyors, crushers, screening equipment, and machinery.
- Geographic Presence: Terex has manufacturing and sales facilities in North America, Europe, Asia Pacific, Latin America, and various other international markets.
- Recent Developments: In 2026, the focus of Terex's efforts moved to designing new products, streamlining existing ones, optimizing operations, and designing more advanced equipment for the construction and material-processing sectors.
- Key Strategies: Product innovation, portfolio development, how to serve the products, efficiency in operation, customer support, and Growth in the infrastructure and construction market.
Loader Market Companies
- Caterpillar Inc.
- Komatsu Ltd.
- Volvo Construction Equipment AB
- John Deere (Deere & Company)
- JCB (J.C. Bamford Excavators Ltd)
- Hitachi Construction Machinery Co., Ltd.
- Doosan Bobcat Inc.
- Liebherr Group
- CNH Industrial N.V.
- Hyundai Heavy Industries Co., Ltd.
- XCMG Group
- SANY Group Co., Ltd.
- Wacker Neuson SE
- Kawasaki Heavy Industries, Ltd.
- Terex Corporation
Recent Developments
- In 2023, Continental has partnered with Aurora, a leader in self-driving technology, to develop autonomous vehicle solutions. This collaboration aims to integrate Continental's expertise in vehicle technology with Aurora's autonomous driving platform for safer and more efficient transportation.
- In 2022, John Deere and Wacker Neuson: John Deere partnered with Wacker Neuson to sell a range of compact excavators under the John Deere brand, expanding their product offerings in the construction equipment market.
- In 2020, Doosan Bobcat and BOB-CAT Mowers: Doosan Bobcat acquired BOB-CAT Mowers, a manufacturer of commercial zero-turn mowers, diversifying its product range beyond loaders.
- In 2020, Caterpillar and Trimble have announced a change to their joint venture, reflecting their ongoing collaboration in the construction technology sector. This partnership is aimed at delivering integrated machine control solutions for construction equipment, including loaders, to enhance precision, productivity, and efficiency in various construction and earthmoving applications.
- In 2019, CNH Industrial and ATI Track: CNH Industrial acquired ATI Track Systems, a manufacturer of rubber track systems for construction equipment, enhancing its product portfolio for loaders.
- In 2018, Volvo CE and LEGO Technic: Volvo Construction Equipment partnered with LEGO Technic to create a miniature remote-controlled Volvo L350F Wheel Loader set, promoting awareness of construction equipment among younger audiences.
- In 2017, Komatsu acquired Joy Global, a mining equipment manufacturer, strengthening its presence in the mining loader segment. Komatsu-brand surface mining equipment with the P&H, Joy and Montabert brands of surface and underground products will allow to offer a complete range of mining solutions to customers.
Segments Covered in the Report
By Loader Type
- Skid Steer
- Backhoe
- Wheeled
- Crawl/Track
- Mini Loaders
By Payload Capacity
- 3-5 tons, 6-10 tons
- 11-15 tons
- 15 tons and above
By Application
- Mining
- Construction
- Waste Management
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
