
Kaolin Market Size, Key Companies, Company Production Capacity, Manufacturing Efficiency, Capacity Utilization, Raw Material Consumption, Cost Structure, Export Trends, Company Expansion Strategies, and Competitive Landscape
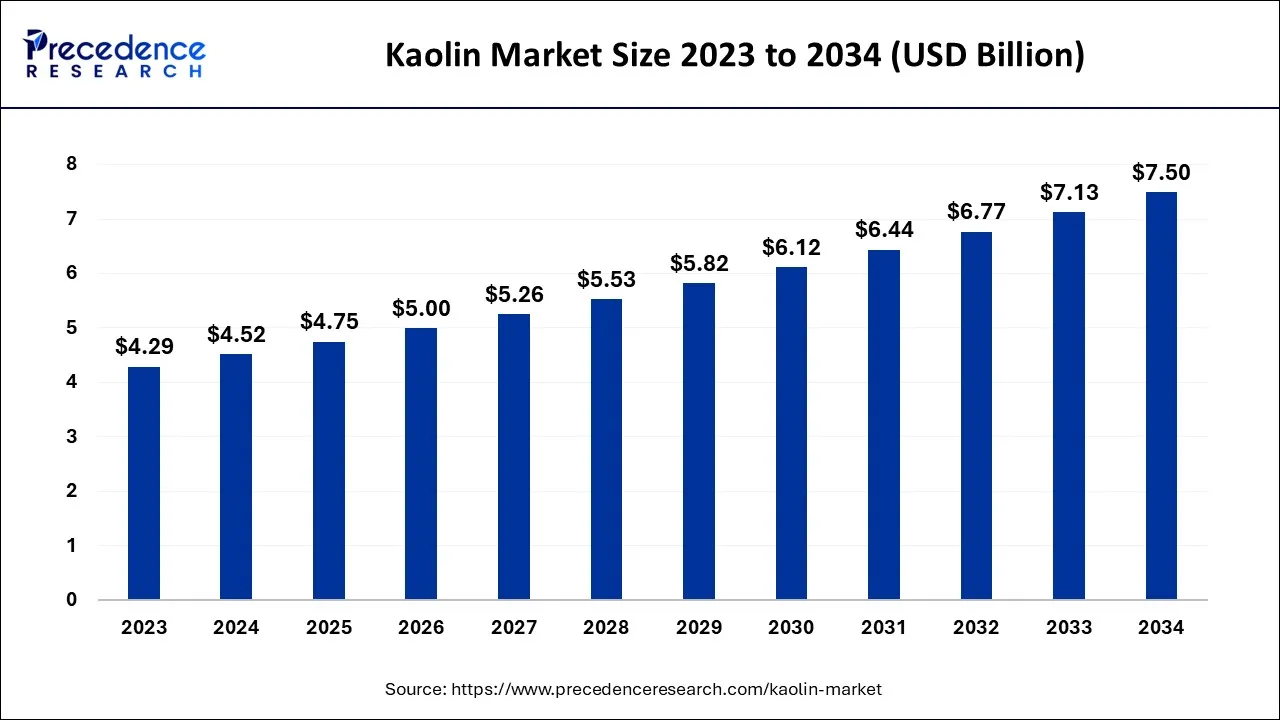
Vidyesh Swar, a Chemical and Materials Industry Expert, estimates the kaolin market at USD 5.00 billion in 2026, with the market projected to reach USD 7.50 billion by 2035 at a CAGR of 5.19%. Major kaolin market companies such as Kaolin AD, Quartz Works GmbHÂ , IMERYS, BASF SE are competing across key material and application segments, including By Type, By Process, By End-use Industry, and By Region.
Source: https://www.precedenceresearch.com/kaolin-market
 Get a Sample
 Table Of Content
What is the Kaolin Market Size?
The global kaolin market size is calculated at USD 4.75 billion in 2025 and is projected to surpass around USD 7.50 billion by 2034, growing at a CAGR of 5.19% from 2025 to 2034. Kaolin market growth driven by rising demand from ceramics, paints and coatings, plastics, paper, rubber, and construction industries worldwide.
Market Highlights
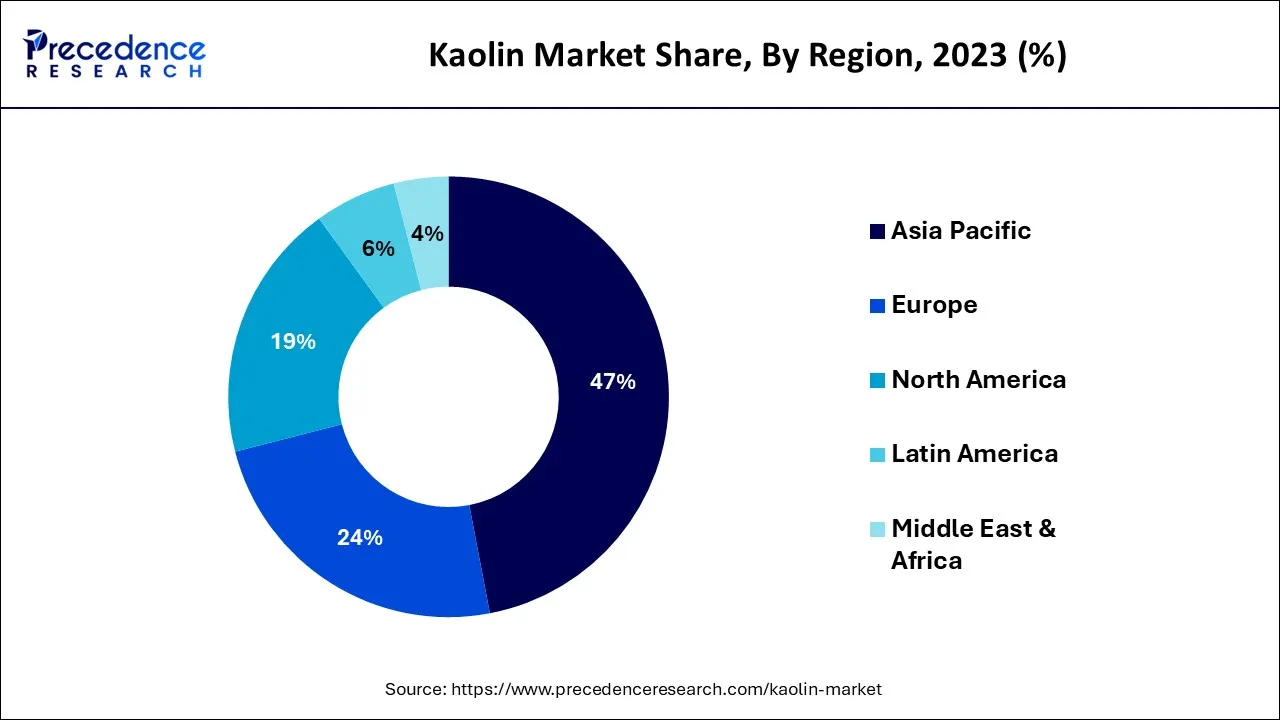
- Asia Pacific region generated more than 47% of revenue share in 2025.
- By Process, the water-washed segment is predicted to dominate the global market from 2025 to 2034.
- By End-use, the paints and coatings segment is expected to contribute the biggest revenue share from 2025 to 2034.
Market Size and Forecast
- Market Size in 2025: USD 4.75 Billion
- Market Size in 2026: USD 5.00 Billion
- Forecasted Market Size by 2034: USD 7.50 Billion
- CAGR (2025-2034): 5.19%
- Largest Market in 2024: Asia Pacific
Market Overview
Market Overview
China clay, often known as kaolin, Soft white clay is widely used in the creation of paper, rubber, paintings, and many other products. It is an essential component in the manufacture of China and porcelain. The hill in China known as Kao-ling, where it has been mined for centuries, is from which kaolin derives its name. In its natural state, kaolin is a white, porous powder mostly formed of the mineral kaolinite, which is thought to be made up of roughly hexagonal, plate crystals ranging in size from 0.1 microns to 10 microns or more. Vermicular and book forms, as well as occasionally macroscopic shapes that are close to millimeter diameters, can be adopted by these crystals. Moreover, iron hydroxide pigments are frequently used to dye unrefined kaolin yellow.
When making kaolin for industrial use, it is frequently necessary to chemically bleach the clay to get rid of the iron pigment and wash the other minerals with water. When kaolin is mixed with water at a 20 to 35 percent concentration, it transforms into plastic and keeps its shape even after pressure is released. The kaolin produces a slurry or watery suspension when there is higher water content. The kaolin market is being driven by the increasing construction activities across the globe, the growing cosmetic industry, the growing uses of kaolin in the paint and coating sector and the increasing use of kaolin in medicinal products.
Future market trends
- Pure Kaolin: The usage of pure kaolin is expected to increase especially in ceramics, paints, coatings and advanced materials so as to improve brightness and performance in specific applications.
- Ceramic Market: The increasing demand for premium tiles, ceramics, sanitaryware and technical ceramics will assist kaolin market growth in areas where kaolin fire qualities and plasticity add value.
- Green Processing: Kaolin producers will utilize green methods of mining, recycling of water, reducing wastes and greener manufacturing processes in order to minimize environmental impacts.
- New Applications: Kaolin product utilization will be expanding in specialized chemicals, specialized fillers, catalysts, polymers and engineered materials as new and advanced grades with certain properties are developed.
- Processing Location: Regions rich in kaolin will invest more in effective processing technologies and local kaolin processing to create value-added exports thus decreasing the amount of raw minerals imported abroad.
Market Outlook
Industry Trend Overview: A strong demand for kaolin is expected in various sectors including paper manufacturing, ceramics, paint and coating production, rubber processing, plastic production, refractory materials, and special industrial processes. The trend in product differentiation is gradually heading towards producing high-purity, calcined kaolin, engineered kaolin, and making grades dedicated for specific applications.
Global Development: Globalization of the kaolin market is characterized by more active use of kaolin in construction materials, ceramics, coatings, packaging, and advanced industry applications. Asia-Pacific is widely recognized as an important production and consumption center of kaolin. Producers are searching for new markets and developing processing and beneficiation methods closer to final users.
Sustainability Trends: According to the trend, the mining companies are improving efficiency of mineral based materials. Emerging companies can differentiate through customized particle sizes, surface modification, higher-purity grades, and application-specific formulations rather than competing solely on conventional bulk kaolin supply.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 4.75 Billion |
| Market Size in 2026 | USD 5.00 Billion |
| Market Size by 2034 | USD 7.50 Billion |
| Growth Rate from 2025 to 2034 | CAGR of 5.19% |
| Largest Market | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2025 to 2034 |
| Segments Covered | Type, Process, End-use Industry, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Market Dynamics
Drivers
Increasing demand for paper and ceramics product
Demand for kaolin is anticipated to increase along with the demand for ceramic and paper products. After being formed and hardened by heating to high temperatures, a ceramic is a product made of either metal or non-metal compounds. Paper goods include items like paper towels, napkins, and corrugated papers created from wheat straw, flax, bamboo, wood, and sugar cane waste. By adjusting the gloss, smoothness, brightness, opacity, and printability of ceramic and paper, kaolin coating improves their visual appeal. For instance, the International Energy Agency (IEA), an independent international agency with headquarters in France, stated in November 2021 that the production of paper and paperboard worldwide climbed by 3% between 2010 and 2019 and was predicted to rise by 1.5% year through 2030. The kaolin market is going to be driven by the growing demand for paper and ceramic products.
Restraints
Decreased rate of medicinal absorption in kaolin consumers
In many food and drug compositions, kaolin is a crucial ingredient. However, it has been noted that the rate of absorption of some antibiotics and heart medications decreases when an individual has consumed kaolin in any form. In the bodies of people who use kaolin products, antibiotics like Clindamycin and Trimethoprim as well as cardiac medicines like Digoxin and Quinidine are absorbed more slowly. This important aspect is anticipated to significantly slow the market's revenue growth.
Opportunities
Technological advancements
The primary trend gaining traction in the kaolin market is technological developments in the production of kaolin. Major players in the market are adopting cutting-edge kaolin production technology, which includes techniques like crushing, bunging, screening, magnetic separations, and others, to remove various impurities from kaolin and to properly design its features to guarantee smoothness. Key companies might get a competitive edge in the market due to such improvements. For instance, in July 2020, three companies—Metso Outotec of Finland, Imerys Minerals Ltd. of France, and PREDICT of France—partnered with three universities, including Aalto University, Technische Universiteit Delft, and Delft University. These companies provided sustainable technologies, end-to-end solutions, and services for the processing of minerals. The MONICALC project intended to develop a high-quality, energy-efficient kaolin manufacturing method.
The calcination of kaolin may be made more efficient while using less energy, which reduces CO2 emissions. This is the goal of the integrated method being investigated by the MONICALC project. Thus, this is expected to drive the growth of the market over the forecast period.
Segments Insights
Process Insights
Based on the process, the global kaolin market is segmented into water-washed, air-floated, calcined, delaminated, surface-modified, and unprocessed. The water-washed segment is expected to dominate the market over the forecast period. To attain the desired particle size, purity, residue, and brightness, water-washed kaolin must undergo an extensive production process that involves slurring, grinding, crushing, sorting, centrifuging, sifting, chemically and perhaps concentrated drying, and magnetic treatment. Since the 14% bound water of hydration present in crude kaolin is still present, water-washed kaolin is hydrous kaolin.
The calcined segment is expected to grow exponentially during the forecast period. The basic material for the heat treatment process known as calcination, which produces calcined kaolins, is water-washed kaolin. Based on the desired finished product, water-washed feed kaolin is chosen for processing. Because calcined kaolin is anhydrous, the 14% bound water of hydration present in raw clay has been removed during the calcining process. Calcined kaolin can be used to control the shrinkage and plasticity of slips (engobes) used on wet or leather-hard pottery in addition to being widely utilized in ceramic glazes. Kaolin that has been calcined softens at around cone 35 and is refractory. Its uses include investment casting, low expansion bodies, thermal insulation bodies, refractory castables and furnishings, and permeable ceramic compositions. Thus, this is expected to drive the growth of the segment during the forecast period.
End-use Industry Insights
Based on the end-use industry, the paints and coatings are expected to capture the largest revenue share over the forecast period. Kaolin is a crucial component of paint formulas and is used as a filler in paint. This substance enhances paint film development, adds gloss to painted surfaces, inhibits quick collapse, boosts wear resistance against various weather conditions, and slows moisture absorption. Kaolin is a chemical that the coatings industry is utilizing more and more because it improves tint strength and opacity, sheen control, scrub and stain resistance, holdout, and pigment suspension in architectural coatings. Kaolin-based paints offer much higher-quality finished painted goods and improve the functionality of painted surfaces, which is driving up mineral demand in the market and accelerating this segment's revenue growth.
Regional Insights
Asia Pacific Kaolin Market Size and Growth 2025 to 2034
The Asia Pacific kaolin market size is exhibited at USD 2.23 billion in 2025 and is projected to be worth around USD 3.56 billion by 2034, growing at a CAGR of 5.31% from 2025 to 2034.
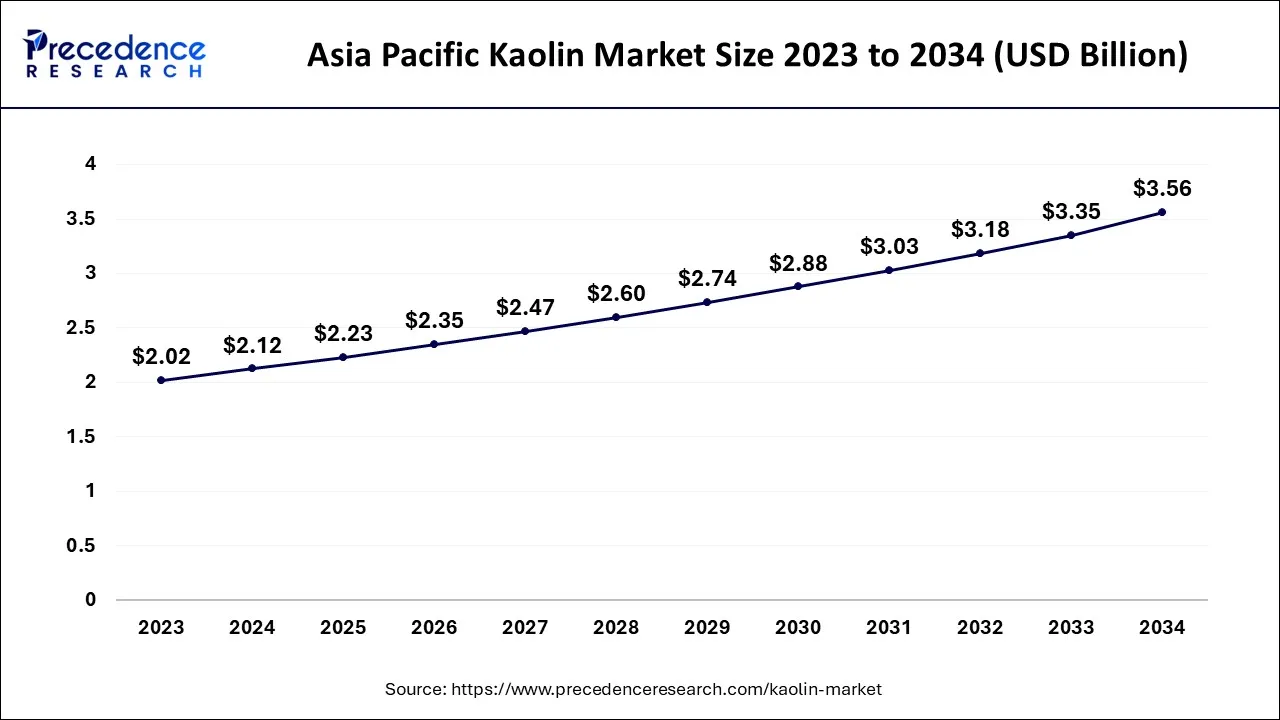
The Asia Pacific region is expected to capture the largest market share in 2025. The regional growth is attributed to the increasing construction industry in the nation like India and China. The construction industry rises owing to the rapid urbanization in these nations. For instance, according to the National Institutes of Indian Affairs, Indian cities are going through a makeover. Since 1951, there has been a six-fold increase in the urban population, from 62.4 million in 2011 to an expected 590 million in Indian cities by 2030, which is twice the population of the United States. Moreover, according to the report of CEIC, building construction in Beijing totaled 237,142 square meters in 2020, a 5% increase over the previous year.
China
China has established itself as one of the strongest countries due to its successful ceramic manufacturing facility, paper industry, major construction activities, and industrial coatings. Growth of local manufacturing plants and boosting demand for kaolin materials resulted in considerable investments into development and usage of processing technologies by this country, which is significant for regional production and consumption.
Further, the growing cosmetic industry in the region is expected to provide enormous opportunities for market growth during the forecast period. Kaolin is widely used in skin care products including face masks and others. For instance, as per Euromonitor International research, the sales of beauty and personal care products in China reached USD 88 billion in 2021, a spike of 10% from the previous year. Thus, this is expected to drive the market growth during the forecast period.
North America is expected to capture the largest market share during the forecast period. The growth in the region is attributed to the increasing production and export of kaolin minerals. For instance, as per OEC, the US is the top exporter of kaolin in 2021 which was around USD 604 million. Moreover, the increasing demand from the paper and packaging industry is expected to drive the forecast period.
U.S.
The leading country in North America is the United States, mainly due to its abundant kaolin reserves, especially in Georgia, thus providing consistent demand from various industries for use in paper, packaging, paints, plastics, rubber, ceramics, and fiberglass applications. Strong processing abilities and an industrial client base aid development of applications in specialty kaolin.
Europe is expected to hold a significant market share during the forecast period. The growth in the region is ascribed to the increasing demand for the component in rubber, plastics, paper and glass industries. Moreover, the growing construction industry in the region is expected to propel the market expansion. For instance, according to the European Construction Industry Federation, France construction activity increased by 10.5% in Volume in 2021.
Germany
Germany is the leading country in Europe, mainly due to its industrial development in ceramics, paper processing, coatings, plastic industries, and advanced materials. The increasing demand for specialty kaolin in various technical applications and the development of the manufacturing processes contribute to the growth of innovative resources in this country.
Competitive Landscape
The kaolin industry is partially concentrated, where well-established players operate with regional and specialized providers. Scale, mineral quality, processing capabilities, and reliable supply chains are the factors that affect competitive positioning and promote moderate entry barriers in the industry.
Top companies, like Imerys, KaMin, LB MINERALS, Thiele Kaolin, and Sibelco, utilize their large reserves, processing expertise, diversified portfolio, and vast geographic coverage to obtain competitive advantages. Smaller producers rely on special grades and niche products to achieve their competitive position. Competition in the industry depends on capacity increases, investments in processing technology, product development, and strategic partnerships to satisfy the customers from the ceramics, paper, paints, plastics, and specialized applications.
Quality reserves, high capital intensity of processing facilities, environmental standards, logistics infrastructure, and consumer qualification limitations stimulate the growth of the competition.
Company Profiles
Kaolin AD
HQ: Senovo, Bulgaria
Founded: 1924
Ownership: Private subsidiary of Quarzwerke Group
Company Overview: Kaolin AD is a well-known Bulgarian company engaged in the production of mineral resources. It specializes in the production of kaolin, silica sand, and other minerals used in various industries. It provides processed minerals used in ceramics, glass, construction, wood, and other industries. Vertically integrated operations are carried out in the sphere of mining and mineral having a direct impact on the quality of the product. Thus the quality of the finished goods is maintained throughout the process. Its membership in Quarzwerke Group enables it to keep up its world-class technologies in the field of minerals.
- Key Strength: Resource Quality: There are large kaolin deposits as well as other minerals. Integration of Processes: There is a direct connection between mining, processing, and distribution of minerals.
- Key Vulnerability: Vulnerability to Energy Prices: Energy prices have an impact on the final cost of the goods. High Level of Dependency on Demand: It heavily relies on demand in Europe.
Quartz Works GmbH
HQ: Frechen, Germany
Ownership: Private; part of Quarzwerke Group
Company Profiles: Quartz Works GmbH is part of the Quarzwerke Group, which is a European producer of industrial minerals such as quartz, kaolin, feldspar, and other similar products. The company works in a wide range of industrial sectors such as the ceramics industry, glass manufacturing, construction, and paint production. The company uses the infrastructure of the parent company for extraction, processing of minerals, quality assurance, and development of new products. Another advantage is the possibility of using top-quality raw materials and advanced technologies in processing. The company production and distribution framework in Europe provides quick access to the clients. In any case, the company is a victim of obstacles caused by legislation, environmental standards, costs related to transportation, and fluctuations in demand for the products.
Key Strength: Know-how in Minerals: Valuable experience in processing quartz and related minerals. Membership in the Group: Advantages of being a member of Quarzwerke Group and utilizing its distribution system.
Key Vulnerability: Regulatory Pressure: Growth of environmental norms imposing comprehensive restrictions on mining and other works in the industry.
Transport Costs: Transportation issue in the transportation of bulk materials.
Imerys
HQ: Paris, France
Founded: 1880
Ownership: Public - Euronext Paris
Company Overview: Imerys is a world's leader in mineral-based solutions, producing and processing a large variety of industrial minerals, including kaolin, calcium carbonate, talc, perlite, and diatomite. Kaolin products are applicable in different industries, including paper, ceramics, paints, plastics, rubber manufacturing, etc. Imerys combines unique mineral deposits with mineral-processing technologies, application knowledge, and an extensive network of manufacturing facilities located in various parts of the world. The company employs a diversified business model so that it can produce mineral products for several industries, thus minimizing risks of high dependency on one particular industry. Furthermore, the scale of the operations allows the company to invest in innovations, increase resource efficiency, and create fewer harmful mineral products.
- Key Strengths: International Scale: Large international mining, processing, and distribution network. Technical Skills: Strong technological capabilities in all sectors of kaolin use.
- Key Vulnerabilities: Complex Operation: Diversification of mineral operations requires complex resources and supply chain management. Environmental Issues: Mining and processing companies face various environmental challenges and needs for meeting the sustainability requirements.
BASF SE
HQ: Ludwigshafen, Germany
Founded: 1865
Ownership: Public -Frankfurt Stock Exchange
Based in Germany, BASF SE is a global chemical company with diversified operations including chemicals, polymers, semi-finished goods and agricultural solutions. The company is involved in kaolin indirectly by utilizing the clay in special mineral and formulated material applications. The company's research expertise in formulating mineral-based products and its large customer base enable it to formulate mineral-intensive solutions for coatings, plastics, construction, etc. A strong global presence aids the company in reaching out to the industrial market and cooperating with end customers.
- Key Strengths: Research & Development: Successful technological and formulation developments of the products in the field of advanced materials. Extensive Customer Base: Global relationships with customers in coatings, polymers, construction and other sectors.
- Key Vulnerabilities: Specialization in Kaolin: The company's specialization in kaolin production is not comparable with that of pure mineral companies. Diversity of Portfolio: Kaolin-related operations compete with various other activities of BASF in the chemicals sector.
Kaolin Market Companies
- Kaolin AD
- Quartz Works GmbH
- Imerys
- KaMin LLC
- BASF SE
- KERAMOST, a.s.
- I-Minerals
- EICL
- SCR-Sibelco NV
- Thiele Kaolin Company
Recent Developments
- In September 2022, in a joint announcement, BASF Inc. and KaMin LLC, a worldwide performance minerals business owned by IMin Partners announced they had successfully acquired the kaolin minerals division of BASF. By expanding its diversification into highly engineered, expanding market categories and expanding its already sizable portfolio of cutting-edge product solutions for everyday life, this purchase transforms KaMin from day one. A global leader with enormous scale, technical ability, and talent will be able to provide customers, distributors, and brand owners around the world greater value.
- In November 2020, Adromeda Metals (AND) has issued a fresh mineral resource estimate for the Great White Kaoline project joint venture. ADN owns 75% of the South Australian project, and Minotaur exploration owns remaining 25%.
- In March 2022, Imerys successfully sells some assets and mining resources in North America that supply hydrous kaolin to the paper and packaging industries to Thiele Kaolin Corporation, one of the leading manufacturers of processed kaolin clay.
Segments Covered in the Report
By Type
- Synthetic
- Natural
By Process
- Water-washed
- Air-Floated
- Calcined
- Delaminated
- Surface-Modified
- Unprocessed
By End-use Industry
- Ceramics and Sanitarywares
- Fiberglass
- Paints and Coatings
- Rubber
- Adhesives and Sealants
- Plastics
- Others
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample

 sales@precedenceresearch.com
 Schedule a Meeting