
Air Purifier Market Size, Key Companies, Company Technology / Innovation, Electronics Manufacturing Output, Supply Chain Metrics, Sales Volume, Technology Adoption, Company Investment Strategies, and Market Analysis
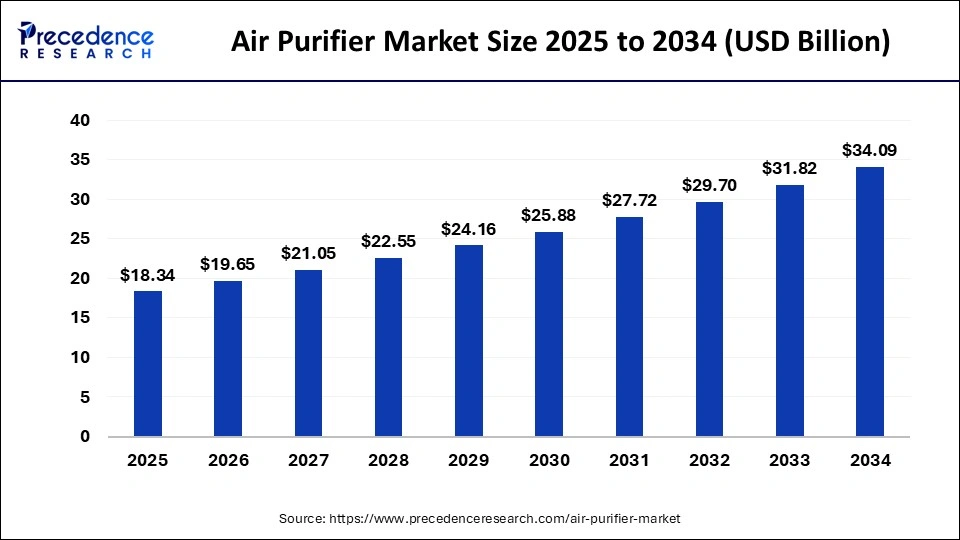
According to semiconductor and electronics specialist Laxmi Narayan, the air purifier market is valued at USD 19.65 billion in 2026 and is forecast to reach USD 36.26 billion by 2035, reflecting a CAGR of 7.5%. Leading air purifier market companies, including Honeywell, Dyson, Panasonic, are strengthening their presence across key segments such as by technology, by mounting type, by product type, by CADR, by coverage area, by application, by distribution channel and region.
Source: https://www.precedenceresearch.com/air-purifier-market
 Get a Sample
 Table Of Content


What is the Air Purifier Market Size?
The global air purifier market size is accounted at USD 18.34 billion in 2025 and predicted to increase from USD 19.65 billion in 2026 to approximately USD 36.26 billion by 2035, expanding at a CAGR of 7.05% from 2026 to 2035.
Market Highlights
- Asia Pacific dominated the global market with the largest market share of 39% in 2025.
- By technology, HEPA technology segment captured the largest market share in 2025.
- By application, the commercial application segment contributed the biggest market share in 2025.
Overview - Is Air Purification Shifting from a Discretionary Appliance to an Indoor-Air-Quality Essential?
The global air purifier market is estimated at USD 18.3 billion in 2025 and is projected to reach about USD 27.0 billion by 2030, implying an 8.1% CAGR and an incremental revenue opportunity of roughly USD 8.7 billion over the period. Market estimates vary depending on whether commercial, HVAC-integrated, industrial, and specialized purification systems are included; the underlying structural opportunity is nevertheless supported by persistent urban air pollution, rising indoor-air-quality awareness, increasing smart home penetration, and greater consumer willingness to monitor and actively manage indoor environments.
The market is no longer defined solely by standalone HEPA appliances. It is increasingly organized around filtration performance, clean-air delivery rate (CADR), room coverage, particulate sensing, activated-carbon capability, connected controls, energy efficiency, noise performance, filter replacement economics, and recurring consumables. HEPA remains the central filtration platform, while smart air purifiers represent a faster-growing technology layer: the global smart segment is estimated at USD 3.6 billion in 2026 and USD 6.2 billion by 2030, equivalent to a 14.1% CAGR.
Asia Pacific is strategically important because it combines high population density, rapid urbanization, significant pollution exposure, expanding middle-class purchasing power, and strong consumer-electronics ecosystems. At the same time, North America and Europe provide important premiumization opportunities around connected products, whole-home air treatment, allergy management, energy efficiency, and high-performance filtration.
Key Coverage
- 2025 global market size of USD 18.3 billion and 2030 opportunity of USD 27.0 billion
- 8.1% estimated 2025-2030 CAGR
- Portable/stand-alone versus in-duct and whole-home purification
- HEPA, activated carbon, ionic, electrostatic, and other technologies
- Residential, commercial, and specialized applications
- Smart-air-purifier adoption and connected-device economics
- CADR, room coverage, noise, energy consumption and filter-life economics
- Regional and country-level demand, penetration, and competitive structures
Market Size & Forecast - Where Will the Next USD 8.7 Billion of Air-Purification Revenue Come From?
The market's USD 18.3 billion 2025 base provides a substantial installed-product opportunity, but the more strategically critical issue is the composition of incremental growth. At an estimated 8.1% CAGR, the market approaches USD 27 billion by 2030, with growth increasingly linked to premium products, connected functionality, higher CADR, multi-stage filtration and applications beyond traditional residential bedrooms and living rooms.
The market should therefore be evaluated through both unit growth and revenue growth. Entry-level products can expand installed penetration without producing proportionate revenue growth, whereas premium connected units can increase average selling prices through sensors, app integration, higher airflow, multi-stage filtration and automated operating modes.
Smart products illustrate this premium-growth dynamic. The smart-air-purifier market is projected to expand from roughly USD 3.6 billion in 2026 to USD 6.2 billion by 2030, materially faster than the overall market. This indicates that a growing proportion of market value may migrate toward connected, sensor-enabled and software-integrated products.
The full analysis quantifies the market through historical revenue, 2025-2030 forecasts, unit shipments, ASP evolution, regional contribution, technology mix, coverage category, channel, and application.
Key Coverage
- Historical market development
- 2025 base-year revenue
- 2030 market forecast
- 2025-2030 CAGR
- Incremental revenue opportunity
- Unit shipment and ASP analysis
- Base/upside/downside scenarios
- Regional and country-level forecasts
Segmentation Analysis
Why HEPA Remains the Core Platform While Smart Purification Creates the Faster-Growth Pool
HEPA remains the principal technology platform, with public market estimates placing its global share in the 40-46% range, depending on market definition and inclusion of commercial/industrial equipment. One market estimate places HEPA at 45.8% of 2024 revenue, while another estimates 39.5%.
This dominance reflects a strong combination of consumer familiarity, measurable particulate-removal performance, and compatibility with multi-stage systems. HEPA is increasingly paired with activated carbon, pre-filters, and real-time particulate sensors rather than being sold as a standalone technology. Mechanical HEPA filters are theoretically capable of removing at least 99.97% of particles at 0.3 microns under the relevant test definition, reinforcing their importance in performance-oriented positioning.
The report segments the market by:
- Technology: HEPA, activated carbon, ionic, electrostatic, UV/photocatalytic and hybrid systems
- Product type: portable/stand-alone, whole-home, in-duct, and specialized systems
- Connectivity: conventional versus smart/connected
- CADR/coverage: compact-room, medium-room, large-room, and whole-space products
- Application: residential, offices, hospitality, healthcare, education, retail, and other commercial environments
- Channel: online/e-commerce, specialty retail, mass retail, HVAC channels and direct sales
- Geography: North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
The segmentation analysis identifies the largest revenue pools, fastest-growing categories, premium-priced niches, emerging technologies, and areas where penetration remains structurally low.
Market Dynamics - Pollution Exposure Creates Demand, but Product Economics Determine Conversion
Air-pollution exposure remains the fundamental demand catalyst. The 2025 global air-quality dataset covered 9,446 cities across 143 countries, regions, and territories, illustrating the scale and geographic dispersion of particulate pollution.
However, pollution alone does not automatically translate into purifier purchases. Conversion depends on consumer awareness, household income, housing characteristics, product affordability, perceived effectiveness, replacement-filter costs and the severity and duration of pollution episodes.
The principal growth drivers include:
- Persistent PM2.5 and indoor-air-quality concerns
- Urbanization and higher-density housing
- Rising consumer health and wellness expenditure
- Increasing awareness of indoor pollutants
- Smart-home ecosystem expansion
- Growth of e-commerce
- Greater availability of affordable HEPA products
- Commercial demand from offices, schools, healthcare, and hospitality
- Recurring demand for replacement filters
Key restraints include low utilization in some households, filter replacement costs, noise concerns, electricity consumption, weak consumer understanding of CADR and filtration performance, and competition from HVAC filtration and ventilation solutions.
A particularly important structural issue is performance transparency. Consumers can compare price easily, but filtration performance is more difficult to evaluate. CADR therefore becomes a critical commercial metric because it links airflow and particle-removal capability with room size.
Pricing Analysis - The Market is Fragmenting into Value, Performance and Connected Premium Tiers
Air-purifier pricing is increasingly determined by a combination of CADR, coverage area, filter configuration, sensor sophistication, connectivity, noise performance and brand positioning, rather than by filtration technology alone.
The report benchmarks:
- Entry, mid-market, and premium ASP bands
- ASP by CADR category
- ASP by room coverage
- HEPA versus multi-stage systems
- Connected versus non-connected products
- Replacement-filter prices
- Annualized filter cost
- Electricity cost per year
- Distribution margins
- Promotional discounting
- Online versus offline pricing
- Regional price differences
The economic model is particularly important because an inexpensive purifier with frequent filter replacement can have a higher five-year ownership cost than a more expensive product with longer filter life. Consequently, total cost of ownership becomes an increasingly important competitive variable alongside upfront ASP.
Demand-Supply & Value Chain - Filter Economics and Electronics Integration Are Becoming Core Profit Pools
The market operates through a relatively broad consumer-appliance value chain:
Filter media and materials → motors/fans → sensors/electronics → product assembly → brand/OEM integration → distributors/e-commerce → consumers and commercial customers → replacement filters/service.
Unlike commodity appliances, air purifiers have a meaningful recurring-revenue component because filters require replacement. Filter replacement intervals vary by usage, pollution exposure, filter design and operating conditions. EPA guidance specifically notes that overloaded or dirty filters can lose effectiveness, reinforcing the importance of replacement economics.
The report quantifies:
- Component cost structure
- Filter-material economics
- Electronics and sensor contribution
- Manufacturing cost
- Logistics
- Channel margins
- ASP-to-cost relationships
- Replacement-filter revenue
- Installed-base economics
- Recurring revenue potential
- Supply-chain concentration
- Regional manufacturing dependence
The analysis also evaluates localization and sourcing exposure across motors, sensors, plastics, filter media and electronics.
Technology & Innovation - Which Technology Shifts Are Turning Air Purifiers from Passive Filtration Devices into Intelligent Indoor-Air Management Systems?
The air-purifier technology landscape is moving beyond conventional particle removal toward continuous sensing, automated response, and connected air-quality management. Smart air-purifier demand is projected to expand at a 14.1% CAGR through 2030, indicating that connectivity and automation are becoming commercially meaningful differentiators rather than peripheral features. At the product level, this transition is reflected in the integration of particulate and VOC sensors, automatic fan-speed adjustment, real-time air-quality dashboards, scheduling, remote control, mobile applications, and voice or smart-home connectivity alongside established HEPA, activated-carbon, and hybrid filtration architectures.
Our analysis indicates that the key technology battleground is shifting from filtration efficiency alone toward the intelligence layer surrounding filtration. Sensors and automated operating modes can enable products to adjust performance according to detected air conditions, while filter-life monitoring, energy optimization, and noise reduction address operating-cost and user-experience considerations. Our assessment is that technologies demonstrating a measurable link between sensing, automated response, energy consumption, and sustained filtration performance are more commercially significant than features positioned primarily as connectivity upgrades or marketing differentiators. Emerging purification technologies therefore need to be assessed not only by technical novelty, but also by demonstrated adoption, performance evidence, cost implications, and scalability.
In our view, this creates a strategic opportunity for manufacturers to differentiate through integrated air-quality platforms rather than treating the purifier as a standalone appliance. The competitive implications extend across sensor accuracy, filtration architecture, software capabilities, automation, power efficiency, acoustic performance, and recurring filter-management economics. The full report therefore evaluates HEPA and activated-carbon technologies, hybrid filtration, particulate and VOC sensing, automatic modes, IoT and mobile connectivity, voice and smart-home integration, energy optimization, noise reduction, filter-life monitoring, emerging purification technologies, and patent/R&D activity while distinguishing commercially adopted technologies from those whose differentiation remains primarily claim-driven.
The same intelligence can be structured into a technology benchmarking dataset covering purifier technology, filtration architecture, sensing capabilities, automation features, connectivity, energy and noise characteristics, purification approach, application, geography, commercialization status, and relevant patent/R&D indicators. Such a dataset would enable filtering and benchmarking by technology type, product configuration, application, and commercialization maturity, complementing the strategic report with a granular view of where technology investment and product differentiation are concentrated.
The report evaluates:
- HEPA architecture
- Activated-carbon performance
- Hybrid filtration
- Particle sensors
- VOC sensing
- Automatic operating modes
- IoT connectivity
- Mobile applications
- Voice and smart-home integration
- Energy optimization
- Noise reduction
- Filter-life monitoring
- Emerging purification technologies
- Patent and R&D activity
The analysis distinguishes technologies with demonstrated commercial adoption from technologies that remain primarily differentiated through marketing claims.
Regulation, Safety & Sustainability - Performance Claims and Ozone Risk Are Becoming Competitive Differentiators
Regulatory and technical standards increasingly influence product positioning. Performance transparency, energy efficiency, emissions and safety are becoming more important as consumers become more sophisticated.
A critical technical distinction is that CADR primarily measures particle-removal delivery, while gaseous-pollutant performance requires different filtration considerations, particularly adequate activated-carbon media.
Ozone generation is another critical issue. Certain purification technologies, including some ionization, electrostatic and plasma approaches, may raise ozone-emission concerns if inadequately designed.
The report therefore evaluates:
- Product safety standards
- Performance-testing requirements
- Energy-efficiency requirements
- Ozone-emission considerations
- Environmental requirements
- Filter disposal
- Plastic and electronic waste
- Recyclability
- Product lifecycle
- Sustainability claims
- Regulatory differences by geography
Competitive Landscape - Global Appliance Scale Is Colliding with Specialist Air-Quality Expertise
Competition is increasingly divided into several strategic groups: global consumer-electronics/appliance companies, specialist air-quality brands, HVAC manufacturers, premium technology-led brands, regional appliance manufacturers and digitally native challengers.
The competitive structure is not determined solely by product sales. Competitive advantage increasingly depends on:
- Brand trust
- Filtration performance
- CADR and coverage
- Sensor accuracy
- Product design
- Noise performance
- Filter availability
- Replacement-filter economics
- Distribution
- Smart-home integration
- Regional manufacturing
- After-sales service
Market estimates indicate meaningful concentration among leading suppliers, but the broader category remains fragmented because regional brands and specialist manufacturers can compete effectively in specific price points and geographies. One market dataset estimates that its three largest manufacturers collectively represent approximately 27% of the market, illustrating both the importance of scale and the remaining opportunity for challengers.
Tentative Leading Company Universe
| No | Company | Headquarters | Market Position | Core Strength |
| 1 | Honeywell | US | Global appliance/IAQ player | HEPA, residential & commercial |
| 2 | Philips / Versuni | Netherlands | Global consumer brand | Residential air treatment |
| 3 | Dyson | UK | Premium technology player | High-performance design & filtration |
| 4 | Daikin | Japan | HVAC/air-quality leader | HVAC integration |
| 5 | Sharp | Japan | Consumer-electronics specialist | Plasmacluster & filtration |
| 6 | Panasonic | Japan | Consumer-electronics/appliance player | Air treatment & electronics |
| 7 | Coway | South Korea | Air-quality specialist | Residential purification |
| 8 | LG Electronics | South Korea | Smart-appliance player | Connected air treatment |
| 9 | Samsung Electronics | South Korea | Smart-home ecosystem player | Connected appliances |
| 10 | Xiaomi | China | Value/smart challenger | Connected affordable products |
| 11 | Midea | China | Appliance-scale competitor | Mass-market air treatment |
| 12 | Blueair | Sweden/US | Premium specialist | HEPA & residential IAQ |
| 13 | IQAir | Switzerland | Premium IAQ specialist | High-performance filtration |
| 14 | Levoit / VeSync | US/China | DTC/e-commerce challenger | Smart residential products |
| 15 | Electrolux | Sweden | Appliance manufacturer | Residential air treatment |
| 16 | Whirlpool | US | Appliance-scale participant | Home air treatment |
| 17 | Carrier | US | HVAC player | Whole home/commercial IAQ |
| 18 | Camfil | Sweden | Filtration specialist | Commercial/industrial filtration |
| 19 | Systemair | Sweden | HVAC/air-quality player | Commercial ventilation |
| 20 | Molekule | US | Technology-focused specialist | Advanced filtration |
| 21 | Alen | US | Premium residential specialist | HEPA residential systems |
| 22 | Winix | South Korea | Residential specialist | HEPA/hybrid purification |
| 23 | Austin Air | US | Filtration specialist | High-performance residential |
| 24 | Airversa / regional smart brands | Asia | Emerging connected challengers | Smart/e-commerce |
| 25 | Regional private-label manufacturers | Asia | Cost-focused challengers | OEM/ODM manufacturing |
This universe is tentative rather than a validated market-share ranking and is designed to capture global leaders, regional participants, technology specialists and emerging challengers.
Market Share & Competitive Benchmarking - Scale Alone Does Not Determine Air-Purifier Leadership
The competitive analysis benchmarks companies using air-purifier-specific KPIs rather than broader corporate size:
- Air-purifier revenue exposure
- Estimated market share
- Product breadth
- HEPA portfolio depth
- CADR range
- Premium ASP exposure
- Smart-product penetration
- Filter portfolio
- Replacement-filter economics
- Geographic presence
- Distribution reach
- E-commerce strength
- Manufacturing footprint
- R&D investment
- Product-launch velocity
- Sustainability positioning
The analysis distinguishes scale leaders, premium specialists, technology specialists, smart-home challengers, regional leaders, and value-oriented competitors, avoiding the assumption that the largest parent company automatically has the strongest air-purifier position.
Product Portfolio Benchmarking - The Competitive Battleground Is Moving From “Has HEPA” to “How Much Clean Air Does the Product Deliver?”
Because HEPA filtration has become widespread, product differentiation increasingly occurs around CADR, room coverage, fan architecture, filter depth, activated-carbon quantity, sensors, noise, and software.
The report benchmarks leading portfolios across:
- Compact-room products
- Medium-room products
- Large-room products
- Whole-home solutions
- Smart products
- Premium products
- Commercial systems
- HEPA-only systems
- HEPA + carbon systems
- Multi-stage filtration
- Replacement-filter portfolios
This reveals portfolio gaps such as low-cost products with limited sensing, premium products with high ASP but weak recurring economics, and commercial systems where higher CADR and filtration capacity create defensible value pools.
Technology & Innovation Benchmarking - Which Technology Capabilities Are Creating the Strongest Differentiation as Air Purifiers Shift from Filtration to Intelligent Air-Quality Management?
Technology benchmarking is increasingly moving beyond conventional filtration performance toward the integration of sensing, automation, connectivity, and software. The shift from passive filtration to active air-quality management is evident in products that combine particulate and air-quality sensing with automatic operating controls, connected platforms, real-time monitoring, and adaptive performance. This creates a technology stack in which the value proposition extends beyond the filter itself to how effectively the product measures indoor conditions and responds to them.
Our analysis indicates that sensor intelligence is becoming a critical differentiator alongside filtration architecture. R&D intensity, patent activity, product launches, sensing capability, connected platforms, automatic controls, and commercialization provide a more meaningful basis for assessing technology maturity than feature counts alone. Our assessment is that technologies capable of linking accurate environmental measurement with automated operating decisions have greater potential to create defensible differentiation than widely replicated connectivity or app-based features. The distinction between genuinely differentiated engineering and feature duplication is therefore becoming increasingly important for competitive benchmarking.
In our view, the most significant implication is that competitive advantage is shifting toward integrated hardware-software capabilities rather than filtration technology in isolation. Manufacturers seeking differentiation will increasingly need to demonstrate how sensing, controls, filtration architecture, connectivity, and user interfaces work together to improve air-quality management and operating efficiency. The full report benchmarks major companies across technology maturity, R&D and patent activity, product innovation, sensing capabilities, automation, connected platforms, filtration architecture, commercialization status, and the extent to which individual capabilities represent substantive differentiation versus industry-standard features.
The same analysis can be structured into a technology benchmarking dataset tracking company, product/model, technology type, sensor capability, filtration architecture, automation features, connectivity, patent/R&D activity, launch timing, commercialization status, and technology-maturity indicators. Users can filter and benchmark technologies by company, product, capability, and commercialization stage, providing a granular dataset that complements the strategic assessment and helps identify areas of technological concentration, differentiation, and potential whitespace.
Geographic Competitive Landscape - Local Pollution Conditions and Distribution Structures Create Different Competitive Rules
North America remains a major commercial market, while Asia Pacific combines strong pollution-driven demand with rapid appliance adoption and manufacturing depth. China and India are particularly important because of their scale, urban concentration and expanding awareness of indoor air quality.
India illustrates the opportunity: HEPA represented approximately 46.4% of India's portable-air-purifier technology revenue in 2024 in one market dataset, demonstrating the significant role of mechanical filtration in a high-pollution emerging market.
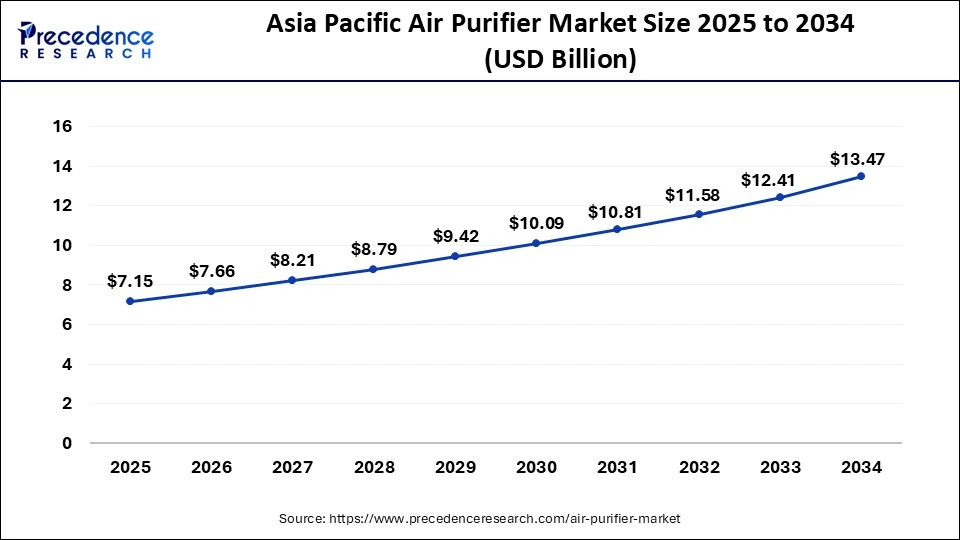
Asia Pacific Air Purifier Market Size and Growth 2026 to 2035
The Asia Pacific air purifier market size accounted for USD 7.15 billion in 2025 and is predicted to be worth around USD 14.37 billion by 2035, rising at a CAGR of 7.23% from 2026 to 2035.
The report compares:
- Regional market size
- Penetration
- Pollution exposure
- ASP
- Local manufacturing
- Distribution
- E-commerce
- Smart-product adoption
- Filter replacement infrastructure
- Competitive intensity
- Import dependence
- Regional product preferences
Manufacturing, Customer & Channel Benchmarking – Distribution and Filter Availability Can Be as Important as the Appliance
Air purifiers are unusually dependent on post-purchase availability because the product requires replacement filters. Consequently, companies with strong distribution can create an installed-base advantage that extends beyond the initial appliance sale.
The report benchmarks:
- Manufacturing locations
- OEM/ODM exposure
- Vertical integration
- Regional production
- E-commerce penetration
- Retail networks
- HVAC channels
- Direct-to-consumer models
- Distributor relationships
- Filter availability
- After-sales service
- Customer support
- Subscription/replenishment opportunities
For commercial customers, procurement additionally depends on airflow requirements, room size, maintenance, compliance, noise, and total cost of ownership.
Strategic Developments & M&A - The Market Is Converging With HVAC, Smart Homes, and Broader Indoor-Air-Quality Platforms
Strategic activity is increasingly centered on:
- Smart-home integration
- HVAC-air-treatment convergence
- Sensor technology
- Premium filtration
- Geographic expansion
- E-commerce distribution
- Connected appliances
- Replacement-filter ecosystems
- Commercial indoor-air-quality solutions
The report tracks the latest two to three years of product launches, partnerships, acquisitions, technology agreements, manufacturing investments and geographic expansion to identify where companies are directing capital.
M&A analysis evaluates transactions by buyer, target, transaction value, technology, geography, customer segment and strategic rationale, with particular attention to consolidation across filtration, HVAC, sensors, and connected-home technologies.
Company Profiles - 20-25 Market Participants Tracked Through a Consistent Competitive Lens
Each leading company profile covers:
- Headquarters and ownership
- Revenue and relevant business exposure
- Air-purifier portfolio
- Technology platforms
- HEPA and carbon offerings
- Smart-product exposure
- Geographic footprint
- Manufacturing
- Distribution
- R&D
- Product launches
- Partnerships
- M&A
- Customer segments
- Competitive strengths
- Vulnerabilities
- Growth opportunities
This creates a consistent company-level dataset rather than isolated corporate profiles.
Opportunity & White-Space Analysis - Where Can New Value Be Created Beyond Conventional Residential HEPA Units?
The analysis identifies opportunities across:
- Affordable HEPA products in emerging markets
- Premium high-CADR systems
- Smart air-quality monitoring
- Whole-home purification
- Commercial indoor-air-quality systems
- Hospitality and healthcare
- Filter-subscription models
- Low-noise products
- Energy-efficient purification
- VOC-focused systems
- High-pollution geographies
- E-commerce-first brands
- Integrated HVAC/purification solutions
The most important white-space opportunities arise where high pollution exposure intersects with low purifier penetration, inadequate distribution, or weak filter-replacement infrastructure.
Industry Structure - Competition Is High, but Entry Barriers Increase with Brand, Distribution, and Installed Base
Supplier Power - Medium
- Core components and filter media are available from multiple suppliers, although specialized filtration materials, sensors and high-quality motors can create sourcing advantages.
Buyer Power - Medium to High
- Consumers can compare products online easily, increasing price transparency. Commercial buyers have greater bargaining power because purchases can involve multiple units and maintenance contracts.
Threat of New Entrants - Medium
- OEM/ODM manufacturing lowers hardware-entry barriers, but establishing brand trust, distribution, certification, after-sales support, and replacement-filter availability remains more difficult.
Threat of Substitutes - Medium
- HVAC filtration, ventilation, source control and building-level air-treatment systems can substitute for portable purification in certain applications. Air cleaners also cannot replace source control and ventilation.
Competitive Rivalry - High
- Competition is intensified by global appliance manufacturers, specialist brands, regional manufacturers, private labels, and digitally native companies competing across overlapping price tiers.
Market Attractiveness - Growth Depends on Penetration, Premiumization and Recurring Filter Economics
The market offers multiple growth mechanisms rather than reliance on one demand driver:
- New household penetration
- Replacement purchases
- Premiumization
- Smart-device adoption
- Commercial deployment
- Geographic expansion
- Filter replacement
- Whole-home integration
The most commercially significant opportunity pools are therefore those combining high pollution exposure, increasing disposable income, low installed penetration and strong e-commerce or distribution infrastructure.
Future Outlook - Air Purifiers Are Evolving into Connected Indoor-Air-Quality Platforms
Through 2030, the market is expected to move toward:
- Greater HEPA penetration
- Faster smart-product adoption
- More sophisticated particulate and VOC sensing
- Higher CADR per dollar
- Lower noise
- Improved energy efficiency
- Greater filter-life optimization
- Integration with HVAC systems
- Expansion into commercial indoor-air-quality management
- Greater recurring revenue from replacement filters and services
The central strategic question will increasingly shift from “Does the product have a HEPA filter?” to “How effectively, quietly, intelligently and economically can the system maintain clean indoor air?”
The full outlook provides 2030 and longer-term scenarios covering market size, technology adoption, regional growth, pricing, competitive structure, capacity, recurring filter economics, M&A, and emerging profit pools.
Recent Development
- In July 2025, an Omani startup developed an innovative and environmentally sustainable air purification device that uses natural components such as natural algae to improve air quality, particularly in enclosed spaces like vehicles. The device was developed by a team of students and researchers aiming to provide a smart, effective, and locally adaptable solution to air pollution and heat-related hazards.
- In July 2025, Equator Advanced Appliances unveiled the APSH 430 W Air Purifier + Humidifier, a compact dual-function system designed to improve indoor air quality in homes with pets, allergens, and everyday environmental irritants. Combining HEPA filtration, UV-C sterilization, and negative ion generation, this 2-in-1 model offers broad-spectrum purification and moisture enhancement for spaces up to 431 square feet.
- In July 2025, Blueair, the global leader in air wellness, announced a strategic partnership with The Class, the transformative movement and mindfulness practice. As the official air wellness partner for The Class's flagship studio, Blueair will provide clean, fresh air to every class.
- In October 2024, Philips, under Versuni India, introduced a new range of air purifiers designed to offer both silent and powerful air purification. The new models, including the 3200, 4200 Pro, and 900 Mini, are built to deliver cleaner air while maintaining a quiet, undisturbed environment. These "Silent Protectors" come with advanced features aimed at improving indoor air quality and are now available in India.
- In April 2025, as global demand for indoor air safety reaches new heights in the post-pandemic era, COTELL trusted name in hospitality technology with over 21 years of industry experience, officially unveiled the COTELL+ Air Purifier series. Leveraging proprietary AOP-KF Registered technology, the new product line delivers a comprehensive and intelligent air purification solution tailored for hospitality, healthcare, education, offices, and residential environments.
- In November 2024, the Hero Group-owned smart devices maker Qubo launched two new models of smart air purifiers, the Q600 and Q1000, for larger living spaces. These air purifiers can be monitored and controlled via Qubo app, and through voice controls like Alexa and Google Assistant.
- In November 2024, Dyson launched a new air purifier, the Dyson Purifier Hot plus Cool Gen 1, in India. The announcement comes amid growing air pollution, with Delhi, Noida, Ghaziabad, and other parts of the National Capital Region (NCR) reporting low visibility from smog and “very poor” AQI levels. The highlight of this air purifier is that it is a relatively affordable option in Dyson's line-up, boasting room heating and cooling technology.
Air Purifier Market Segments Covered in the Report
By Technology
- Activated Carbon
- High Efficiency Particulate Air
- Ionic Filters
- Others
By Mounting Type
- Fixed
- Portable
By Product Type
- Upper Air
- In-duct
- Self Contained/Standalone
- Others (Coil & Drain Pans, etc.)
By CADR
- Smoke
- Dust
- Pollen
By Coverage Area
- Below 250 Sq. Ft.
- 250-400 Sq. Ft.
- 401-700 Sq. Ft.
- Above 700 Sq. Ft.
By Application
- Residential
- Commercial
- Industrial
By Distribution Channel
- Online
- Company Owned Websites
- e-Commerce Websites
- Offline
- Hypermarkets/
- Supermarkets
- Specialty Stores
- Others (Retail Stores, etc.)
By Region
- North America
- Latin America
- Europe
- Asia-pacific
- Middle and East Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting