
Blockchain Technology Market Size, Key Companies, Company Market Share, User Adoption, Technology Deployment, Revenue Growth, Competitive Positioning, and Demand Forecast
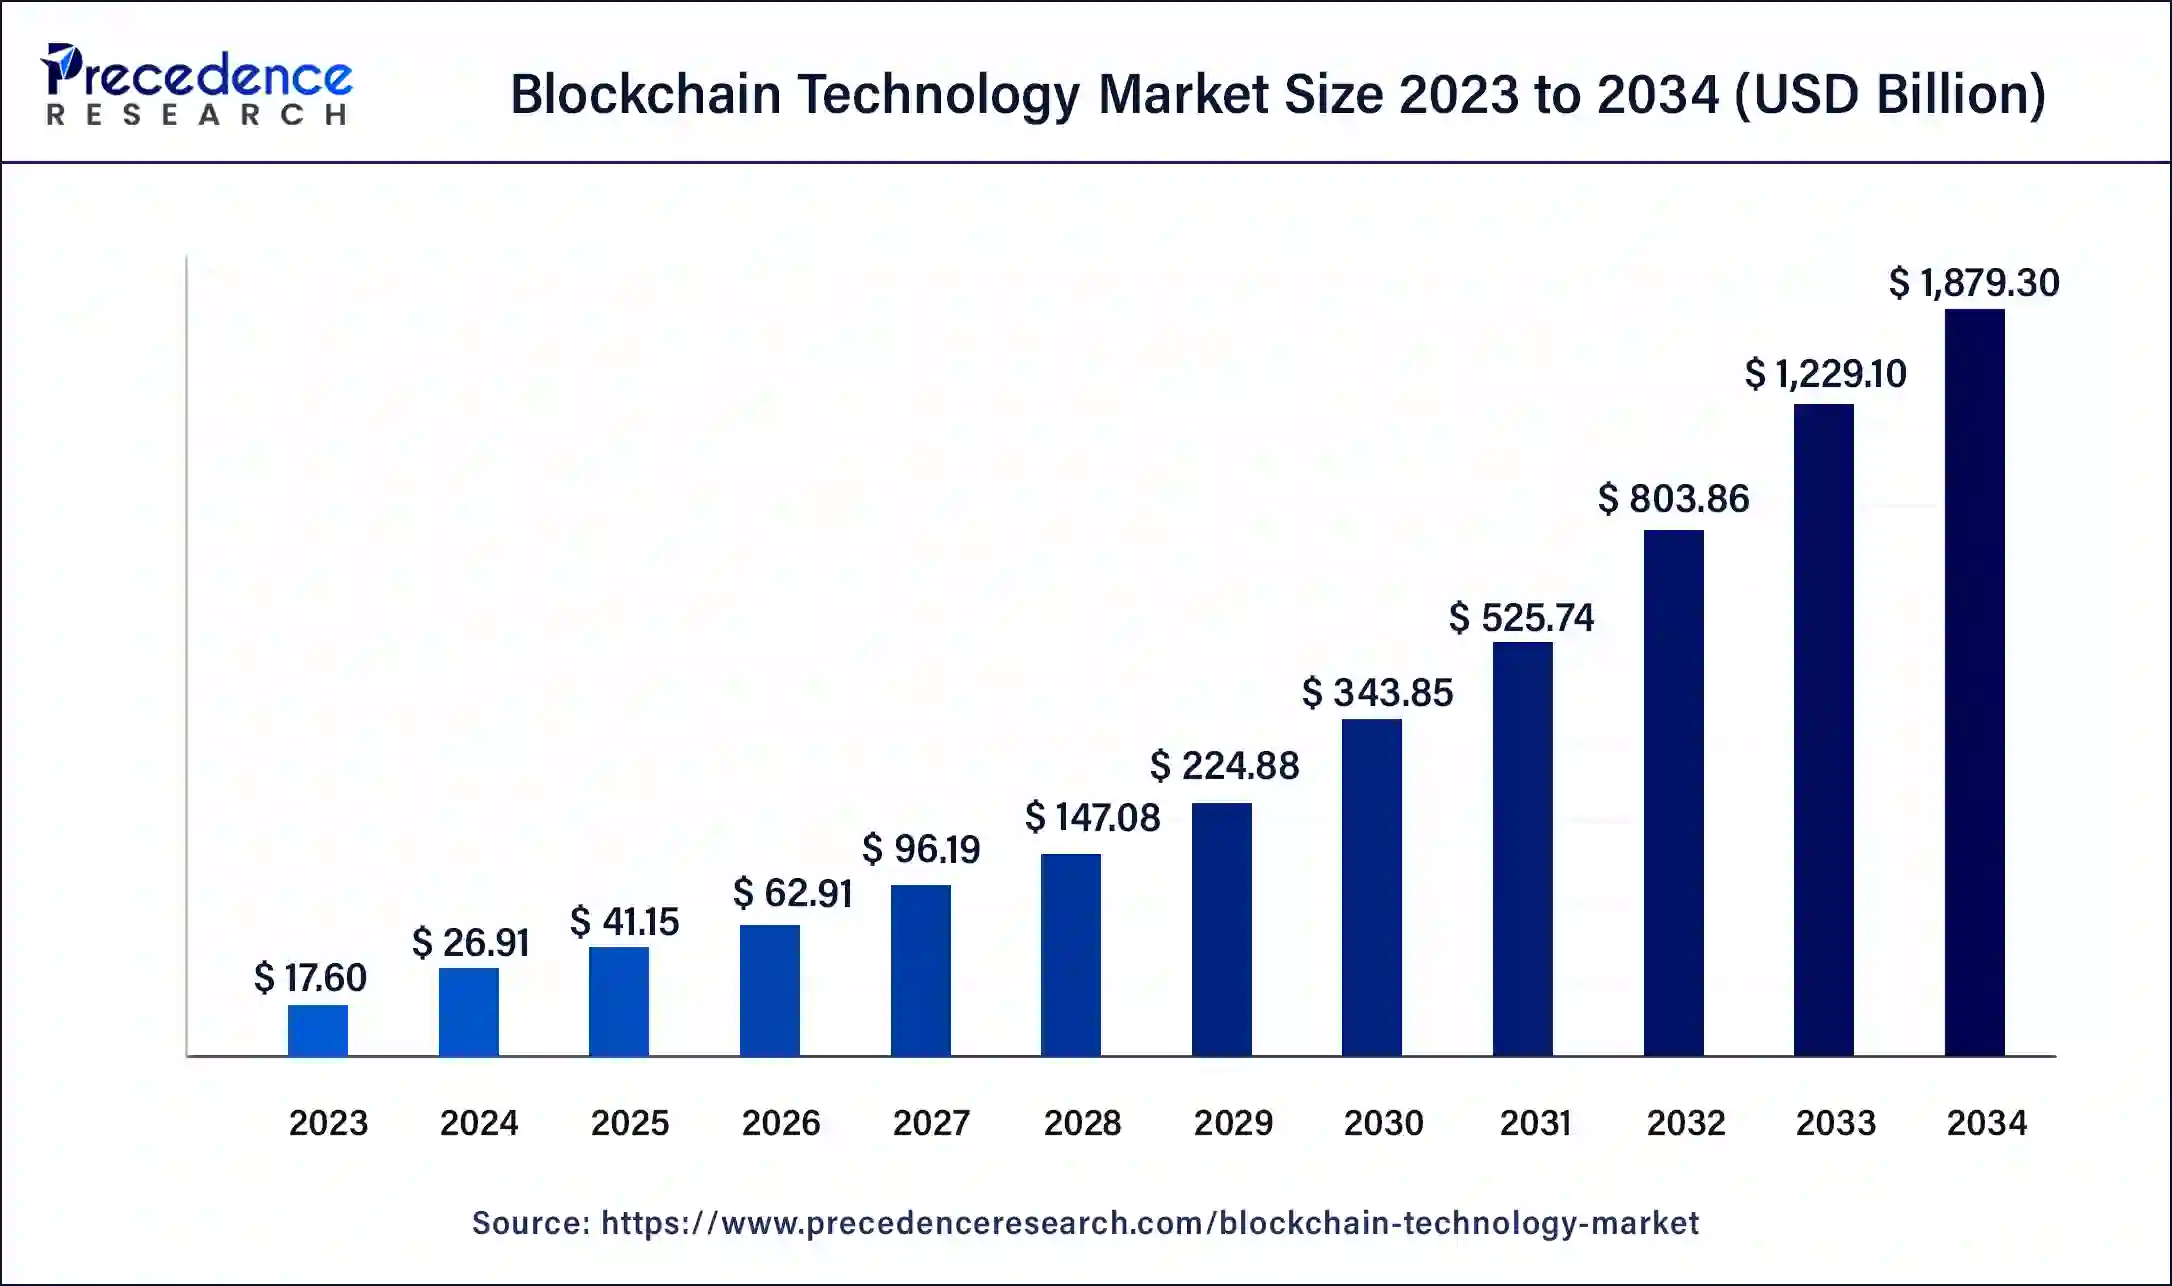
Blockchain is growing well beyond cryptocurrency, into stablecoins, tokenized assets, institutional settlement, decentralized applications, and enterprise infrastructure. The market is estimated at USD 62.91 billion in 2026 and should reach USD 2,379.53 billion by 2035, a 50.04% CAGR. Growth comes from institutional adoption, rising stablecoin activity, tokenization of real-world assets, layer-2 scaling, interoperability, and demand for programmable settlement. Tokenized real-world assets passed USD 19 billion by early 2026, a sign that commercialization is picking up speed. The report covers market size, technology architecture, applications, competitive positioning, pricing, investment, and new blockchain opportunities.
Source: https://www.precedenceresearch.com/blockchain-technology-market
 Get a Sample
 Table Of Content


What is the Blockchain Technology Market Size?
The global blockchain technology market size is predicted to increase from USD 62.91 billion in 2026 to approximately USD 2,379.53 billion by 2035, expanding at a CAGR of 50.04% from 2026 to 2035.
Key Takeaways
- Blockchain is growing beyond cryptocurrency into stablecoins, tokenization, institutional settlement, decentralized applications, and enterprise infrastructure.
- Financial services remain the most mature application area, covering payments, custody, tokenization, securities settlement, and digital-asset infrastructure.
- Layer-2 scaling, zero-knowledge technologies, interoperability, account abstraction, and modular designs are easing scalability, privacy, and cost limits.
- More than USD 20 billion went into crypto and blockchain startups in 2025, a sign of continued commitment to infrastructure.
- Institutional adoption depends on security, compliance, interoperability, integration, transaction economics, governance, and reliable infrastructure.
- North America is a major investment and institutional hub, while Asia Pacific shows strong adoption and growth potential.
- Competition is shifting toward developer ecosystems, institutional distribution, compliance, interoperability, security, and recurring infrastructure revenue.
- Pricing combines transaction fees, API usage, enterprise licensing, custody fees, infrastructure services, subscriptions, and tokenization revenue.
- The market is fragmented across protocols, exchanges, infrastructure providers, custodians, analytics firms, tokenization specialists, and enterprise platforms.
- Stablecoins, tokenized securities, institutional custody, programmable settlement, interoperability, and analytics are emerging profit pools.
- Future leaders will stand out through ecosystem depth, institutional relationships, regulatory readiness, scalability, interoperability, and recurring revenue.
Overview
Blockchain is Growing Beyond Crypto into Digital Trust Infrastructure
The blockchain technology market is entering a new phase. Value is being created beyond foundational cryptography infrastructure and is now being invested in stablecoin settlement, tokenized real-world assets, institutional digital assets, decentralized applications, identity, supply-chain tokenization, and enterprise data infrastructure. Market estimates are inherently volatile, with varying definitions that include crypto-economic services and only blockchain infrastructure and enterprise software.
Financial services continue to represent the largest economic opportunity, but tokenization, infrastructure-as-a-service solutions, institutional custodianship, interoperability, smart-contract auditing, and enterprise data services are also significant factors. The Asia-Pacific region remains a critical adoption driver, while North America is a region of capital formation, institutional infrastructure, and enterprise commercialization.
Key Coverage
- Blockchain infrastructure, middleware, platforms and services
- Stablecoins and tokenized assets
- Public, private, consortium, and hybrid blockchain architectures
- Financial services, supply chain, identity, and enterprise applications
- Regional adoption and investment intensity
- Enterprise versus consumer blockchain economics
- Emerging blockchain infrastructure profit pools
How Big is Blockchain Technology Once Crypto Prices are Removed?
That spread points to a key analytical issue, since blockchain technology revenue has to be kept apart from cryptocurrency market capitalization, transaction value, and the economic value of assets that are merely recorded on-chain.
The full analysis builds the market bottom-up from blockchain platforms, node and infrastructure services, smart-contract and development platforms, enterprise solutions, custody and wallet infrastructure, analytics, interoperability, tokenization infrastructure, and professional services. Technology revenue is kept separate from transaction volumes and asset values, so swings in crypto prices do not distort the underlying opportunity.
Key Coverage
- Historical market development
- Revenue by infrastructure, middleware, platform, and services
- Enterprise versus consumer monetization
- Blockchain transaction and settlement volumes
- Regional contribution
- Base/upside/downside scenarios
- Incremental revenue opportunity
Segmentation Analysis
Financial Infrastructure Leads While Tokenization Drives New Growth
The market is segmented by blockchain type, technology layer, application, end user, deployment model, customer size, and geography. Public blockchains remain central to transaction and application ecosystems, while private and permissioned networks stay relevant where enterprises need controlled access, governance, and compliance.
By application, payments and settlement, digital assets, decentralized finance, and financial-market infrastructure are the biggest commercial opportunities. Tokenization is a particularly strong growth path. Tokenized real-world assets passed USD 19 billion by the end of Q1 2026, more than tripling since the start of 2026, and tokenized Treasuries alone made up about 67% of that total. (CoinGecko)
The report sizes each segment by revenue, adoption, transaction activity, deployment, customer penetration, and growth contribution. It also separates high-volume, low-monetization applications from smaller but higher-value enterprise infrastructure categories.
Key Coverage
- Public/private/hybrid blockchain
- Infrastructure, middleware, and application layers
- Stablecoins and payments
- Tokenization and digital securities
- DeFi and smart-contract applications
- Enterprise blockchain
- Identity and supply-chain applications
- Regional and customer segmentation
Market Dynamics
What is Driving Demand for Blockchain Beyond Crypto Trading?
The key driver is the shift from blockchain as a cryptocurrency ledger to blockchain as programmable financial and digital infrastructure. Stablecoin transaction activity topped USD 4 trillion in the first eight months of 2025, about 83% higher than the same period a year earlier. (TRM Labs)
Tokenization is the second big aspect. Tokenized real-world assets grew from about USD 5.4 billion at the start of 2025 to USD 19.3 billion by March 2026, a rise of roughly 257%. (CoinGecko) Against that, regulatory fragmentation, cybersecurity incidents, limited interoperability, transaction costs, scalability, and unclear enterprise ROI still hold adoption back.
The next stage will go beyond proving the technology's viability and work to reduce frictions in adoption, encourage regulatory clarity, and demonstrate value over existing databases and payment settlement infrastructures.
Pricing Analysis
Blockchain Revenue is Shifting from Transaction Fees to Recurring Contracts
Blockchain pricing models are fundamentally different from those in traditional software due to the revenue sources from transaction fees, API, nodes, custody, software subscriptions, wallets, enterprise licensing, development services, and asset-servicing fees.
Public-chain economics are driven to a large degree by network utility and gas fees. Enterprise infrastructure is increasingly sold through recurring software contracts, usage-based pricing, and infrastructure-as-a-service. Institutional customers are willing to pay a premium for compliance, security, uptime, governance, and integration, and not just the lowest total transaction cost.
This report contains pricing benchmarks of infrastructure, RPC/ API access, custody, tokenization platforms, enterprise software, analytics, and developer tooling. The study assesses transaction cost, cost per API call, custody fees, subscription economics, infrastructure margins, and enterprise contract structures.
Key Coverage
- Transaction-fee economics
- API/RPC pricing
- Enterprise licensing
- Custody economics
- Infrastructure-as-a-service
- Tokenization fees
- Developer-tool monetization
- Gross-margin implications
Demand-Supply Analysis
Can Developer Infrastructure Keep Up with Institutional Demand?
Demand is growing faster in several specialized infrastructure categories than in traditional enterprise blockchain projects. More than USD 20 billion of venture capital went into crypto and blockchain startups in 2026, and Q4 alone drew about USD 8.5 billion across 425 deals. (Galaxy)
Supply is still scattered across protocol infrastructure, node providers, custodians, analytics firms, development platforms, security providers, and tokenization specialists. The report assesses capacity through developer activity, node coverage, transaction-processing capability, supported chains, API capacity, institutional assets serviced, custody balances, cloud infrastructure, and capital deployed.
Value Chain & Supply Chain
Value is Moving Toward Infrastructure, Security, and Institutional Distribution
The blockchain value chain starts with hardware, cloud infrastructure, and validator services. It then runs through protocols, developer infrastructure, wallets and custody, applications, and exchanges or financial institutions, before reaching end users.
The biggest value pools are moving toward infrastructure that reduces complexity between blockchain networks and conventional financial or enterprise systems. Security, custody, compliance analytics, interoperability, and institutional connectivity therefore matter more than raw blockchain deployment.
The full report maps revenue and margin pools across each layer, identifies technology dependencies, analyzes switching costs, and assesses where vertical integration makes economic sense.
Technology & Innovation
Which Blockchain Technologies Will Solve Scale, Interoperability, and Institutional Adoption?
Blockchain architecture is moving from single, monolithic networks toward modular, multi-chain infrastructure. Layer-2 scaling, zero-knowledge technologies, interoperability protocols, account abstraction, and specialized execution environments are tackling the throughput, latency, and cost limits that have held back large-scale adoption. At the application level, tokenization is creating measurable new demand. By Q1 2026, tokenized commodities had reached about USD 5.5 billion and tokenized stocks about USD 0.5 billion. These technologies matter for more than speed. They are becoming the plumbing that connects on-chain assets with regulated financial markets and institutional settlement systems.
Interoperability and scalability are the main technology battlegrounds since adoption is spreading across many networks and not resting on a single chain.
Layer-2 designs can lower transaction costs and add capacity, while zero-knowledge technologies can improve scale and privacy without pushing all transaction data through the base layer. Tokenization also raises demand for infrastructure that links Treasuries, securities, deposits, and commodities to programmable blockchain environments. The most valuable technologies will probably be the ones that cut friction between blockchains and traditional finance, not the ones that merely raise theoretical throughput.
In practice, blockchain competition is moving from protocol features toward infrastructure that can actually be deployed. Providers that offer high throughput, low execution cost, cross-chain interoperability, institutional-grade security, privacy, compliance tools, and easy developer access are best placed to win enterprise and financial-market workloads. The full report evaluates throughput, latency, gas economics, interoperability, developer adoption, smart-contract functionality, security, privacy, deployment maturity, and commercialization, to show which technologies have moved from technical innovation to scalable use.
The same data is available as a technology intelligence database covering technology, architecture, scalability mechanism, supported networks, throughput, latency, transaction cost, interoperability, privacy, developer ecosystem, deployment status, application, geography, and commercialization stage. Users can filter and compare mature, emerging, and experimental architectures and see where differentiation is developing fastest.
Regulatory & Sustainability Analysis
Regulation is Moving from Uncertainty to Market Structure
Regulation is becoming a factor of adoption enabler and not only a restraint. Stablecoin, digital-asset licensing, custody, tokenized securities rules, and anti-money laundering prerequisites dictate what blockchain-based applications have the right to institutional adoption.
Clear standards create room for compliant infrastructure providers and raise the bar for unregulated ones. The report outlines requirements across jurisdictions and applications and measures the impact on licensing costs, compliance infrastructural outlays, institutional onboarding, transaction surveillance, and market access.
Customer & Application Analysis
Financial Institutions Moving from Blockchain Pilots to Real Deployment?
Financial services are the most commercially mature customer group, covering payments, securities settlement, collateral management, custody, tokenized deposits, and digital assets. Enterprise demand also reaches supply-chain traceability, digital identity, documentation, and automated contract workflows.
Qualification requirements are high, and switching costs are high. Institutional buyers evaluate potential blockchain solutions by their security, regulatory compliance, interoperability, ease of integration, transaction economic efficiency, uptime, governance, and counterparty risks while being relatively indifferent to innovation.
Competitive Landscape
What Will Decide Leadership as Blockchain Infrastructure Scales?
The blockchain competitive landscape is fragmented across protocols, exchanges, institutional infrastructure, custody, developer tooling, analytics, tokenization, stablecoins, and enterprise platforms. No single company controls the full stack. The 23-company universe in this report spans trading and custody, blockchain APis, interoperability, settlement, tokenization, compliance, and network infrastructure. Competitive advantage is moving away from individual blockchain features and toward ecosystem depth, institutional trust, regulatory readiness, interoperability, developer adoption, and infrastructure scale.
Scale and institutional connectivity matter more as blockchain moves beyond crypto-native activity into payments, tokenized assets, programmable settlement, and enterprise use. Specialists now operate across custody, stablecoins, middleware, scaling, analytics, and institutional settlement, so leadership is likely to stay spread across several layers. Companies that can connect multiple layers of the value chain while keeping security, compliance, interoperability, and reliable performance are better placed to win higher-value institutional demand.
For that reason, the assessment looks at capabilities more than company size. It compares institutional customer reach, supported networks, custody and settlement, developer ecosystem, API coverage, interoperability, tokenization, stablecoin exposure, compliance, geographic presence, partnerships, investment activity, and product breadth. Competition will intensify around institutional custody, tokenized real-world assets, stablecoin infrastructure, cross-border settlement, interoperability, and enterprise-grade infrastructure.
The full report adds company-level benchmarking, product and technology comparisons, geographic capabilities, institutional customer coverage, strategic developments, partnerships, investment, and M&A. It also points out capability gaps and white spaces across infrastructure, tokenization, settlement, compliance, interoperability, and developer services.
The competitive intelligence can also be structured into a company benchmarking database covering company, headquarters, market position, core strength, product category, supported networks, technology layer, application focus, institutional capabilities, custody, tokenization, stablecoin capabilities, interoperability, geographic coverage, partnerships, strategic developments, M&A, and year. Users can filter by company, capability, layer, application, geography, and position for side-by-side comparison.
Tentative Leading Company Universe
| Company | Headquarters | Market Position | Core Strength |
| Coinbase | U.S. | Institutional/digital-asset infrastructure | Trading, custody, infrastructure |
| Binance | Global | Digital-asset ecosystem | Exchange and blockchain ecosystem |
| Ripple | U.S. | Payments/blockchain infrastructure | Cross-border settlement |
| Circle | U.S. | Stablecoin infrastructure | Digital-dollar infrastructure |
| Consensys | U.S. | Ethereum infrastructure | Wallets and developer tooling |
| Chainlink Labs | U.S. | Blockchain middleware | Oracles/interoperability |
| Fireblocks | U.S. | Institutional infrastructure | Custody and asset transfer |
| Chainalysis | U.S. | Blockchain intelligence | Compliance and analytics |
| Alchemy | U.S. | Developer infrastructure | Blockchain APIs |
| Blockdaemon | U.S. | Institutional infrastructure | Nodes/staking |
| Kraken | U.S. | Digital-asset infrastructure | Trading/custody |
| Paxos | U.S. | Regulated digital assets | Stablecoins/tokenization |
| R3 | U.K. | Enterprise blockchain | Institutional distributed ledger |
| Digital Asset | U.S. | Institutional blockchain | Tokenization/settlement |
| Ava Labs | U.S. | Blockchain platform | Avalanche ecosystem |
| Polygon Labs | Global | Scaling infrastructure | Ethereum scaling |
| Stellar Development Foundation | U.S. | Payments infrastructure | Cross-border/tokenization |
| Hedera | U.S. | Enterprise-oriented network | Distributed ledger |
| BitGo | U.S. | Institutional custody | Custody and settlement |
| Copper | U.K. | Institutional digital assets | Custody/prime infrastructure |
| Anchorage Digital | U.S. | Institutional custody | Regulated custody |
| Blockstream | Canada | Bitcoin infrastructure | Infrastructure/tokenization |
| Galaxy Digital | U.S. | Digital-asset financial services | Trading, investment, infrastructure |
Market Share & Competitive Ranking
Revenue Pools Stay Fragmented Across Blockchain Layers
Concentration varies a lot by segment. Digital-asset exchanges and stablecoins are far more concentrated than developer tooling, enterprise blockchain, analytics, and interoperability.
Coinbase gives a sense of the scale of adjacent infrastructure. It generated USD 6.9 billion of net revenue in 2025, made up of USD 4.1 billion in transaction revenue and USD 2.8 billion in subscription and services revenue. (SEC) The rise of subscription and services income points to a wider move from transaction-dependent economics toward recurring infrastructure revenue.
The full report estimates market share by blockchain technology layer and does not apply exchange revenue to the whole technology market.
Competitive Benchmarking
Ecosystem Depth Now Matters as Much as Revenue Scale
Leading participants are compared on revenue exposure, blockchain coverage, institutional customers, developer ecosystem, supported networks, technology, geographic reach, custody, security, R&D, partnerships, and strategic activity.
The analysis separates market leaders, infrastructure specialists, technology leaders, institutional specialists, application-focused players, and emerging challengers, and does not treat every blockchain company as a direct competitor.
Product Portfolio Benchmarking
Broad Platforms or Specialists Hold the Advantage?
The market spans wallets, custody, APis, node infrastructure, exchanges, tokenization platforms, analytics, smart-contract development, stablecoin infrastructure, and enterprise distributed-ledger solutions.
Broad platforms gain from cross-selling across their ecosystem, while specialists stand out through compliance, security, institutional connectivity, or highly tuned infrastructure. The report points out portfolio overlaps, capability gaps, and expansion opportunities across the main technology layers.
Technology & Innovation Benchmarking
Interoperability, Security, and Developers Define Technology Leadership
Technology benchmarking looks at supported protocols, transaction performance, interoperability, smart-contract environments, developer tools, security architecture, patents where relevant, R&D intensity, and commercial deployments.
Special attention goes to zero-knowledge technologies, layer-2 scaling, cross-chain interoperability, tokenization infrastructure, programmable payments, and institutional blockchain architectures.
Application Competitive Benchmarking
Payments and Capital Markets are the Key Institutional Battlegrounds
Positioning is mapped across payments, trading, custody, tokenization, securities settlement, supply chain, identity, compliance, decentralized finance, and enterprise applications.
The analysis flags application specialists, diversified platforms, and areas where customer demand is foreseen to grow faster than providers can supply it.
Geographic Competitive Landscape
North American Capital Meets Asia's High-Volume Adoption
North America is still a key center for blockchain venture investment and institutional infrastructure, while Asia Pacific pairs strong user adoption with growing digital-asset and payment applications. South Asia showed especially strong crypto adoption momentum in 2025. (TRM Labs)
The report benchmarks companies by headquarters, revenue exposure, regulatory footprint, customer concentration, partnerships, and local infrastructure across North America, Europe, Asia Pacific, the Middle East, and Latin America.
Manufacturing & Capacity Benchmarking
How is Blockchain Capacity Measured Without Factories?
Blockchain has no factories, so capacity is measured through validator and node infrastructure, transaction throughput, cloud capacity, API requests, supported networks, custody infrastructure, and developer capacity.
The report compares infrastructure footprints, supported chains, validator exposure, data-center dependencies, geographic redundancy, security infrastructure, and capacity investments.
Customer & Channel Benchmarking
Institutional Distribution is Becoming a Major Competitive Moat
Customer relationships in the company now span from retail users to banks, asset managers, payment companies, fintechs, enterprises, developers, and governments. Institutional customers' needs often involve regulatory compliance, technical support, API integration, cybersecurity, and service-level commitments.
The report benchmarks direct institutional sales, developer ecosystems, partnerships, distribution networks, embedded finance relationships, and customer concentration.
Strategic Developments
apital is Flowing Toward Stablecoins, Tokenization, and Institutional Infrastructure
Investment picked up through 2025, with more than USD 20 billion going into blockchain and crypto startups. Later-stage deals took about 56% of Q4 investment, a sign that money is shifting toward scaling businesses with proven products and institutional demand. (Galaxy)
The report tracks major launches, partnerships, network expansions, institutional integrations, stablecoin initiatives, tokenization platforms, and infrastructure investments to show where leading companies are putting capital.
M&A Landscape
What are Acquirers Really Buying in Blockchain Deals?
The focus of mergers and acquisitions is shifting from blockchain protocols to technology capabilities, institutional customers, derivatives infrastructure, custody, compliance, stablecoin capabilities, and geographic footprint.
The analysis covers deal value, target revenue, strategic rationale, technology, geographic impact, and vertical-integration themes, and it identifies where and how consolidation could reshape market structure through 2035.
Company Profiles
Financial, Technology and Strategic Intelligence Across Leading Participants
Thorough analyses are made of each company's headquarters, owners, employees, revenue, market presence, products, blockchain technology, customers, geographical presence, infrastructure, R&D, partnerships, M&A, and strategic priorities.
For publicly traded companies, the analysis is based on revenues, growth rates, profitability, R&D, and investment. For private companies, the emphasis is placed on funding, products, customers, ecosystem outreach, and strategic activity, while avoiding any financial assessments that the data might not support.
Company Strategic Positioning
Scale, Trust, and Specialization Create Different Routes to Leadership
Participants are positioned qualitatively as market leaders, growth leaders, technology leaders, scale leaders, regional leaders, institutional specialists, application specialists, and emerging challengers.
The analysis weighs observable factors such as ecosystem depth, institutional penetration, technology differentiation, geographic reach, recurring revenue potential, and investment activity, rather than building a proprietary competitive score.
Opportunity & White-Space Analysis
Where are the Next Big Blockchain Profit Pools?
The strongest white spaces sit in regulated tokenization, cross-border payments, stablecoin infrastructure, institutional custody, interoperability, blockchain compliance, enterprise APis, and emerging-market financial infrastructure.
Tokenized real-world assets grew from about USD 5.4 billion to USD 19.3 billion in fifteen months, which shows how fast this area can expand from a small base. (CoinGecko) The full report sizes opportunity pools by geography, application, customer type, and technology layer.
Industry Structure
Security and Regulation Raise Entry Barriers While Open-Source Technology Lowers Them
| Force | Assessment | Key Evidence |
| Supplier Power | Medium | Providers depend on cloud, compute, cybersecurity, and specialized engineering talent. |
| Buyer Power | Medium–High | Institutional buyers demand compliance, interoperability, and reliable service. |
| New Entrants | Medium | Open-source protocols lower technical barriers, but trust and regulation raise the commercial ones. |
| Substitutes | Medium | Conventional databases, payment rails, and centralized platforms still work well for many uses. |
| Rivalry | High | Many protocols and infrastructure specialists compete across overlapping layers. |
PESTLE Analysis
How Policy, Capital, and Computing Will Shape the Next Adoption Cycle
- Political: Digital-asset policy and monetary sovereignty.
- Economic: Interest rates, liquidity, and institutional capital allocation.
- Social: Digital-asset adoption and consumer trust.
- Technological: Scaling, interoperability, privacy, and AI integration.
- Legal: Securities, stablecoin, custody, AML, and data requirements.
- Environmental: Energy use, validator design, and the shift toward more efficient consensus mechanisms.
Market Attractiveness
Growth is Highest Where Blockchain Solves a Measurable Problem
The most compelling areas are large transaction volumes, significant cost reductions, regulatory clarity, recurring infrastructure revenue, and high switching costs. Tokenized securities, stablecoin settlement, institutional custody, blockchain analytics, and interoperability increasingly meet those conditions.
The report evaluates attractiveness on market growth potential, monetization opportunities, competitive dynamics, regulatory barriers to entry, customer economics, technology maturity, investment requirements, and scalability.
Future Outlook
Will Programmable Money and Tokenized Assets Define the Next Decade?
By 2035, the blockchain technology market should be much larger, though the outcome depends on how much comes from speculative digital-asset activity versus durable enterprise infrastructure. Current trends suggest that stablecoins, tokenized securities, institutional custody, programmable settlement, interoperability, and blockchain-enabled financial infrastructure will be increasingly important profit pools.
The base case assumes continued institutional adoption and regulatory normalization. The upside case adds faster tokenization of financial assets, broader stablecoin payments, and quicker enterprise deployment. The downside case reflects fragmented regulation, cybersecurity failures, weak enterprise ROI, and slower institutional integration.
Competitive advantage will move steadily away from simply running a blockchain network and toward owning distribution, developer ecosystems, compliance infrastructure, institutional relationships, and interoperability layers.
Key Strategic Questions Addressed
- What is the economically addressable blockchain technology market excluding cryptocurrency asset capitalization?
- Which blockchain layers will capture the largest revenue pools through 2035?
- How quickly are stablecoins moving from crypto-native applications into mainstream payments?
- What is driving the rapid expansion of tokenized real-world assets?
- Which blockchain applications generate recurring versus transaction-based revenue?
- How are public, private, and hybrid blockchain architectures competing?
- Where are infrastructure capacity and interoperability becoming bottlenecks?
- Which customer segments have the highest willingness to pay for blockchain infrastructure?
- How concentrated are blockchain technology revenues across infrastructure, platforms, and services?
- Which companies have the strongest institutional, developer, and technology ecosystems?
- How are custody, compliance, analytics, and tokenization changing competitive dynamics?
- Where is M&A creating vertically integrated blockchain infrastructure platforms?
- Which geographies offer the largest adoption and expansion opportunities?
- Which emerging application and technology white spaces could create the next major blockchain profit pools?
Blockchain Technology Market segments
By Blockchain Type
- Public Blockchain
- Private Blockchain
- Consortium Blockchain
- Hybrid Blockchain
By Technology Layer
- Blockchain Infrastructure
- Middleware
- Protocol Layer
- Application Layer
- Blockchain-as-a-Service
By Application
- Payments & Settlement
- Smart Contracts
- Digital Assets & Tokenization
- Decentralized Finance (DeFi)
- Supply Chain Management
- Digital Identity
- Data Management
- Other Applications
By End Use
- Financial Services
- Government
- Healthcare
- Retail & E-commerce
- Manufacturing
- Logistics & Transportation
- Energy & Utilities
- Telecommunications
- Other End Users
By Deployment Model
- Cloud-Based
- On-Premises
- Hybrid
By Customer Size
- Large Enterprises
- Small & Medium-Sized Enterprises
By Business Model
- Subscription-Based
- Transaction-Based
- Licensing
- Infrastructure-as-a-Service
- Professional Services
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting