



Propylene Market Size, Production Capacity, Raw Material Pricing, Export & Import Analysis, Manufacturing Cost, Market Share, and Demand Forecast
The global propylene market was estimated at USD 116.23 billion in 2025 and is forecast to reach nearly USD 165.96 billion by 2035, registering a CAGR of 3.63% during the forecast period. The market growth is driven by rising demand for polypropylene, increasing use of propylene derivatives, and growing demand from the packaging, automotive, construction, electronics, and chemical industries.
Source: https://www.precedenceresearch.com/propylene-market
 Get a Sample
 Table Of Content


Propylene Market Size and Forecast 2026 to 2035
The global propylene market size accounted at USD 116.23 billion in 2025 and is anticipated to reach around USD 165.96 billion by 2035, growing at a CAGR of 3.63% between 2026 to 2035. The propylene market is driven by rising demand from the plastics, automotive, construction, and chemical industries.
Propylene Market Key Takeaways
- By Region, Asia Pacific held a majority revenue share of the propylene market in 2025.
- By Region, North America is expected to grow at the fastest CAGR in the market during the forecast period.
- By derivatives, the polypropylene segment held a dominant position in the market in 2025.
- By derivatives, the propylene oxide segment is expected to grow at the fastest CAGR in the market between 2026 and 2035.
- By type, the homopolymer segment accounted for a considerable revenue market in 2025.
- By type, the copolymer segment is expected to grow at the highest CAGR market during the study period.
- By application, the injection molding segment led the global market in 2025.
- By application, the film & sheet segment is expected to expand rapidly in the market with a CAGR coming years.
- By end user, the packaging segment held the largest revenue market in 2025.
- By end user, the electronics segment is expected to show the fastest growth with a CAGR over the forecast period.
Market Overview
Propylene is a colorless chemical substance that exists as a gas and is an organic component. It is a flammable hydrocarbon that is widely used as fuel. The majority of the propylene is removed during the refinement of crude oil. Propylene's molecular weight and chemical formula are 42.08 g/mol and C3H6, respectively. Propylene, also known as propene and derived from petroleum, is widely utilized in the production of resins, fibers, elastomers, and other chemical goods.
Key AI Integration in the Propylene Market
Artificial Intelligence is playing a larger role in the propagation of a plant and the enhancement of its efficiency in the production of propylene. Machine-learning models can be used to analyze production data, and machine learning can uncover ways to save energy. Process control using artificial intelligence can help optimize feedstock utilization and ensure the stability of product quality. Advanced analytics are also used to aid with forecasting demand, infusing planning decisions for inventory, and optimizing the supply chain.
Propylene Market Growth Factors
The rising need for effective plastic packaging materials drives global demand for polypropylene. PP offers a wide variety of characteristics that enable its use in several applications, including improved operating temperature, tensile strength, strong chemical resistance, and low moisture absorption. PP is widely utilized in injection moulding applications nowadays due to its ease of melting and moulding into any form or size without losing its original quality.
The market for PP is expanding due to the increased demand for lightweight polymers from the automotive, consumer goods, and electronics sectors. Spheripol, Unipol PP, Novolen, Innovene PP, Sherizone, and Borstar PP are just a few of the technologies that help businesses generate high-quality PP in accordance with customer specifications.
Strategic Growth Opportunities
- High-Growth Commercial Opportunities: The commercial prospects are growing with growing demand for polypropylene, propylene oxide, acrylonitrile and more. Growth in the automotive, packaging, construction, healthcare and electronics sectors is another growth driver.
- Emerging Technology Opportunities: Efficiencies and reduced emissions can be realised through using advanced catalysts, AI process optimisation and low-carbon production technologies. Companies can invest in recycled solutions for their companies using recyclables or bio feedstock generated from renewable sources.
- Geographic Expansion Opportunities: Asia-Pacific, MEA, and other emerging markets are expected to exhibit capacity expansion and downstream opportunity growth possibilities. Enhance the market presence of a region by strengthening local partnerships and having integrated production facilities.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 116.23 Billion |
| Market Size in 2026 | USD 120.60 Billion |
| Market Size by 2035 | USD 165.96 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 3.63% |
| Largest Market | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | By Derivatives, By Type, By Application and By End User |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America and Middle East & Africa |
Market Dynamics
Driver
Increasing demand of propylene derivatives
The propylene derivative used in polymers and viscoelastic fiber is acrylonitrile. Sweaters, socks, athletics, and home furnishings are among the products made of acrylic that account for the lion's share of the industry due to the global coronavirus pandemic expanding the need for medical equipment, acrylonitrile and propylene demand in the market. Acrylonitrile is also used in medical equipment such as valves, mechanical seals, and pumps.
Rise the demand in automobile sector
Throughout the projected period, the propylene market is going to expand due to the fast-rising demand for propylene in the automotive industry. The monomer of propylene, utilized in the automotive sector, is converted into polypropylene, a propylene polymer. The need for polypropylene goods, which are used to make bumpers, interior trim, instrument panels, battery boxes and trays, fender liners, door trims, and other machinery, has increased as a result of the large-scale manufacture of vehicles.
Restraints
Government rules and regulation concerns about safety
A significant barrier to the growth of the propylene industry has been the implementation of strict safety regulations in the manufacture and transportation of propylene. When subjected to high pressures and temperatures, propylene is poisonous, extremely flammable, and dangerous.
Propylene dealers should invest in technology, equipment, and procedures to reduce chemical and hazardous levels. These limitations raised the cost of manufacturing in the propylene sector, restricting opportunities for investments in product expansion, the introduction of new goods, and entry into new markets, which has an impact on market expansion.
Opportunities
Rising petrochemical industry
In order to expand the market share of propylene as a stand-alone product rather than an alternative or co-product, petrochemical firms are increasingly using on-purpose propylene manufacturing methods. A modified version of the conventional fluid catalytic cracking unit called on-purpose propylene technology increases propylene production to 20% or more of this output.
Oil refineries and steam crackers, which are the traditional sources of propylene, produce less propylene as a byproduct. Petrochemical businesses are investing in on-purpose technology growth to sustain the gap in propylene output to keep up with the increased demand for propylene. These elements will produce opportunities and accelerate propylene market growth.
Technological Advancement
Technological advancements in the propylene market feature AI integration, methanol to propylene (MTP) technology, process intensification, advanced catalysts, and on-purpose propylene production. AI optimizes the MTP production process and eases operations. It also monitors equipment performance, which helps in increasing productivity. MTP technology supports the environment by stabilizing sustainability. This technology is used in traction, an eco-friendly alternative for this market.
The advanced catalyst technology is used for catalyst design, also allowing propylene production even at lower pressure and temperature. Process intensification is a technique used to accelerate propylene production. On-purpose propylene production technologies are adopted by petrochemical companies. It is used in the production of propylene as a sole product. Additionally, it also consists of other technologies such as methanol-to-olefins/methanol to propylene and propane dehydrogenation (PDH).
Segmental Insights
Derivatives Insights
The propylene oxide segment is expected to witness strong growth during the forecast period, with demand for products based on polyenes intending to grow. Propylene oxide is a key chemical for the synthesis of polyether polyols and propylene glycol. Polyurethane foams are used for insulation and building purposes, and activity in the building sector has been growing, which is driving demand for these foams.
The cumene/phenol segment is projected to grow at a notable pace since it is extensively employed in the plastics, resins, and chemical intermediates manufacturing. Phenol is an important raw material for producing bisphenol A and phenolic resins. Rising consumption of polycarbonate and epoxy-based products is supporting consumption.
The acrylonitrile segment is expected to witness steady growth during the forecast period due to its wide application for the synthetic fibre and engineering plastics sectors. Acrylonitrile is heavily employed to prepare acrylic fibres, ABS plastics and specialty products. Demand for lightweight automotive components is helping to drive ABS demand. Consumer electronics also drive durable engineering plastics producers to grow.
Based on the derivatives, polypropylene is anticipated to hold the largest market share in 2024. The reason for this growth in the market is an increase in demand for derivatives, particularly polypropylene and propylene oxide. Naphtha cracking, which arises from refinery cracking production of other products and is used to manufacture ethylene, is a significant source of propylene. Propane dehydrogenation produces hydrogen as a byproduct while converting propane to propylene.
The two most often utilized propylene manufacturing processes globally are fluid catalytic cracking splitters and on-purpose technology (OPT). Films, fibers, containers, packaging, caps, and closures are a few examples of its final products. The automobile sector makes substantial use of polypropylene and its alloys. Several elastomeric fibers and polymers employ another derivative, acrylonitrile. It is utilized for acrylic fibers in clothing, such as sweaters, socks, beds, carpets, sportswear, pillows, and blankets.
Type Insights
The copolymer segment is expected to grow significantly during the forecast period, attributed to its better mechanical, chemical, and thermal properties. Copolymers are more versatile and effective than many of the traditional polymer materials. The momentum of automotive, packaging, electronics, and consumer goods sectors is driving adoption. The increasing opportunities for their use due to advances in polymer processing will be developed.
Based on type, the homopolymer segment held the more significant share of the propylene market in 2024. Over the projection period, the homopolymer category is expected to maintain its market dominance. Homopolymer polypropylene, which has a higher strength-to-weight ratio and is stiffer and more resilient than copolymer polypropylene, is mostly to blame. These qualities make it popular in many corrosion-resistant constructions, with strong chemical resistance and weldability.
Application Insights
The film & sheet segment is expected to grow steadily during the forecast period, supported by the growing demand for lightweight and durable packaging. Propylene-based materials can be used in a great variety of flexible packaging, food packaging, or industrial film applications, among others. The demand for protective packaging and convenient packaging is being boosted with the growth of E-commerce.
The fiber segment is projected to grow at a healthy pace due to the demand for low-cost, lightweight, and tough synthetic fibers. Propylene fibres are used in the production of carpets, industrial fibres, car interiors, and hygienic products. The increased demand for geotextiles and other technological textile usage is being driven by the increased building activity.
The blow molding segment is expected to experience considerable growth during the forecast period, as there is rising demand for lightweight plastic containers and packaging products. Demand is being supported by growth in the food, beverage, and personal care packaging sectors. New-generation packaging demands for durable and recyclable packaging are presenting new revenue opportunities.
Based on application, the injection moulding segment commanded the most significant market share for propylene in 2024 in volume and value. It will continue to hold this position, linked to the extensive use of injection molding. Polypropylene is used to make items of various sizes and forms, including home goods, automotive, marine, and recreational vehicle (RV) products. As a result, throughout the projected period, the market expansion in this category would be driven by the increased demand for moulded goods, such as rigid containers.
End User Insights
The electronics segment is expected to witness notable growth owing to the growth in production of consumer electronics appliances and electrical components. Propylene materials have lightweight, durability, and insulation properties which are appropriate to several electronic applications. Manufacturers are working on materials of improved properties designed for increasingly more demanding electronic applications.
The medical segment is expected to grow steadily, driven by increasing demand for lightweight, durable, and hygienic medical products. Plants use propylene to make containers for medicine, plastic medical syringes, laboratory and packaging products. Increased government spending on healthcare is driving growth of the medical device industry.
The consumer goods segment is projected to witness stable growth during the forecast period due to the demand for durable and lightweight household products. Polypropylene is applied to storage containers, appliances, components of furniture, and ordinary items. Polypropylene-based polymers are used in increasingly more consumer products; the use is expanding as innovation in the sector advances.
The end-user industry sector of the propylene market had the most considerable revenue in the packaging category in 2024, and this trend is anticipated to continue during the forecast period. It is due to the widespread use of propylene in food packaging, which comes into touch with food and drinks. Injection-moulded pots, thermoformed pots, and thermoformed trays are just a few examples of food packing containers that may safely use this rigid polymer since it is resistant to many chemical solvents.
Similarly, the increased manufacturing of vehicles is anticipated to drive up material sales in the automotive industry throughout the forecast period. The easy availability of PP and its attributes, like stain resistance, high durability, and flexibility, will facilitate the production of lightweight automobiles, lowering the cost and increasing the vehicle's energy efficiency. These elements will fuel market expansion in the automobile sector.
Regional Insights
Asia Pacific Propylene Market Size and Growth 2026 to 2035
The Asia Pacific propylene market size was exhibited at USD 47.65 billion in 2025 and is expected to be worth around USD 68.54 billion by 2035, rising at a CAGR of 3.70% between 2026 to 2035.
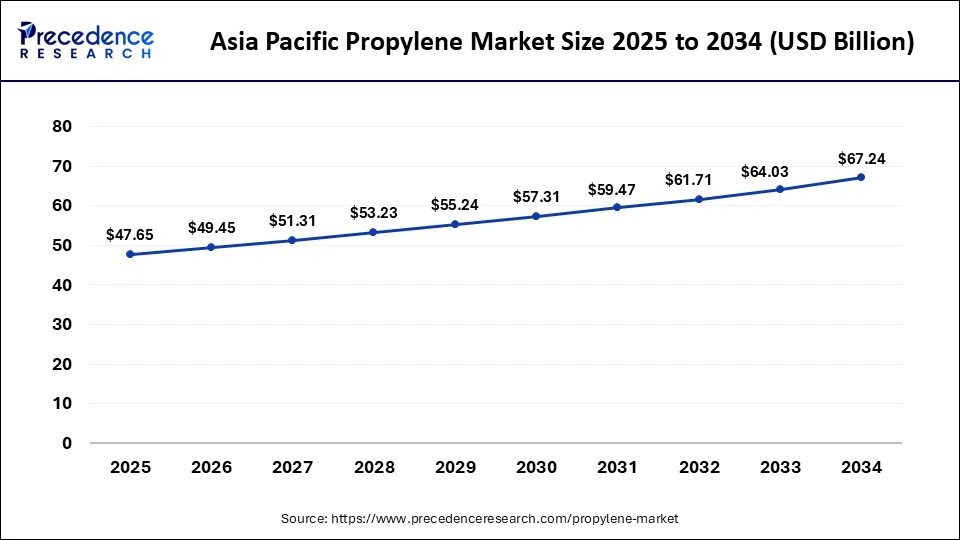
In 2024, the market in Asia Pacific holds the maximum revenue share. Due to rising demand from the packaging and automobile production industries, Asia Pacific is anticipated to expand rapidly in this market. Due to the growing use of PP in these nations' food & beverage, packaging, and care sectors, China, Japan, and India are significant contributors to the market growth in the area.
Due to the enormous prospects presented by the expanding automotive and construction sectors, major market players are attempting to increase their presence in the area.
Currently, Asia Pacific is dominating the propylene market. With the rapid growth in urbanization and industrialization is an instant rising demand for this market. Within the region, China is popular for consumer and producer of propylene and the successful growth of plastics, electronics, and textiles.
Over the projected period, North America is expected to account for a sizable percentage of the worldwide market. A significant market driver in the area is the expansion of the medical and electrical, and electronics manufacturing industries. Nonetheless, this region's market is expected to display a considerably lower CAGR compared to Asia Pacific.
The need for food and beverage packaging as well as the production of vehicles, would both increase propylene use in Europe. The region's leading producers, processors, and compounders are constantly working to develop new products for the automotive industry. The usage of goods in the healthcare and pharmaceutical, electrical and electronic, and other industries is another essential element boosting the growth of the PP market in Europe.
The market will experience considerable expansion in South America, the Middle East, and Africa due to rising infrastructure & development activity as well as shifting consumer lifestyle choices. Moreover, the Middle East and Africa will produce more PP due to the simple access to raw materials.
China Market Trends
China's propylene market is anticipated to grow significantly, owing to its huge petrochemical and manufacturing sector. The country has a huge demand in the downstream industries such as plastics, automotive fuel, packaging, and electronics. Domestic propylene production is being boosted by rising investments in propylene capacity. The increased demand for propylene derivatives is due to the boom in consumer goods and infrastructure. Demand for lightweight polymer materials is also growing along with China's growing EV industry.
U.S. Market Trends
U.S. market is anticipated to grow significantly, due to strong demand for plastics, automotive, construction, and chemical sectors. The country has already invested in the petrochemical industry as well as having access to competitive feedstocks. The increasing packaging market and durable polymer products market are expected to drive propylene demand. Investments focused on production efficiencies and process technologies are improving the competitiveness of the industry.
Advancements in the Propylene Market in Europe
Europe is expected to witness significant market growth throughout the forecast period, driven by rising demand for sustainable and premium quality polymer products. The automotive and packaging industries continue to be significant consumers in the area. Advanced polymer technologies are gaining importance in the growing trend of recycling and circular economy principles. Manufacturers are working on reducing carbon emissions from production due to high environmental requirements.
Germany Market Trends
Germany market is anticipated to grow significantly, as the automotive, chemical, and manufacturing industries are flourishing in Germany. The country has a sizeable demand for polymers and chemical derivatives based on propylene that is driven by its well-developed industrial base. With an upsurge in the production of electric cars, the need for lightweight, long-lasting plastic parts is surging. The use of propylene is also being encouraged in Germany's packaging sector and consumer goods industry.
Key Trends in the Propylene Market in Latin America
Latin America is expected to witness significant growth in the market driven by the growing manufacturing and petrochemical sector. Propylene demand from packaging, automotive parts, and consumer goods is helping to drive consumption. More and more people are raised in cities; this increases processed goods and the demand of plastic packaging. More propylene application opportunities are opening up from investments in industrial infrastructure.
Brazil Market Trends
Brazil propylene market is anticipated to grow significantly. Propylene consumption is growing in various sector industries as double demand for plastics and chemical products. As the food and beverage sector expands, so is the opportunity for polypropylene packaging. Demand for propylene-based materials is also being affected by the automotive industry and the construction industry in the country. Petrochemical investments relating to infrastructure are to enhance the supply capability at home.
Growth of the Middle East and Africa in the Propylene Market
The Middle East and Africa region is expected to witness significant growth in the market due to the developing manufacturing and petrochemical industry, which is anticipated to emerge. The area has significant hydrocarbon resources, and investment is rising in the petrochemical industry. Relying on packaging, construction, and consumer goods growth has signalled the growth in propylene use. Increasing investments in petrochemical facilities are creating new production and export opportunities.
Saudi Arabia Market Trends
Saudi Arabia market is anticipated to grow significantly, owing to its robust petrochemical industry and rich feedstock availability. Propylene and its derivatives are expected to expand with the country's investments in downstream chemicals. The market is also expanding due to the increasing demand for plastics, packaging, automotive components, and construction materials. To enhance production efficiency and product value, companies are investing in advanced technologies in the petrochemical industry.
Supply Chain Analysis-Propylene Market
- Quality Testing and Certification: Manufacturers test the propylene and derivatives to ensure purity, composition, physical properties, and performance in accordance with the customer specifications and industry needs.
- Packaging and Labelling: Products are contained in adequate tanks, containers, and bulk systems, and adequate product identification and handling, safety, and regulatory data are provided.
- Regulatory Compliance and Safety Monitoring: Employees work under chemical safety regulations, environmental regulations, and regulations concerning transportation and workplace activities, and continuous audit of the pollutants emitted, the process activities, their products, and the risk of processes and workplace tasks is performed at the companies.
Competitive Landscape
The propylene market is highly competitive as the key players include BASF SE, Repsol, Borouge, Borealis AG, and MOL Group. The leading companies are targeting their production to scale up, augment their integrated petrochemical enterprise, and enhance process efficiency to preserve their market positions. The companies are increasingly investing in new technologies and materials of value, such as those that make propylene derivatives, sustainable production processes, and meet customer demands.
International collaborations, growth strategies, and geographic diversification strategies are being leveraged to upgrade global presence and supply. The volatility in the price of feedstocks, environmental issues, and changes in supply and demand in the markets are creating problems for market participants.
Propylene Market Companies
- BASF SE
- Repsol
- Borouge
- Borealis AG
- MOL Group
- Beaulieu International Group
- LyondellBasell Industries N.V.
- ExxonMobil Chemical
- China National Petroleum Corporation
- INEOS
- China Petroleum & Chemical Corporation
- SABIC
- Ducor Petrochemicals
- Reliance Industries Limited
- Formosa Plastic Group
- Total S.A.
- Braskem
Collaboration Landscape
- In June 2025, Borealis and AnQore joined forces to implement more circular solutions and use renewable feedstocks in acrylonitrile value chains. The partners hope to reduce carbon production and to create more sustainable propylene-derived products. (Source: https://www.borealisgroup.com)
Recent Developments
- In September 2024, global bio-polymer producer Braskem launched a bio-polypropylene (bio-PP) product from used cooking oil (UCO). The bio-PP is suitable for a range of applications, including food packaging and flexible packaging (such as films).
- In February 2025, Genpak LLC launched its new line of polypropylene bowls and lids, Grab a bowl. The product features easy-grip tabs and is also suitable for both hot and cold meal applications.
- In August 2024, Pactiv Evergreen Inc., a food and beverage packaging manufacturer based in Lake Forest, Illinois, launched Recycleware, reduced-density polypropylene (RDPP) meat trays. The product is a solution for packer processors seeking alternatives to foam polystyrene (PS).
- July 2022: The Canadian company Heartland Polymers fully commissioned its polypropylene (PP) plant with a planned production capacity of 525,000 tons/year of polypropylene at the Heartland Petrochemical Complex in Alberta, Canada.
- June 2022: Linde Engineering announced that the company started working on a large-scale revamp of a polypropylene (PP3) plant of Slovnaft, a member of the MOL Group situated in Bratislava, Slovakia. The revamp will extend the plant's production capacity by 18% to 300 kilotons of polypropylene per year and the expansion of the storage facility from 45 to 61 silos in total.
- In February 2022, Braskem which is one of the major polyolefins manufacturers companies, as well as also a market leader of biopolymers has declared the enlargement of its circular polymer portfolio and include two new polypropylene (PP) grades with post-consumer recycled (PCR) content. Braskem's new PCR polypropylene grades would be used in an extensive array of U.S based Food and Drug Administration (FDA) food contact applications where polypropylene is used today, like in housewares, caps and closures, consumer packaging, and others.
- In January 2022: INVISTA is a Koch company and this company is associate either Flint Hills Resources which has attained the Flint Hills Resources propylene business efficiently from Jan. 1, 2022. This includes the chemical facilities in Texas, Longview and Houston, along with the employee's support. The possession of the pipelines which deliver these facilities also moved their business to INVISTA but will continue to be worked by Flint Hills Resources under an agreement.
- In February 2022, ExxonMobil announced that they will tart polypropylene capacity in Louisiana, U.S. by the end of 2022. This expansion is budgeted at US$ 500 million. Through this expansion, ExxonMobil will enhance their market presence in the U.S. and adjoining countries.
- In April 2021, Braskem S.A. launched a carbon-fiber-reinforced polypropylene filament for additive manufacturing. The filament is lightweight and rigid, thus ideal for automotive, aerospace, marine, and sporting goods applications.
- In April 2021, Sulzer Ltd. and Borealis AG launched a new polypropylene foam extrusion technology, enabling lower cost and increased efficiency across the value chain. The companies have completed the development of an advanced process for the cost-effective extrusion of expanded polypropylene (ePP) beads.
- In December 2020, LyondellBasell launched Beon3D, an innovative PP product range that will provide unique design and allow the production of high-quality, complex 3D printed objects within one step. This product was produced by combining polymer technologies and additive manufacturing. This product range will serve transportation, industrial, building & construction, and consumer goods markets.
Segment Covered in the Report
By Derivatives
- Polypropylene
- Propylene Oxide
- Cumene/Phenol
- Acrylonitrile
- Acrylic Acid
- Oligomers
- Alcohols
- Acrylates
- Others
By Type
- Homopolymer
- Copolymer
- Random
- Block
By Application
- Injection Molding
- Film & Sheet
- Raffia
- Fiber
- Blow Molding
By End User
- Packaging
- Electronics
- Medical
- Consumer Goods
- Automotive
- Construction
- Textile
- Agriculture
- Other
By Geography
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
