
Data Center Automation Market Size, Key Companies, Company Market Share, AI Adoption, Cloud Deployment, Automation Technology, Data Center Expansion, Energy Efficiency, and Competitive Positioning
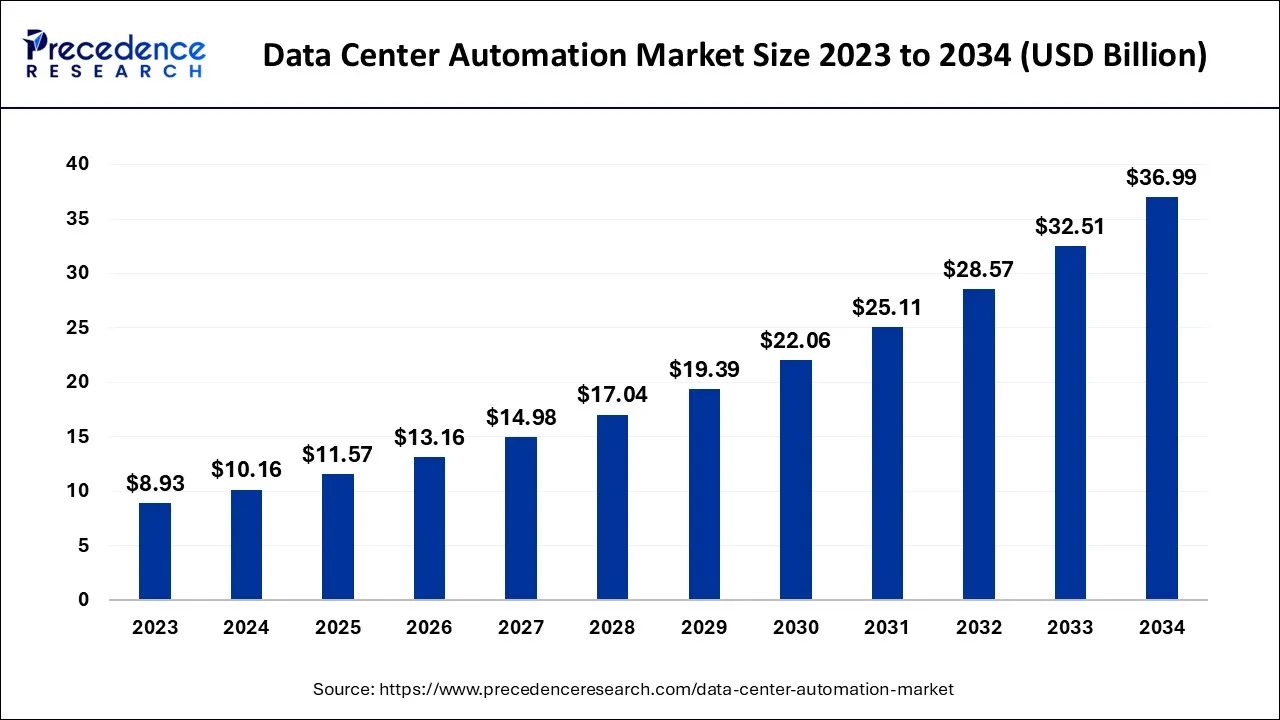
ICT industry specialist Shivani Zoting estimates the data center automation market at USD 13.16 billion in 2026, with continued technology adoption expected to take the market to USD 41.11 billion by 2035 at a CAGR of 13.52%. Leading data center automation market providers such as Cisco Systems Inc., ABB Limited, Oracle Corporation, are expanding their capabilities across segments including by solution, by service, by deployment, by enterprise, by vertical.
Source: https://www.precedenceresearch.com/data-center-automation-market
 Get a Sample
 Table Of Content


What is the Data Center Automation Market Size?
The global data center automation market size is accounted at USD 11.57 billion in 2025 and predicted to increase from USD 13.16 billion in 2026 to approximately USD 41.11 billion by 2035, representing a CAGR of 13.52% from 2026 to 2035. The generative AI boom, high-density workloads, and increased focus on on-site energy management and efficiency optimization are expanding the data center automation sector.
Data Center Automation Market Key Takeaways
- North America generated more than 42% of the revenue share in 2025.
- By Solution, the server automation segment captured more than 52% of revenue share in 2025.
- By Service, the installation and support services segment contributed to the highest market share in 2025.
- By Deployment, the cloud segment generated more than 52% of revenue share in 2025.
- By Enterprise, the large-size enterprise segment captured more than 70% of revenue share in 2025.
- By Vertical, the Telecom& IT segment generated for the maximum market share in 2025.
Market Overview
What is Data Center Automation?
The implementation of automation reduces manual errors, while automated monitoring detects complex issues immediately. It aims to reduce response time from hours to minutes and boost pre-established recovery processes. It has also eliminated IT infrastructure failures that are caused by equipment issues, human mistakes, or delayed troubleshooting responses. Smart automation potentially manages airflow, cooling, and resources to handle thermal loads and the extreme power densities that are created by edge computing deployments and massive AI clusters. The workflow of data centers is changed by the rapid growth of AI, cloud computing, digital services, and edge computing.
How does AI Transform the Data Center Automation Market?
The key features of an AI-ready data center are high-performance computing, advanced storage architecture, resilient and secure networking, and adequate power and cooling solutions. AI accelerators are AI chips that are used to speed up machine learning and deep learning models, AI operations, and natural language processing. AI-ready data centers include neural processing units and tensor processing units, which are more specialized AI accelerators. AI data center networking must be able to support the high-bandwidth needs of AI workloads with low latency.
Major Trends
- The data center automation market is increasingly embracing machine learning technologies instead of using static and rule-based methods to predict hardware failure, optimize workloads, and allow autonomous self-healing.
- AI applications are significantly increasing electricity demands; automated solutions are being used to control liquid cooling systems, balance grid loads and support utility providers and minimize overall power usage.
- Many organizations are scaling across dispersed backgrounds where advanced automation platforms are streamlining operations, configurations, and offering solutions across edge, public cloud, and on-premises architectures.
- The market is witnessing expansion of IoT and real-time processing that needs local data centers nearer to the end-user. Automated platforms ensure seamless coordination between various micro data centers located at different geographical locations.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 11.57 Billion |
| Market Size in 2026 | USD 13.16 Billion |
| Market Size by 2035 | USD 41.11 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 13.52% |
| Largest Market | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | By Solution, By Service, By Deployment, By Enterprise and By Vertical |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America and Middle East & Africa |
Market Dynamics
Drivers
The growing global use of the internet and networking has significantly increased the demand for computing power, additional storage space and complex networking. This requirement has caused infrastructure development in current data centers, raising capital and operating expenditures for data centers and enterprises. This expansion has also enhanced the complication of networking, integration, and resource pooling in data centers. These factors are critical to the growth of the global data center automation market.
To address the concerns of the growing need for resource pooling, networking simplification, and overall data center management, innovators developed the complex conception of data center automation, also known as Software-Defined Data Centers (SDDCs). This enables conventional data center operators to level up their current infrastructure effortlessly, resulting in lower overheads. This additionally contributes to the integration of server storage and networking and the streamlined management of all resources. Data center automation assists enterprises and service providers in managing their active data centers and networks by overcoming the challenges of scalability, flexibility, manageability, and cost reduction.
Restraints
Lack of skilled professionals
Given the number of new technology innovations on the market, it is vital to have employees who are skilled in maintaining and programming advanced technologies. When addressing skill shortages, the data center skills difference is broadening. According to a study, more than half of data center workers need help recruiting staff as of April 2021. Moreover, the number of employees required to operate global data centers is expected to rise from 2 million in 2019 to approximately 2.3 million in 2025, implying that the number will increase even further.
According to the survey, 29% of respondents needed help recruiting cloud professionals, while 26% had difficulty recruiting data center facilities, engineering, and technicians. Furthermore, 25% of respondents reported needing help finding qualified candidates for network security, IT and data center management, and DevOps. Thus, the lack of skilled professionals restricts the market growth.
Opportunity
Rapid advancement in technology
The rapid advancement in technology transforming data centers, such as server virtualization, is expected to drive the market. Many manag
ed service providers (MSPs) and data centers are migrating to Software-Defined Data Centers to reduce infrastructure burdens (SDDCs). Virtualization technologies recreate computing power and storage in software form in an SDDC model. In contrast to the traditional, inefficient method of issuing one server to each user, server virtualization enables data centers and service providers to house multiple users on a single server by segmenting servers.
Since workloads are distributed across multiple servers, virtualization improves scalability. This model effectively functions as a cloud model, with the service provider allocating data storage and processing power on an 'as needed' basis. Virtualization also improves efficiency by ensuring that resources are used to their full potential.
Segments Insights
Solution Insights
Based on the solution segment, the data center automation market is segmented into network automation, server automation, and storage automation. In 2025, the server automation segment accounted for the largest market share of 52% and is expected to grow at a faster rate during the forecast period.
The growth of the segment is driven by the growing demand for efficient servers, which led to adequate network and storage facilities. Server automation benefits include clean architecture, secure and reliable, more accessible and reliable environment setup, instant feedback, software policies, range of interfaces and tools, testing and rollback of deployments. Server automation can help ease and accelerate the deployment process in various ways, beginning with the emergence of test environments.
Test environments that employ the same procedures as production enables developers to see how new features perform before releasing them to the final customer. Thus, server automation combines task and process automation to improve application deployment and administration across virtual and physical servers and provides end-to-end management via automated workflows, which reduce human errors.
Service Insights
The data center automation market is segmented based on services: consulting, installation, and support services. In 2023, the installation and support services segment accounted for the largest market share. All services provided to set up and integrate all data center management processes into one unified, simple, and highly efficient platform are referred to as installation and integration services.
Deployment Insights
Based on deployment, the data center automation market is segmented into on-premises and cloud. In 2025, the cloud segment accounted for the largest market share at about 52%. Businesses provide features and functions with greater efficiency and flexibility due to cloud deployment and growing cloud adoption reduces costs and maintenance requirements.
Organizations that use cloud-based solutions can gain access to a large number of data centers and cloud platforms for analysis and mapping.
Fastest Growing Segment: The on-premise segment is the fastest-growing segment as of this year. This rapid growth is driven by organizations that are prioritizing data security, control, and regulatory compliance. On-premise solutions help companies to maintain oversight over their infrastructure, which is vital for those who handle sensitive data, such as finance, healthcare, and government. This segment ensures that data is stored and protected in a controlled environment, thus mitigating potential risks.
Enterprise Insights
Based on the enterprise, the market is segmented into large-size enterprises and small-size enterprises. In 2023, the large size enterprise accounted for the largest market share of about 70% and is expected to grow faster during the forecast period. Companies must store massive volumes of daily data due to the rise of complex business tools such as data analytics and big data. Multinational corporations typically select data centers with superior data security, fueling segment growth.
Fastest Growing Segment: Small and medium enterprises (SMEs) are expected to grow at the fastest rate throughout the forecast period. The increasing adoption of digital technologies and the growing need for efficient data management solutions are driving the demand for this segment. This is because it helps to leverage advanced data management and automation capabilities without the need for any substantial investments in data center infrastructure.
Vertical Insights
Based on the vertical segment, the market is segmented into telecom and information technology (IT), media and entertainment, healthcare, banking, Financial Services and Insurance (BFSI), Public Sector, Manufacturing, Retail, and Others. In 2023, the Telecom& IT segment accounted for the largest market share. This is primarily due to the advancement of mobile technologies and the increasing demand for high-speed data services. The expansion of the IT and telecommunications industries benefited the economy by creating new jobs and business opportunities. Consumer prices have decreased due to increased competition among service providers.
Fastest Growing Segment: The BFSI (Banking, Financial Services, and Insurance) sector is set to witness the fastest growth throughout the forecast period. This rapid growth is fueled by the need for efficient data management, regulatory compliance, and the increasing adoption of digital banking services. Data center automation solutions help to manage vast amounts of data more effectively, thus ensuring regulatory compliance and enhancing overall operational efficiency.
Regional Insights
What is the U.S. Data Center Automation Market Size?
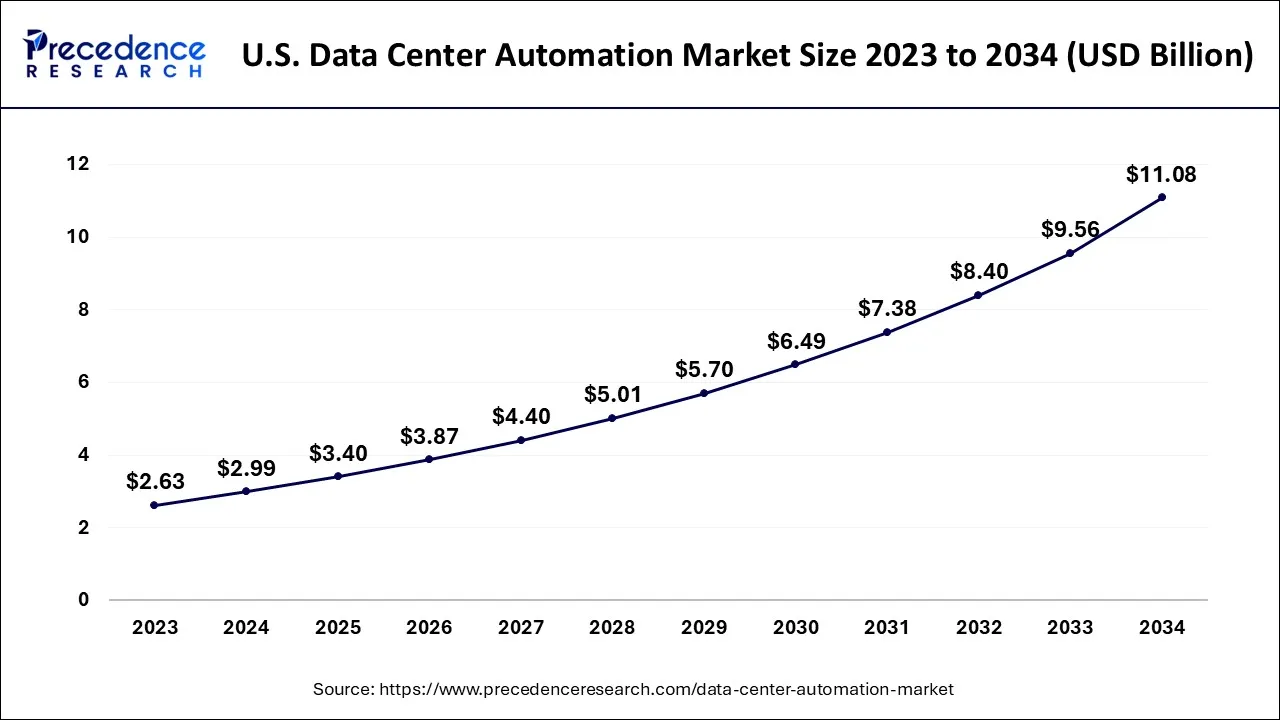
The U.S. data center automation market size is exhibited at USD 3.40 billion in 2025 and is projected to be worth around USD 12.60 billion by 2035, growing at a CAGR of 14.01% from 2026 to 2035.
In 2025, North America dominated the global data center automation market with the highest share of around 42%. The growth of this region is due to technological advancements and their adoption. It has a well-equipped infrastructure and the financial means to purchase data center automation software solutions. Furthermore, using data center automation tools improves efficiency and lowers costs for data center operations such as incident and event management. End-user industries can use it to monitor infrastructure, applications, performance, and security features.
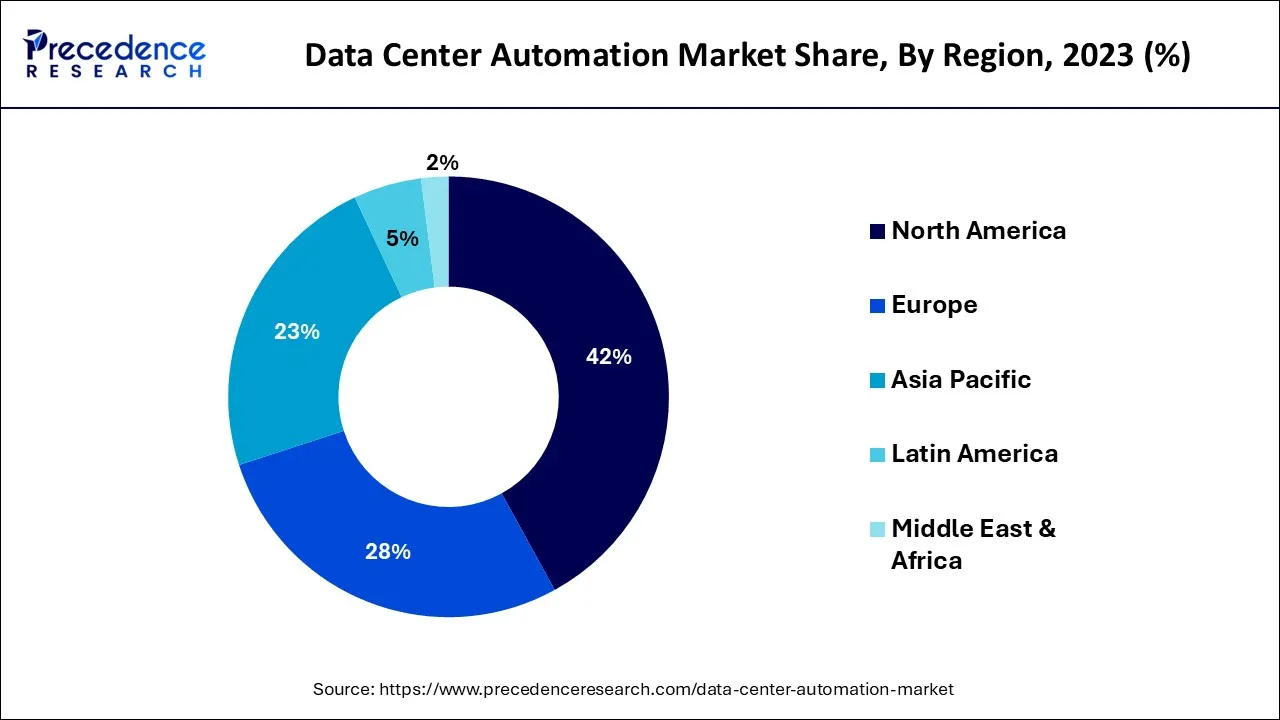
In North America, data center automation solutions used in industries such as BFSI, IT & telecom, and media & entertainment are rapidly increasing. However, due to the large number of people who use social media and the presence of developing countries such as India, China, and South Korea, Asia-Pacific is the dominant region in the global data center automation market.
U.S. Data Center Automation Market Analysis
The market in the U.S. is rapidly growing, driven by AI and machine learning integration, expanding cloud and hybrid infrastructure, and increasing operational efficiency. Additionally, increasing integration of AI and machine learning, which enhances operational efficiency and reduces downtime, and the rising demand for automated management and monitoring solutions drive the market.
- In July 2025, the U.S. Department of Energy (DOE) announced the site selection for a new AI data center and energy infrastructure on federal lands.
Why is the Asia Pacific Considered a Significant Region in the Data Center Automation Market?
Asia Pacific is a significant region in the data center automation market due to rapid digital transformation, growing cloud adoption, and increasing investment in hyperscale and edge data centers. The region's expanding IT infrastructure and rising demand for efficient, AI-driven operations are driving widespread adoption of automation solutions. The surge in AI workloads, growing adoption of hyperscale cloud and hybrid cloud, mandates sustainability and energy efficiency, and government digitalization initiatives also support regional market growth.
India Data Center Automation Market Analysis
In India, the market is growing due to the rapid adoption of cloud computing, AI, and machine learning technologies across enterprises and service providers. Additionally, increasing investments in data center infrastructure and the rise of digital services are driving demand for automated management and operational efficiency solutions.
- In January 2025, Sify Technologies announced to invest $5 billion to expand data centers and AI operations in India.
How is the Opportunistic Rise of Europe in the Data Center Automation Market?
Europe is experiencing an opportunistic rise in the market due to increasing adoption of AI-driven management solutions, stringent energy efficiency regulations, and growing demand for cloud and hybrid infrastructure. Additionally, investments in smart data centers and sustainable IT operations are creating opportunities for automated monitoring, optimization, and predictive maintenance solutions across the region.
- In November 2025, Google announced the investment of €5.5 billion in AI infrastructure through 2029 in European countries like Germany.
What are the Advancements in the Data Center Automation Market in Europe?
Germany Data Center Automation Market Trends: The region's market landscape is propelled by its well-established industrial base and a strong focus towards Industry 4.0. The need to streamline data center operations and support IoT-based initiatives encourages automation. In addition, the region has strict regulations regarding data security, which helps to push companies toward advanced automation systems and tools.
What are the Major Factors Contributing to the Data Center Automation Market within Latin America?
The market in Latin America is driven by the rapid digitalization of businesses, increasing adoption of cloud and hybrid infrastructure, and the need for efficient IT operations. Growing investments in hyperscale and edge data centers are further fueling demand for automated management, monitoring, and predictive maintenance solutions. Additionally, government initiatives to enhance digital infrastructure and rising demand for energy-efficient and reliable data centers are supporting market growth across the region.
- Chile released the Guía para la Inversión en Data Centers in 2024 to guide companies through the complex process of setting up data centers, anticipating around $4 billion in upcoming projects. The guide is part of the national data centers plan (Pdata) and was developed by the Ministry of Science, Technology, and Innovation.
What Potentiates the Market in the Middle East & Africa (MEA)?
The data center automation market in the Middle East & Africa is potentiated by rapid digital transformation, increasing cloud adoption, and growing investments in hyperscale and edge data centers. Additionally, the demand for energy-efficient, AI-driven operations and government initiatives to enhance IT infrastructure is driving market growth in the region. Saudi Arabia is a major contributor to the market in the MEA due to rapid digitalization, significant investments in cloud and hyperscale data centers, and government initiatives like Vision 2030 that emphasize smart infrastructure and AI-driven operations.
Saudi Arabia Data Center Automation Market Trends: The region's market landscape is evolving rapidly, driven by the need for efficient IT infrastructure management, cost reduction through energy efficiency, and stringent compliance and security requirements. The expansion of 5G networks, artificial intelligence, and big data analytics is further increasing the need for scalable and software-defined data center operations.
Latin America Data Center Automation Market Analysis
The region is witnessing rapid expansion in the data center automation market due to the explosive growth of AI workloads, hyperscaler's massive investments, and the increasing demand for high-density power. Organizations in Latin America are adopting automation to optimize complex operations, standard processes, and manage IT demands.
Mexico Data Center Automation Market Analysis
Mexico is considered as the fastest-growing region that supports Latin America data center automation market. The market's growth is attributed to hubs like Queretaro backed with nearshoring and proximity to the US cloud regions. Also, the region hosts various operational submarine cables like ARCOS, and AMX-1, supporting the region's growth in the data center automation market.
Competitive Landscapes
The global data center automation market boasts highly fragmented and competitive landscape largely driven by AI workloads and multi-cloud architectures. Vendors are competing to offer predictive, self-tuning, and energy efficient platforms by using artificial intelligence and machine learning technologies. The leading technology players like Microsoft, IBM, Dell Technologies, and HPE offer highly comprehensive automation solutions that are designed to manage evolving hybrid environments. Similarly, Red Hat offers open-source orchestration via platforms like Red Hat Ansible.
Also, the market is witnessing strategic partnerships like collaboration of ABB and ATS global as software organizations and system integrators bridges resources to offer holistic, and edge-to-cloud automation. Vendors that are able to provide automated and fine-grained power with cooling controls are gaining strong hold and competitive edge as data center electricity demand surges.
Company Profiles
Cisco Systems Inc.
- HQ: San Jose, California, United States
- Founded: 1984
- Ownership: Publicly traded company owned by large institutional investors, mutual funds, and individual shareholders.
- Business Overview: Cisco Systems Inc. dominates the data center automation and networking industry through AI infrastructure integration, uniform platform strategies, and robust hardware-software innovation. The company has retained its position in scaling its portfolio and as a primary industry leader in data center networking solutions.
- Products: Core management and orchestration platforms, advanced AI infrastructure, and hardware-integrated automation and security.
- Geographic Presence: Cisco Systems Inc. has divided its global operations into three primary geographic segments: EMEA, Asia Pacific, Japan, and China (APJC), and the Americas. It operates globally in over 90 countries with more than 275 offices globally.
- Revenue: Cisco Systems Inc. reported revenue of $63.3 billion for the full-year fiscal 2026, which represents a 12% increase year-over-year.
- Recent Development: In August 2026, Cisco Systems Inc. launched a sovereign critical infrastructure in Canada. It will give greater control and choice to healthcare and other critical infrastructure providers, financial institutions, and government over how they run their technology.
- Key Strategies: AI infrastructure and data center dominance, unified security cloud and platform integration, business model transformation, system operations, network security, and data visibility.
ABB Limited
- HQ: Zurich, Switzerland
- Founded: 1988
- Ownership: Publicly traded, multinational corporation
- Business Overview: ABB Limited is expanding its role in the power infrastructure and data center automation industry through strategic acquisitions, major regional investments, and AI-driven energy solutions.
- Products: Core automation software and ecosystems, electrical and power management infrastructure, predictive maintenance and monitoring, modular automation software, AI-ready power architectures, and predictive maintenance.
- Geographic Presence: ABB Limited operates in approximately 100 countries globally, with its headquarters located in Zurich, Switzerland.
- Revenue: ABB Limited reported an annual revenue of $33.22 billion for the full year 2025.
- Recent Development: In March 2026, ABB Limited invested ~$75 million in India for the expansion of R&D and manufacturing for critical segments. The company reported significant capital expenditure to accelerate R&D and manufacturing in India for critical electrification solutions.
- Key Strategies: Division accountability, agility, digitalization and AI integration, sustainability, low-carbon performance, targeted portfolio management, localizing supply chains, industrial IoT solutions, software innovation, eco-efficiency products, internal net-zero operations, etc.
Oracle Corporation
- HQ: Austin, Texas
- Founded: 1977
- Ownership: Owned by co-founder Larry Ellison and large institutional asset managers
- Business Overview: Oracle Corporation is expanding its global footprint through massive capital investments in Oracle Cloud Infrastructure. Oracle implemented non-evaporative, closed-loop cooling systems and signed clean-energy and ratepayer protection pledges.
- Products: Hybrid and on-premises cloud automation, intelligent and distributed data platforms, multi-cloud control planes, and edge and AI supercomputing automation.
- Geographic Presence: Oracle Corporation has a vast global footprint with cloud data centers, offices, and operations across 175 countries and North America, the Middle East, Europe, Africa, Latin America, and the Asia Pacific region.
- Revenue: Oracle Corporation generated total annual revenue of $67.4 billion for fiscal year 2026.
- Recent Development: In February 2026, Oracle Corporation planned to raise US$ 45-50 billion to support the expansion of cloud infrastructure. It also aims to establish additional capacity to meet growing consumer demands from potential clients like Meta, AMD, OpenAI, NVIDIA, TikTok, and xAI.
- Key Strategies: Expansion of high-performance AI infrastructure, embedding AI into SaaS applications, distributed and sovereign cloud deployments, and multicloud alliances.
Microsoft Corporation
- HQ: One Microsoft Way, Redmond, Washington, U.S.
- Founded: 1975
- Ownership: Publicly traded company
- Business Overview: Microsoft Corporation manages an expansive network scaling to more than 400 data centers and 80 Azure regions globally.
- Products: On-premises and hybrid infrastructure management, cloud native automation, governance, process automation, Azure automation, Azure Logic Apps and Azure Functions, Microsoft System Center 2025, etc.
- Geographic Presence: Microsoft Corporation operates in over 190 countries and more than 100 countries globally, while managing major hubs, offices, and cloud data centers across four core regions, including the Americas, Europe, Asia Pacific, and the Middle East and Africa.
- Revenue: Microsoft Corporation reported total annual revenue of $331.8 billion for the fiscal year 2026.
- Recent Development: In August 2026, Microsoft Corporation announced the expansion of its newest India data center region to empower the country's AI economy and enable Frontier firms. It gives organizations more local choice to build new digital services, modernize critical systems, and turn AI ambition into faster decisions and stronger customer outcomes.
- Key Strategies: Ubiquitous AI integration and copilot ecosystem, cloud supremacy via Azure, high-margin subscription financial model, the ‘secure future' initiative, and aggressive M&A and partnership strategy.
BMC Software
- HQ: Texas, U.S.
- Founded: 1980
- Ownership: Owned by funds managed by the global investment firm KKR
- Business Overview: BMC Software strongly manages file transfers, multi-cloud data pipelines, and application workflows. It also integrates generative AI tools and machine learning to help enterprises automate certificate lifecycles, modernize code, and drive self-managing mainframe data center environments.
- Products: Control-M platform, BMC automated mainframe intelligence portfolio, DataOps and managed file transfer, agentic AI and Jett integration, deep multi-system pipeline integration, etc.
- Geographic Presence: BMC Software operates globally, with its headquarters in Texas and its business across Europe, the Americas, the Asia Pacific, Africa, and the Middle East.
- Revenue: BMC Software generated over $2.3 billion in annual revenue, and the company is privately owned by KKR.
- Recent Development: In April 2026, BMC Software expanded AI-powered mainframe solutions and announced new innovations with purpose-built AI integrated into the mainframe tools.
- Key Strategies: Structural specialisation, generative AI and agentic orchestration, mainframe modernisation and inclusion, end-to-end enterprise data orchestration, and transition to AIOps and observability.
Data Center Automation Market Companies
- Cisco Systems Inc.
- ABB Limited
- Oracle Corporation
- Microsoft Corporation
- BMC Software
- ServiceNow
- Citrix Systems, Inc
- Hewlett Packard Enterprise Development LP
- FUJITSU
- VMWare
Recent Developments
- In December 2025, NTT DATA, a global leader in digital business and technology services and AI, launched four next-generation autonomous Cyber Defense Centers powered by AI technologies. They were launched in Mumbai, Hyderabad, and Noida, with two additional centers set to open in Dallas and Birmingham by January 2026. (Source: https://www.nttdata.com/en-ca/news/2025/ntt-data-announces-six-new-ai-powered-cyber-defense-centers
- In November 2025, ABB and VoltaGrid formed a partnership to enhance grid stability and data center power supply in the U.S. to support the growth of AI. ABB is leading in supplying prefabricated eHouse units and 27 synchronous condensers to enable stable electricity generation. (Source: https://new.abb.com/news/detail/130817/abb-and-voltagrid-partner-to-deliver-stable-data-center-power-to-support-ai-growth
- In October 2025, OMRON launched an automation center in Bengaluru to advance smart manufacturing in India.
- In September 2024, Nokia launched the most modern data center automation platform, specifically established for the AI era.
Segments Covered in the Report
By Solution
- Network automation
- Server automation
- Storage automation
By Service
- Consulting service
- Installation and support services
By Deployment
- On-Premises
- Cloud
By Enterprise
- Large Size Enterprises
- Small and Medium Sized Enterprises (SMEs)
By Vertical
- Telecom and Information Technology (IT)
- Media and Entertainment
- Healthcare
- Banking
- Financial Services and Insurance (BFSI)
- Public Sector
- Manufacturing
- Retail
- Others
By Geography
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting