
Ambulatory Infusion Centers Market Size, Trends, Segmentation, Key Companies, and Forecast 2026-2035
Ambulatory Infusion Centers Market (By Therapy Type: Anti-infective Therapy, Hydration Therapy, Chemotherapy, Immunoglobulin Therapy, Biological Therapy, Enteral and Parenteral Nutrition, Others (e.g., corticosteroids, pain management infusions); By Application: Oncology, Autoimmune Disorders, Neurological Disorders, Infectious Diseases, Gastrointestinal Disorders, Immune Deficiencies, Others; By End-User: Hospital-Affiliated Infusion Centers, Physician Office Infusion Centers (POICs), Standalone/Independent Infusion Centers, Home Infusion Service Providers; By Payor Type: Commercial Insurance, Medicare, Medicaid, Out-of-Pocket / Self-Pay) - Global Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2035
Source: https://www.precedenceresearch.com/ambulatory-infusion-centers-market
 Get a Sample
 Table Of Content


What is the Ambulatory Infusion Centers Market Size?
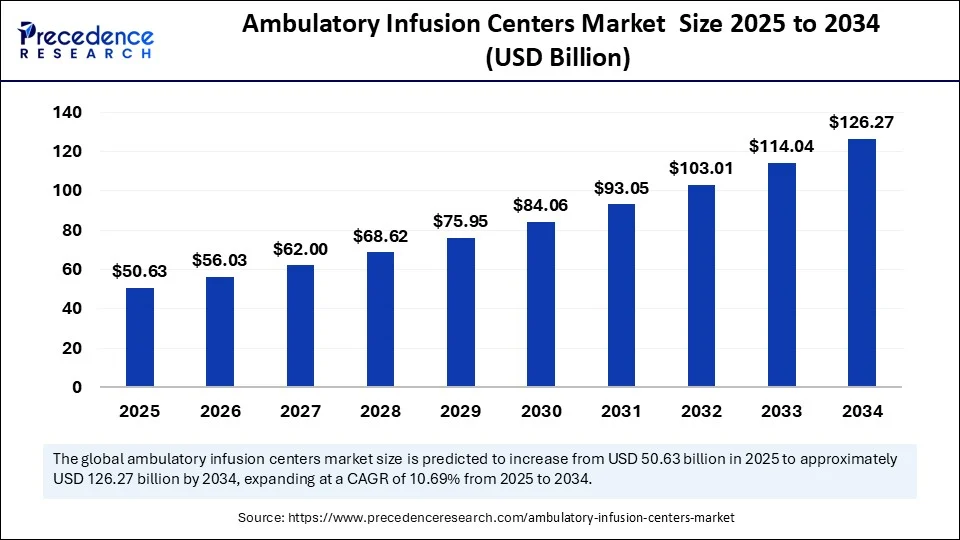
The global ambulatory infusion centers market size was valued at USD 56.03 billion in 2026 and is projected to reach approximately USD 137.70 billion by 2035, growing at a CAGR of 10.51% from 2026 to 2035. The ambulatory infusion centers market is experiencing robust growth due to the increasing number of cases of chronic diseases, such as diabetes, cancer, and autoimmune diseases. The rising demand for outpatient services due to the increased healthcare costs further contributes to market growth.
Ambulatory Infusion Centers Market Key Takeaways
- In terms of revenue, the global ambulatory infusion centers market was valued at USD 56.03 billion in 2026.
- It is projected to reach USD 137.70 billion by 2035.
- The market is expected to grow at a CAGR of 10.52% from 2026 to 2035.
- North America dominated the ambulatory infusion centers market with the largest market share of 58% in 2026.
- Asia Pacific is expected to expand at the fastest CAGR between 2026 and 2035.
- By therapy type, the biological therapy segment held the biggest market share of 28% in 2026.
- By therapy type, the immunoglobulin therapy segment is anticipated to grow at a remarkable CAGR between 2026 and 2035.
- By application, the autoimmune disorders segment captured the highest market share of 33% in 2026.
- By application, the oncology segment is expected to expand to a notable CAGR over the projected period.
- By end user, the standalone/independent infusion centers segment contributed the major market share of 42% in 2026.
- By end user, the physician office infusion centers segment is expected to expand at a notable CAGR over the projected period.
- By payor type, the commercial insurance segment generated the largest market share of 48% in 2026.
- By payor type, the Medicare segment is expected to expand at a notable CAGR over the projected period.
What are Ambulatory Infusion Centers?
The ambulatory infusion centers market refers to the healthcare services ecosystem comprising outpatient facilities where patients receive intravenous (IV) therapies, biologics, antibiotics, and specialty medications without hospitalization. These centers are typically staffed by nurses and clinical professionals and are used for chronic disease management (e.g., autoimmune diseases, cancer, neurological disorders) in cost-effective, non-acute care settings. Their growth is driven by rising biologic use, payer cost-containment policies, increasing outpatient preference, and specialty drug approvals.
The market is evolving with the move from inpatient to outpatient care and emerging infusion technologies and digital monitoring devices. The increased pertinence of specialty therapies and bundled payment models is supporting market growth. Moreover, the shift toward patient-centric care is encouraging providers to move from hospital systems to independent or integrated clinic-based models, contributing to market growth.
How is Artificial Intelligence Transforming the Ambulatory Infusion Centers Market?
Artificial intelligence may support operational improvements in ambulatory infusion centers through scheduling, workflow automation, and patient monitoring., leaner, and more patient-centric care. AI-powered operations reduce patient wait times, optimize chair time scheduling, and improve nursing productivity through real-time analytics. AI-enabled scheduling, clinical decision support, and remote monitoring may help infusion providers improve operational efficiency and patient oversight, allowing ambulatory infusion centers to provide advanced therapy practices outside the walls of the hospital. Fully integrated AI systems also increase administrative efficiency by automating several tasks, such as scheduling appointments, managing patient records, and handling billing processes. This automation frees up staff to focus on patient care. AI systems also optimize resource allocation, ensuring that ambulatory infusion centers meet patient needs.
What are the Growth Factors of the Ambulatory Infusion Centers Market?
- Increased Adoption of Biologic Drugs: Many biologics prescribed for chronic health conditions are administered intravenously, although some are delivered through subcutaneous or other routes. Ambulatory centers provide an ambulatory setting for these long-term biologic therapies as they are more convenient and cost-effective for the patients and their payers.
- Transition from Inpatient to Outpatient Care: There is a transition occurring among the health systems from inpatient to outpatient care in order to decrease costs and make the patient experience more streamlined. Ambulatory infusion centers support efficient delivery of non-acute infusion services.
- Increased Approvals of Specialty Drugs: Additional approvals of specialty drugs requiring infusion are increasing demand for specialized services delivered outside traditional hospital settings.
- Higher Incidence of Chronic Diseases: An increase in autoimmune disorders, oncological disorders, and neurological disorders are contributing to the need for long-term therapies or therapies, placing ambulatory infusion centers to be an integral element of where to delivered care, the populations, and behavior one can get when/where they want treatment.
Ambulatory Infusion Centers Market Outlook
- Industry Growth Overview: From 2025 to 2030, demand for ambulatory infusion center services is expected to benefit from the shift toward outpatient care, driven by rising demand for cost-effective outpatient care options, the increasing prevalence of chronic diseases, and patient preference for shorter hospital stays. Growth has been fueled largely by payers advancing infusion services into outpatient settings outside an inpatient, acute-care setting, as well as improved treatment protocols for oncology, immunology, and pain management.
- Global Expansion: Regional expansion opportunities depend on local demand for infusion services, reimbursement structures, healthcare infrastructure, and regulatory requirements. Major infusion companies were established to provide outpatient infusion suites next to specialty clinics and facilities providing diagnostic services.
- Major Investors: Private equity firms and healthcare investors quickly became involved in this market because of the high margins when compared to other health sectors, the repeat-visit models within infusion therapy, and the strong reimbursement outlook. Private equity investment in infusion services should be assessed using documented transactions, including the investor, target company, transaction date, and disclosed investment details. Investors seemed particularly interested in infusion centers with scalable technologies, strong regulatory compliance, and relationships with large hospital systems.
- Startup Ecosystem: Potential areas of innovation include appointment scheduling, infusion workflow management, medication preparation, and patient monitoring, such as AI-based scheduling, remote monitoring for reactions to infusion, and safer dilution or mixing solutions. Newer companies are integrating home-to-center, automated pharmacy compounding, and better patient tracking platforms.
Market Dynamics
Drivers
How the Growth of Ambulatory Infusion Centers is Driven by a Rise in Chronic Disease Prevalence
The increasing prevalence of chronic and autoimmune diseases, specifically cancer, rheumatoid arthritis, Crohn's disease, and multiple sclerosis, is certainly a major driver of the ambulatory infusion centers market. According to the World Health Organization, noncommunicable diseases account for approximately 74% of deaths worldwide, and there is an increasing number of patients who require consistent intravenous treatments. Ambulatory infusion centers provide a non-hospital, cost-effective alternative to administering biologics, antibiotics, hydration, and nutritional therapy. (Source: https://www.who.int)
This ultimately reduces hospital admissions and allows patients to continue outpatient therapy instead of an inpatient setting. Demand for continuous outpatient care may support the role of infusion centers in managing chronic conditions.
Restraint
Limited Reimbursement
One of the most prevalent restraints for the ambulatory infusion centers market is the inconsistency and limitations of insurance reimbursement. There are many outpatient infusion therapies, especially the more expensive biologics used to treat autoimmune and chronic diseases, that are not uniformly covered by either private payers or government programs. The variability in reimbursement rates, pre-authorization, and fluidity of insurance policies create financial uncertainty for providers. Some infusion centers limit the types of therapies they can provide, directly impacting patient access to appropriate services, as too great a financial investment could put them at a loss.
Additionally, even patients with insurance coverage may find high out-of-pocket expenses dissuading them from continuing long-term therapies, and from their perspective, these expenses are simply unacceptable. Medicare coverage and payment requirements vary by service, care setting, and applicable policy. Insurance reimbursement and coverage restrictions can limit infusion centers' ability to expand services and reach more patients.
Opportunity
Expansion of Services
One emerging opportunity in the ambulatory infusion center space stems from the expansion of service offerings to include a broader range of infusion therapies and a shift in public and private payer policies that promote site-of-care optimization. Payers, including the Centers for Medicare & Medicaid Services (CMS), continue to promote alternative sites of care, moving infusion services out of hospital outpatient departments to lower-cost, higher-quality options, such as physicians' offices and free-standing infusion centers. CMS publishes coverage and payment requirements for eligible home infusion therapy services. Cite the applicable 2025 CMS rule or payment document before claiming that the benefit expanded or reimbursement increased.
(Source: https://www.cms.gov)
Some commercial health plans use site-of-care policies that direct eligible infusion treatments to alternative settings. Cite current UnitedHealthcare or Aetna policies for any payer-specific coverage restrictions. The reimbursement environment creates favorable opportunities and contributes to the financial sustainability of independent or physician-mixed infusion centers, resulting in an influx of new openings in unserved suburban and rural markets.
Segments Insights
Therapy Type Insights
Why Did the Biological Therapy Segment Dominate the Market in 2026?
The biological therapy segment dominated the ambulatory infusion centers market with the largest share in 2026. This is due to the increased number of cases of autoimmune and chronic inflammatory diseases, including rheumatoid arthritis and Crohn's disease. Biologics (most commonly monoclonal antibodies or cytokine inhibitors) require dosing and monitoring, making infusion centers an attractive option for their administration. Combined with the high treatment frequency and long duration of treatment, this will continue to be an area of growth for infusion centers and outpatient specialty pharmacies.
The immunoglobulin therapy (IVIG) segment is expected to grow at the fastest rate in the coming years because of the increased number of diagnoses of immunodeficiency disorders and also the increasing prevalence of neurological disorders, including chronic inflammatory demyelinating polyneuropathy (CIDP). The increased demand for more targeted and specialty infusion treatments in ambulatory centers is contributing to this growth. Similarly, the increase in the elderly population and increased off-label use of IVIG for autoimmune disorders are helping increase the use of IVIG in outpatient settings.
Application Insights
Which Application Segment Dominated the Market in 2026?
The autoimmune disorders segment dominated the ambulatory infusion centers market in 2026. This is mainly due to the increased number of cases of rheumatoid arthritis, psoriasis, and Crohn's disease. These diseases require long-term infusion-based biologic therapy. Ambulatory infusion centers provide a far more comfortable and cost-efficient alternative to inpatient care. The additional increase in the number of autoimmune conditions and new diagnoses, in addition to the increasing number of patients receiving access to more complex biologics, continues to support this dominant application segment.
The oncology segment is expected to expand at the fastest CAGR during the forecast period. The growth of the segment is attributed to the increasing transition of cancer care from the inpatient to the outpatient environment. Ambulatory infusion centers offer the ability to administer safe and effective oncology therapies in a far more cost-effective and convenient manner than a hospital or inpatient care setting. The increasing incidence of cancer and new infusion-based immunotherapies will further bolster this trend.
End User Insights
How Does the Standalone/Independent Infusion Centers Segment Dominate the Ambulatory Infusion Centers Market in 2026?
The standalone/independent infusion centers segment dominated the market while holding the largest share in 2026, due to their flexibility, longer hours of operation, and patient-centric nature. Patient-centered infusion services attract a broad mix of patient types with chronic conditions who may need regular infusions. Compared to hospital centers, patients experience shorter wait times and enjoy low-cost, high-quality infusion services, which improve their overall satisfaction levels.
Physician office infusion centers (POICs) are the fastest-growing end-user segment. POICs are gaining traction by integrating infusion services into their practices to support continuity of care. POICs particularly benefit chronic disease patients by providing them with convenience, personalized treatment plans, and immediate access to a physician for medical supervision. Improvements in reimbursement and the demand for in-office services have prompted additional physicians to expand their infusion capabilities.
Payor Type Insights
Why Did the Commercial Insurance Segment Dominate the Ambulatory Infusion Centers Market in 2026?
Commercial insurance is the most dominant payor because employer coverage often includes extensive benefits that facilitate chronic condition management, as well as the fact that the majority of these plans will result in more expedited approvals and wider access to high-cost biologics and infusion therapies for patients. Commercial insurance tends to provide infusion centers with better reimbursement, thus creating more incentive for the infusion center to prefer these prospects.
The Medicare segment is expected to expand at the fastest rate in the upcoming period, driven by an aging and chronically ill population of seniors. Older adults often require infusion services for their arthritis, cancer, and immune disorders at an increasing pace. Medicare infusion services are on the rise. Policy revisions to boost reimbursement rates for outpatient services have enhanced the ability of Medicare patients to receive treatment at community-based ambulatory infusion centers.
Regional Insights
What Made North America the Dominant Region in the Ambulatory Infusion Centers Market in 2026?
North America dominated the market by capturing a 58% share in 2026. This is mainly due to solid Medicare reimbursement support and an established outpatient system in place. The Centers for Medicare and Medicaid Services (CMS) allows "incident to" billing under Place of Service 11, which allows AICs to bill Medicare an infusion fee for the administration of infusion drugs. CMS publishes home infusion therapy payment files and applicable updates. Cite the specific 2025 file before stating the revision date or asserting that rates and geographic adjustments remained unchanged. There is a high demand for outpatient services, supporting regional market growth.
What is the U.S. Ambulatory Infusion Centers Market Size?
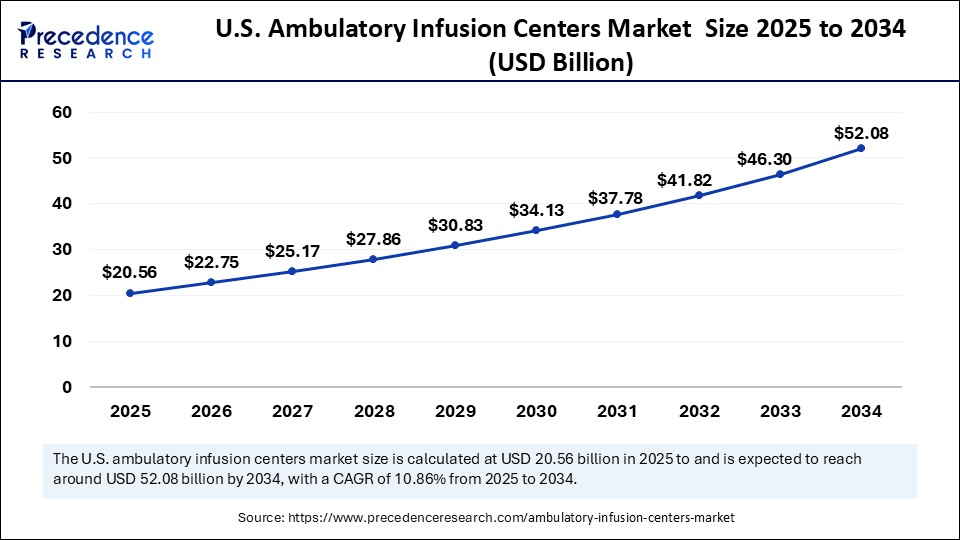
The U.S. ambulatory infusion centers market size is evaluated at USD 22.75 billion in 2026 and is projected to be worth around USD 56.99 billion by 2035, growing at a CAGR of approximately 10.74% from 2026 to 2035.
U.S. Ambulatory Infusion Centers Market Trends
The U.S. is a major player in the market in North America. Healthcare providers in the country are increasingly moving infusion services from hospitals to ambulatory settings to reduce hospital congestion. The 2025 Medicare Physician Fee Schedule established payment policies for eligible physician services. Cite the specific provision relevant to infusion services before claiming that it improved reimbursement. This outpatient infusion reimbursement parity between outpatient departments and private infusion centers represents significant opportunities for AIC growth across the U.S.
Asia Pacific: The Fastest-Growing Region
Asia Pacific is expected to experience the fastest growth in the coming years due to rising healthcare policies and outpatient coverage. In September 2023, the National Healthcare Security Administration (NHSA) of China stated that 99% of outpatient institutions were included in the integrated medical reimbursement system, which processed ¥124?billion in outpatient reimbursements through employer-employee insurance coverage. The changes will ultimately allow outpatient clinics, inclusive of AICs, to provide affordable chronic and specialty care outside hospital settings. (Source: https://govt.chinadaily.com.cn)
China Ambulatory Infusion Centers Market Trends
In China, infusion services are shifting away from tertiary hospitals and are being located in community and district-level clinics. Outpatient infusion service models in China should be described using a cited government policy or documented provider examples, hospital-third-party partnerships, and pharmacy-based centers, all of which require emergency readiness and adequately trained staff. As chronic diseases and patients' access to insurance coverage increase, China's infusion service system can evolve into a safer and more accessible system for outpatient service implementation.
Europe: The Second-Largest Region in the Ambulatory Infusion Centers Market
Europe is the second largest market due to its strong healthcare delivery network, an elderly population with the accompanying burden of chronic disease, and a growing demand for outpatient rather than inpatient treatment. Like other countries, Germany, France, and the UK are moving many treatments and therapies from inpatient to outpatient to contain costs and increase access and patient comfort in receiving care wherever possible. The infusion center market is growing due to supportive reimbursement and government-funded home-based infusion therapy service initiatives, expanding infusion "ownership" and therapy treatment options in the region.
Germany Ambulatory Infusion Centers Market Trends
Germany is an important European market for outpatient infusion services, partly due to a strong healthcare delivery system, comprehensive insurance coverage, and highly accessible care from and among physicians, which has led to the rapid adoption of outpatient infusion therapy. Additionally, Germany has seen an increase in daycare treatment models, a diminished burden on hospitals, and reduced wait times for chronic care patients.
What made Latin America Grow at a Steady Pace in the Ambulatory Infusion Centers Market?
Demand for outpatient infusion services in Latin America may be influenced by chronic disease prevalence, specialty drug access, reimbursement, and healthcare infrastructure. Countries in the region expanded their infusion offerings to relieve hospital crowds. The market enjoyed benefits from growing cancers and more access to specialty drugs. Moreover, private hospitals and clinics opened new infusion suites in urban areas. Mobile infusion services, telehealth referrals, and partnering with global pharma to support entering the region represented opportunities.
Brazil Ambulatory Infusion Centers Market Trends
Brazil had led the region due to its population and growing private health sector. Many hospitals had renovated their outpatient units to accommodate the growing demand for oncological and immune-related infusions.Private-sector expansion and insurance coverage may influence access to outpatient infusion services in Brazil. Digital health tools improved coordination of care, too.
What made the Middle East & Africa region Grow at a Significant Rate in the Ambulatory Infusion Centers Market?
Healthcare infrastructure investment and specialty care expansion may create opportunities for outpatient infusion services in the Middle East and Africa. The increase in cases of cancer and autoimmune conditions has created a strong demand for infusion services. In addition, governments had endorsed outpatient care as a way to limit hospital expenditures. Similar to the outpatient care trends, private hospitals have invested in outpatient infusion suites, particularly in the Gulf region. There is still a strong opportunity to develop telehealth support, international care partnerships, and increase the care footprint in underdeveloped regions.
The UAE Ambulatory Infusion Centers Market Trends
The UAE's healthcare infrastructure, insurance arrangements, and access to specialty therapies may support demand for outpatient infusion services. Private hospitals had invested in modern outpatient infusion centers focused on patients with cancer, immune disorders, and pain management. Additionally, medical tourism has led to greater demand for infusion services. Furthermore, the region had invested in digital systems and developed automated drug preparation systems to improve safety and care.
Key Companies in the Ambulatory Infusion Centers Market
- Option Care Health: Home and alternate-site infusion services with customized nursing support and care coordination services by a U.S. provider of home and alternate-site infusion services.
- InfuCare Rx: Specialty infusion pharmacy company providing data-driven, digital care solutions for chronic and complex care efficiently.
- Coram, CVS: Health care provider that provides specialty home infusion and ambulatory suite services, clinical monitoring, and patient counseling support.
- KabaFusion: Physician-led infusion therapy company with a focus on IVIG and SCIG products for immune deficiencies and chronic neurological diseases.
- Amerita: Specialized ambulatory infusion clinic operator that delivers nurse-led complex, high-touch infusion therapy treatments and patient services.
Other Major Key Players
- United Infusion
- Soleo Health
- Paragon Healthcare
- PromptCare
- ContinuumRx
- CareCentrix
- Chartwell Pennsylvania
- Intramed Plus
- AlayaCare
- ClearSky Health
- Healix Infusion Therapy
- Nufactor (a FFF Enterprises company)
- PharMerica Infusion Services
- Infusion Associates
Recent Developments
- In May 2026, Pure Infusion launched from the merger of AleraCare and Pure Healthcare, uniting established infusion clinics to simplify care and enhance patient experience. The company focuses on improving healthcare outcomes and reducing costs for patients with chronic conditions through a shared commitment to quality. (Source: https://www.businesswire.com)
- In April 2026, Soleo Health opened a new ambulatory infusion center in Louisville, Kentucky, enhancing access to specialized infusion care and demonstrating its commitment to the local community's needs. (Source: https://www.globenewswire.com)
- In November 2025, AleraCare and Pure Healthcare announced the completion of their merger, combining AleraCare's infusion and specialty pharmacy services with Pure Healthcare's expertise in managing complex chronic conditions like rheumatoid arthritis and multiple sclerosis.
- In October 2025, Sutter Lakeside Hospital launched onsite infusion services, enhancing access to advanced cancer care in Lake County. This initiative is part of Sutter's Rural Oncology Program, aimed at providing innovative treatments and coordinated care to rural communities, similar to metropolitan services.
- In January 2025, Optum, a UnitedHealth subsidiary, agreed to acquire FlexCare Infusion, a 30 location ambulatory infusion network across Alabama, Arizona, and Oklahoma, expanding outpatient infusion services amid growing antitrust scrutiny.
Ambulatory Infusion Centers Market Segments
By Therapy Type
- Anti-infective Therapy
- Hydration Therapy
- Chemotherapy
- Immunoglobulin Therapy
- Biological Therapy
- Enteral and Parenteral Nutrition
- Others (e.g., corticosteroids, pain management infusions)
By Application
- Oncology
- Autoimmune Disorders
- Rheumatoid Arthritis
- Multiple Sclerosis
- Crohn's Disease
- Psoriasis
- Neurological Disorders
- Infectious Diseases
- Gastrointestinal Disorders
- Immune Deficiencies
- Others
By End-User
- Hospital-Affiliated Infusion Centers
- Physician Office Infusion Centers (POICs)
- Standalone/Independent Infusion Centers
- Home Infusion Service Providers
By Payor Type
- Commercial Insurance
- Medicare
- Medicaid
- Out-of-Pocket / Self-Pay
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting