
Cell and Gene Therapy Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Competitive Positioning, and Demand Forecast
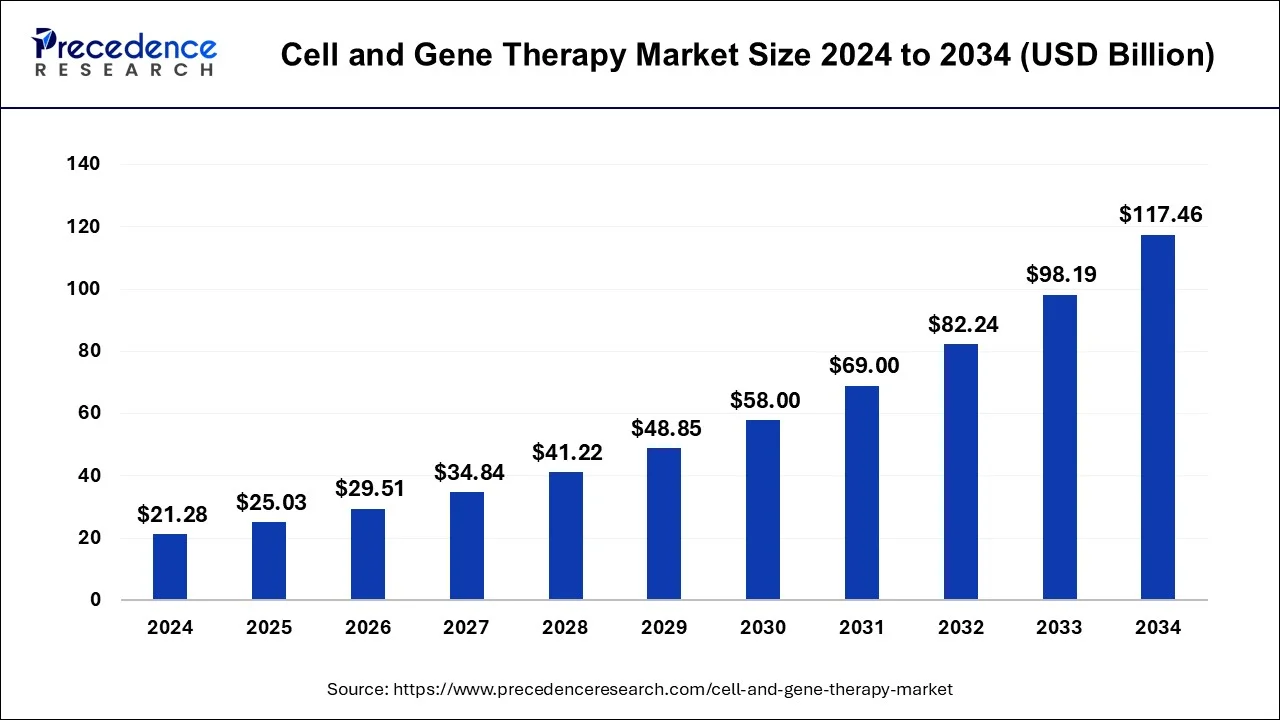
Deepa Pandey, a Healthcare Industry Expert, highlights that the cell and gene therapy market has reached USD 10.44 billion in 2026 and is on track to reach USD 47.18 billion by 2035, advancing at a CAGR of 17.60%. Key cell and gene therapy market companies shaping the market include Alnylam Pharmaceuticals Inc., Amgen Inc., Biogen Inc., while major growth segments span by therapy type, by indication / therapeutic area, by vector type, by manufacturing type, by end use, and region.
Source: https://www.precedenceresearch.com/cell-and-gene-therapy-market
 Get a Sample
 Table Of Content


What is the Cell and Gene Therapy Market Size?
The global cell and gene therapy market size was estimated at USD 8.94 billion in 2025 and is predicted to increase from USD 10.44 billion in 2026 to approximately USD 47.18 billion by 2035, expanding at a CAGR of 18.1% from 2026 to 2035.
Cell and Gene Therapy Market Key Takeaways
- In terms of revenue, the global cell and gene therapy market was valued at USD 8.94 billion in 2025.
- It is projected to reach USD 45.24 billion by 2035.
- The market is expected to grow at a CAGR of 17.60% from 2026 to 2035.
- North America region generated a revenue share of around 50.26% in 2025.
- By therapy type, the cell therapy segment led the market with a 65% share in 2025.
- By therapy type, the gene therapy segment held the second largest share of 35% in the market in 2025.
- By indication, the oncology segment led the market with a 39% share in 2025.
- By indication, the musculoskeletal/orthopedic disorders segment held the second largest share of 21% in the market in 2025.
- By vector type, the viral vectors segment led the market with a 72% share in 2025.
- By vector type, the non-viral vectors segment held the second largest share of 28% in the market in 2025.
- By manufacturing type, the in-house segment led the market with a 46% share in 2025.
- By manufacturing type, the contract development & manufacturing organizations (CDMOs) segment held the second largest share of 39% in the market in 2025.
- By end use, the hospitals & specialty clinics segment led the market with a 63% share in 2025.
- By end use, the cancer treatment centers segment held the second largest share of 24% in the market in 2025.
What is Cell and Gene Therapy Manufacturing?
Cell and gene therapies (CGTs) provide substantial advancements in patient care by treating or perhaps curing a variety of illnesses that have previously been untreatable by small molecules and biological medicines. The FDA in the United States has approved more than 20 CGTs during the past 20 years, and many of these one-time therapies range in price from $37,500 to $2 million per shot.
Given the significant financial investment involved and high patient expectations surrounding these life-saving therapies, it has become essential for manufacturers to offer integrated services across the entire supply chain. This approach helps ensure efficient biomanufacturing processes, smoother logistics, and fewer barriers to broader treatment adoption.
The continued expansion of the cell and gene therapy (CGT) market has been reflected in several high-profile mergers and acquisitions, including bluebird bio and BioMarin, Celgene and Juno Therapeutics, Gilead Sciences and Kite, Novartis and AveXis alongside CDMO CELLforCURE, Roche and Spark Therapeutics, and Smith & Nephew and Osiris Therapeutics.
Many biopharmaceutical companies have significantly reinvested in research and development, focusing on standardizing vector manufacturing and purification processes, adopting forward engineering approaches in cell therapy development, improving cryopreservation techniques for cellular samples, and exploring the development of off-the-shelf allogeneic cell therapy solutions.
To strengthen manufacturing capabilities, pharmaceutical companies are increasingly evaluating their internal production capacity, choosing either to invest in proprietary manufacturing facilities or to partner with contract development and manufacturing organizations (CDMOs) and contract manufacturing organizations (CMOs).
At the same time, limited funding, infrastructure, and production capacity are prompting smaller biotech companies to develop cell and gene therapies to pursue strategic partnerships with contract manufacturers. This trend continues to drive meaningful growth within the CGT market, further reinforced by the substantial rise in investment flowing into this space.
How is AI contributing to the Cell and Gene Therapy Manufacturing Industry?
Artificial intelligence is playing an increasingly important role in improving cell and gene therapy manufacturing by accelerating development timelines and helping stabilize complex production conditions. By leveraging real-time manufacturing data, AI helps optimize process conditions while enhancing overall consistency through predictive, anticipatory learning models. Additionally, AI enables early prediction of potential equipment failures well before they occur, while also supporting smoother, more efficient production scale-ups across manufacturing operations.
Market Outlook
- Industry Growth Overview: Clinical momentum keeps the industry growing. Automation enhances effectiveness throughout manufacturing settings.
- Global Expansion: Infrastructure is being expanded in Germany, the UK, and Canada to supply regional manufacturing requirements.
- Major investors: Thermo Fisher Scientific, Lonza Group, Catalent, WuXi AppTec, Fujifilm Holdings, increased capacity and technologies.
Market Scope
| Report Coverage | Details |
| Market Size by 2035 | USD 47.18 Billion |
| Market Size in 2025 | USD 8.94 Billion |
| Market Size in 2026 | USD 10.44 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 18.1% |
| Largest Market | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | By Therapy Type, By Indication, By Vector Type, By Manufacturing Type, By End Use, and Region |
| Regions Covered | Asia Pacific, North America, Europe, Latin America, Middle East and Africa |
Market Dynamics
Drivers
The COVID-19 pandemic initially disrupted market growth through restrictive containment measures, including social distancing, remote work, and the temporary closure of commercial operations, all of which created significant operational challenges across the industry. As companies gradually resumed operations and adapted to the evolving business environment, the market began to recover and regain momentum.
Since then, growth has been primarily driven by an expanding clinical pipeline and a rising number of regulatory approvals for innovative cell and gene therapies. Market participants continue to strengthen their industry presence, recognizing significant growth potential within the contract development of cellular and gene-modified medicines. Many biopharmaceutical companies are forming strategic partnerships with contract manufacturers to accelerate research and development timelines for their therapeutic candidates. The entry of new competitors, combined with expanding product development capabilities driven by rising demand for CMO and CDMO services, has further contributed positively to overall market revenue.
Several innovative techniques are also being introduced to advance cell and gene therapy production. For example, manufacturers are increasingly exploring single-use technologies within production workflows, an approach gaining popularity for its ability to accelerate development timelines while reducing both costs and production time. Continued technological innovation in this space is expected to support sustained market growth in the years ahead.
Rising demand for advanced cell and gene therapies continues to intensify competition among market participants. Cell therapy manufacturers and CDMOs are increasingly entering strategic agreements to accelerate product development and strengthen their competitive positioning. Ongoing clinical research activity continues to drive revenue growth within the contract manufacturing segment, further supported by the growing trend of outsourcing cell and gene therapy manufacturing processes.
Restraints
The development of cell and gene therapies continues to face significant challenges, including ongoing concerns around safety and efficacy, lengthy clinical trial protocols, stringent regulatory requirements, and high treatment costs. Key technical considerations shaping successful therapy development include the ability to simultaneously target heterogeneous cell systems, achieving high gene transfer efficiency, minimizing cell toxicity, and ensuring precise single-cell specificity toward the intended therapeutic target.
While several CAR T-cell therapies have received regulatory approval, manufacturing capacity constraints remain a critical challenge. According to Dr. Krina Patel, director of the myeloma cell therapy program at MD Anderson Cancer Center, approximately 20 percent of eligible cancer patients die while waiting for an available production slot. That said, manufacturing timelines have improved considerably in recent years, with some autologous CAR T-cell products now produced in under two weeks, compared to roughly a month earlier years.
Opportunities
A number of gene treatments have received approval, mostly for the treatment of rare diseases Numerous businesses, including Astellas Gene Therapies, Bayer, ArrowHead Pharmaceuticals, Bluebird Bio, Intellia Therapeutics, Krystal Biotech, MeiraGTx, Regenxbio, Roche, Rocket Pharmaceuticals, Sangamo Therapeutics, Vertex Pharmaceuticals, Verve Therapeutics, and Voyager Therapeutics, are researching novel gene therapy vectors to boost levels of gene expression/protein production, decrease immunogenicity, and improve durability.
Segments Insights
Therapy Type Insights
The Cell Therapy Segment Dominated the Cell and Gene Therapy Market in 2025 With A 65% Share
The cell therapy segment dominated the market with a 65% share in 2025. Growing focus on treating blood cancers, combined with the rising prevalence of autoimmune disorders, continues to drive strong demand for cell therapy. Increased investment in cell therapy manufacturing, along with the growing need for structural tissue repair, is further accelerating adoption across the segment. Additionally, the expanding use of stem cell therapies and consistently strong clinical outcomes continue to support overall segment growth.
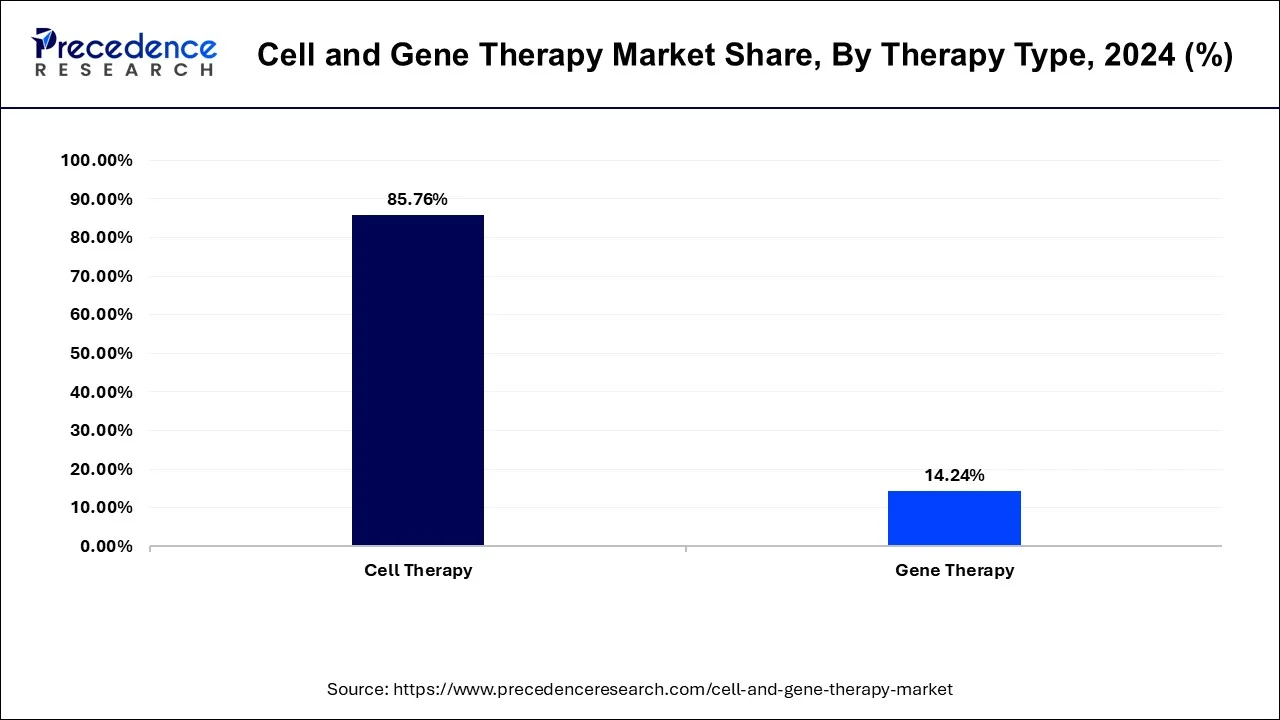
The gene therapy segment held the second largest share of 35% in the market in 2025. The rising incidence of rare genetic disorders, along with the growing use of in vivo treatment approaches, continues to drive the adoption of gene therapy. The persistent burden of previously untreatable genetic conditions, combined with expanding collaborative partnerships across the industry, is further supporting market expansion. Continued advancements in gene editing technologies are also playing a key role in reinforcing long-term growth within the gene therapy segment.
Cell and Gene Therapy Market By Therapy Type, 2022-2024 (USD Million)
| Therapy Type | 2023 | 2024 | 2025 |
| Cell Therapy | 4,454.4 | 5,061.6 | 5,792.7 |
| Gene Therapy | 2,381.3 | 2,728.7 | 3,149.1 |
Indication Insights
The Oncology Segment Dominated The Cell and Gene Therapy Market In 2025 With A 39% Share
The oncology segment dominated the market with a 39% share in 2025. The growing number of cancer patients and the expansion of autologous therapies is increasing the adoption rate of cell and gene therapy. Targeted personalization and the high incidence of hematological cancers continue to drive the use of cell and gene therapy. Substantial R&D investment and rapid innovation in CAR-T treatments are fueling growth within this segment.
The musculoskeletal/orthopedic disorders segment held the second largest share of 21% in the market in 2025. The widening treatment gap in orthopedic disorders and continued innovation in iPSCs are increasing the adoption of cell and gene therapy. Growing focus on soft tissue repair and the treatment of non-union fractures is further increasing the use of cell and gene therapy. The rising prevalence of age-related orthopedic disorders continues to support segment growth.
The genetic disorders segment held the third largest share of 12% in the market in 2025. The growing prevalence of sickle cell anemia and advances in genomic understanding are increasing the adoption of cell and gene therapy. The development of customized genetic disorder therapies is supporting market expansion. Ongoing innovations in gene editing, along with rising diagnosis rates of genetic disorders, continue to boost segment growth.
Vector Type Insights
The Viral Vectors Segment Dominated the Cell and Gene Therapy Market In 2025 With A 72% Share
The viral vectors segment dominated the market with a 72% share in 2025. The growing use of in-vivo gene delivery and the increasing need to deliver therapeutic genes are driving the adoption of viral vectors. Rising use of cancer immunotherapy and the growing modification of ex vivo cells are further increasing demand for viral vectors. High efficacy, stable clinical pipeline, and targeted delivery capabilities continue to drive growth within this segment.
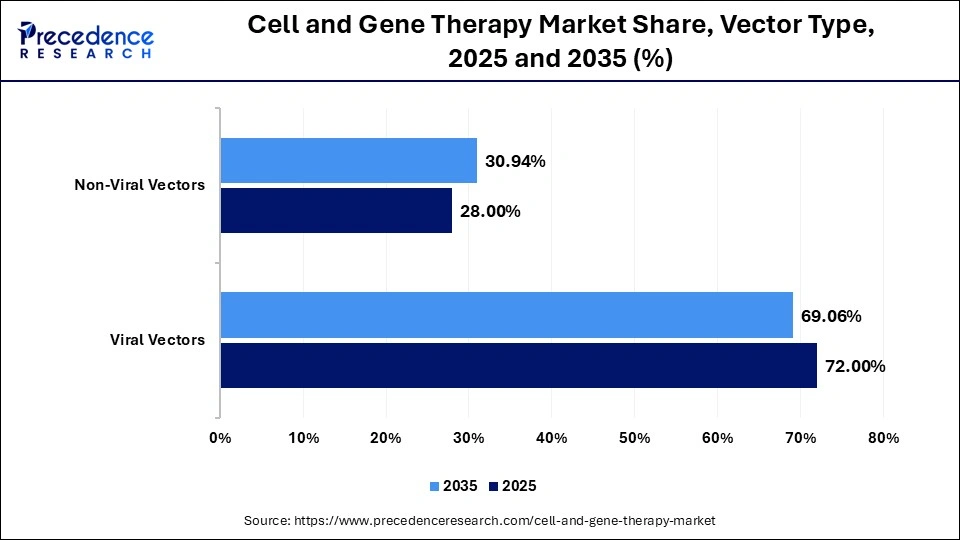
The non-viral vectors segment held the second largest share of 28% in the market in 2025. The increased development of CRISPR genome editing, along with the larger genetic cargo capacity offered by non-viral vectors, is driving their adoption. The rapid growth of mRNA technology is further supporting this expansion. Lower cost, superior safety, reduced immunogenicity, and lower toxicity continue to support growth within the non-viral vectors segment.
Manufacturing Type Insights
The In-House Segment Dominated the Cell and Gene Therapy Market in 2025 With A 46% Share
The in-house segment dominated the market with a 46% share in 2025. Rising sensitivity requirements in cell and gene therapy production, combined with a growing number of clinical trials, continue to fuel demand for in-house manufacturing capabilities. As proprietary CGT processes become more complex and commercial-scale production increases, more companies are turning to in-house manufacturing to maintain greater control. This approach offers valuable benefits, including operational flexibility, stronger cost control, and easier regulatory compliance, all of which continue to support growth within this segment.
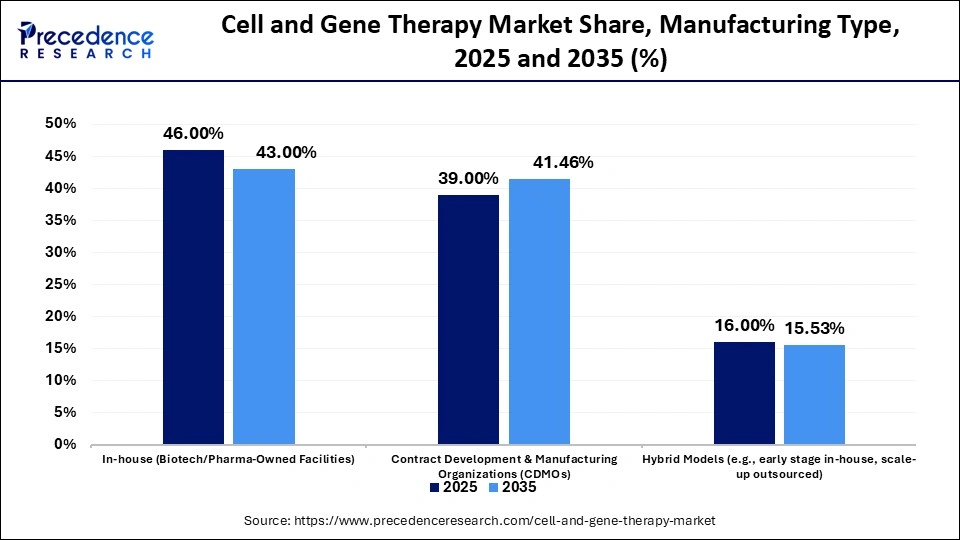
The contract development & manufacturing organizations (CDMOs) segment held the second largest share of 39% in the market in 2025. Demand for customized cell processing, along with the appeal of lower operational costs, is driving stronger adoption of CDMOs across the industry. This growth is further reinforced by the expanding CGT pipeline and the increasing need for specialized cell therapy infrastructure that many companies cannot easily build in-house. Strengthening partnerships between biopharmaceutical companies and CDMOs continue to play a key role in accelerating growth within this segment.
The hybrid models segment held the third largest share of 16% in the market in 2025. Hybrid manufacturing models are also gaining traction, largely driven by the need to minimize transportation of fragile biological materials and achieve faster turnaround times. Growing pressure to reduce batch failures, along with rising interest in modular manufacturing approaches, is further accelerating adoption of these hybrid models. By offering better capacity balancing, improved logistics, and greater operational scalability, hybrid models continue to support meaningful growth across this segment.
End Use Insights
The Hospitality & Specialty Clinics Segment Dominated the Cell and Gene Therapy Market in 2025 With A 63% Share
The need for sterile treatment facilities in cell and gene therapy, along with the growing demand for targeted cancer care, continues to drive greater use of hospitals and specialty clinics. Rising Phase 3 clinical trial activity, combined with access to specialized storage infrastructure within these clinics, is further supporting segment expansion. Strong safety protocols, multidisciplinary clinical expertise, and specialized therapy administration continue to drive growth within this segment.
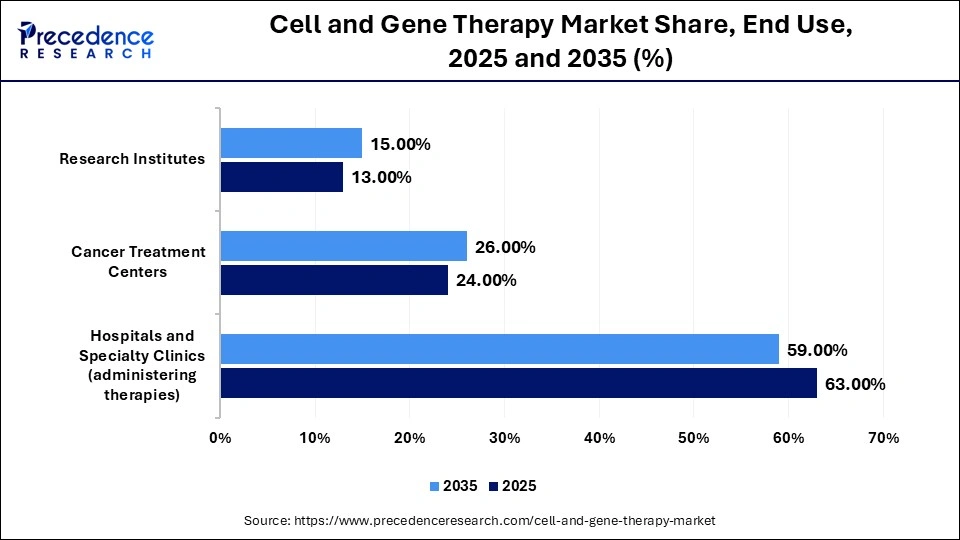
The cancer treatment centers segment held the second largest share of 24% in the market in 2025. The increased use of cell therapies for treating blood cancers, along with the expanding use of TIL (tumor-infiltrating lymphocyte) therapies, continues to drive greater use of dedicated cancer treatment centers. The growing emphasis on individualized genetic treatment profiles is further supporting this expansion. Strong demand for comprehensive therapeutic clinical testing continues to reinforce growth within this segment.
The research institutes segment held the third largest share of 13% in the market in 2025. Ongoing development of advanced delivery systems, along with an expanding therapeutic pipeline, continues to drive greater adoption of research institutes. Complex technical challenges, combined with the growing need for advanced therapy development, are further increasing reliance on research institutions. Substantial funding support and favorable regulatory frameworks continue to boost growth within this segment.
Cell and Gene Therapy Market By End Use, 2022-2024 (USD Million)
| By End Use | 2023 | 2024 | 2025 |
| Hospitals and Specialty Clinics (administering therapies) | 4,331.2 | 4,908.1 | 5,601.5 |
| Cancer Treatment Centers | 1,604.3 | 1,847.4 | 2,142.4 |
| Research Institutes | 900.2 | 1,034.8 | 1,197.9 |
Regional Insights
What is the U.S. Cell and Gene Therapy Market Size?
The U.S. cell and gene therapy market size was estimated at USD 4.74 billion in 2026 and is predicted to be worth around USD 20 billion by 2035, at a CAGR of 17.21% from 2026 to 2035.
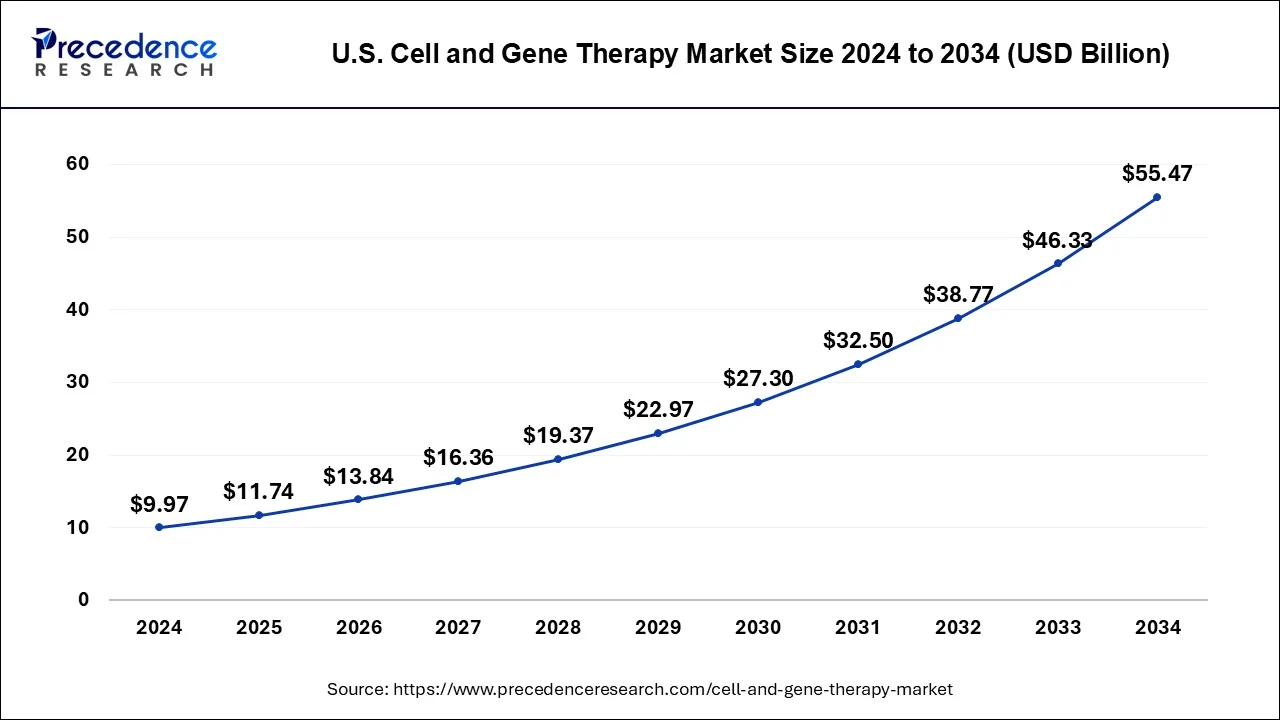
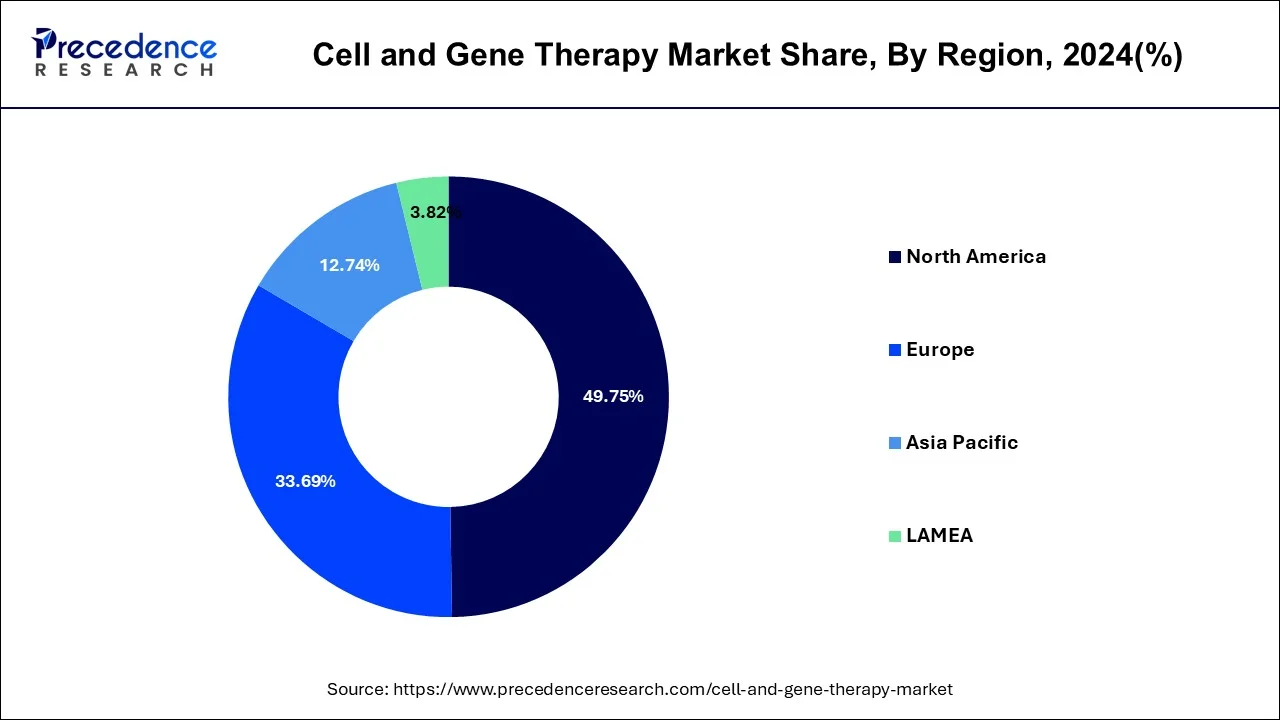
A significant number of ongoing clinical trials and a rise in corporate involvement in gene and cell therapy R&D are the primary drivers of regional market expansion. The North America region accounted for more than 50% of revenue share in 2025.
North America scored first for having the greatest number of gene therapy clinical trials, with more than 400 enterprises in the region actively engaged in the development of cell and gene therapy products for a variety of disorders.
Numerous brand-new collaborative research and innovation initiatives have been launched across Europe under the Horizon 2021 initiative. One of these endeavors is testing gene therapy utilizing viral vectors. This is expected to accelerate the growth of cell and gene therapy manufacturing services across Europe. The rise of the market is anticipated to be aided by the developed infrastructure and skilled labor force in European countries.
Value Chain Analysis of the Cell and Gene Therapy Manufacturing Market
- R&D: The effective identification of therapeutic targets and the development of viral vectors or cellular modification targeting a particular genetic disorder.
Key players: Novartis, Gilead (Kite Pharma), CRISPR Therapeutics - Clinical Trials and Regulatory Approvals: Therapies that are tested in humans and are shown to be safe and gain approval from authorities such as the FDA or EMA.
Key players: IQVIA, Charles River Laboratories - Packaging and Serialization: To make sure that items are kept in temperature-controlled packaging marked with labels that do not allow counterfeiting but allow tracking of items in supply chains.
Key players: Marken (UPS), Cryoport Systems, Almac
Cell and Gene Therapy Market Companies
- Merck KGaA: Provides bioprocessing equipment, specialized culture media, and viral vectors services that assist in the stable production of therapies in a variety of manufacturing settings.
- Novartis AG: Global manufacturing system for manufacturing CAR-T products and gene therapies based on automated bioreactor systems to supply in large quantities on a commercial basis.
Other Major Key Players
- Alnylam Pharmaceuticals Inc.
- Amgen Inc.
- Biogen Inc.
- CORESTEM Inc.
- Dendreon Pharmaceuticals LLC.
- Helixmith Co. Ltd.
- JCR Pharmaceuticals Co. Ltd.
- Kolon TissueGene Inc.
- Novartis AG
- Pfizer Inc.
Recent Developments
- In November 2025, BRIC-THSTI, in partnership with Miltenyi Biotec and BIRAC, launched India's inaugural hands-on training program on Cell and Gene Therapy Manufacturing. The program emphasizes CAR-T cell therapy techniques. (https://www.expresspharma.in )
- In November 2025, Bharat Biotech launched "Nucelion Therapeutics," a subsidiary in Hyderabad's Genome Valley. The subsidiary serves as a CRDMO for advanced cell and gene therapies, offering comprehensive solutions for global life science innovators. (https://www.gktoday.in )
- McKinsey will launch a new Digital Capability Center to quicken the development of cell and gene therapies (CGT). The Digital Capability Center will focus on accelerating operational excellence and digital transformations in biopharmaceutical manufacturing. The Digital Capability Center will join McKinsey's rapidly growing global network of Digital Capability Centers, immersive learning environments that inspire and prepare organizations to deliver sustainable performance improvement from operational-excellence and tech-enabled transformations.
- on october 3, 2022, Alexion's genomic medicines annuoced the acquisition of LogicBio's technology, by this acquiestuion they are looking to incorpate knowledgeable team for preclinical development, and team for research and development on rare diseases. LogicBio has developed a number of technical systems for the delivery and insertion of genes to address genetic disorders. Additionally, they will built a platform to improve the creation of viral vectors.
- On October 12, 2022, Moderna disclosed that Merck(MSD) has decided to exercise its $250 million option to co-develop and commercialize PCV mRNA-4157/V940. The vaccine is now being tested in a phase II clinical trial as adjuvant therapy for patients with high-risk melanoma in combination with pembrolizumab, Merck's programmed cell death protein 1 (PD-1) antibody.
- On October 3, 2022, Pfizer announced that they have successfully purchased Biohaven Pharmaceuticals which is a migraine drug manufacturing company. They recently manufactured NURTEC ODT (rimegepant) which is approved for both acute therapy and episodic migraine prevention in adults. With Pfizer's global reach and this acquisition, they will be able to provide migraine patients with more treatment alternatives.
Segments Covered in the Report
By Therapy Type
- Cell Therapy
- Stem Cell Therapy
- Hematopoietic Stem Cells (HSC)
- Mesenchymal Stem Cells (MSC)
- Induced Pluripotent Stem Cells (iPSC)
- Immune Cell Therapy
- CAR-T Cell Therapy
- TCR (T-cell Receptor) Therapy – targets intracellular antigens
- TIL (Tumor Infiltrating Lymphocyte) Therapy
- NK (Natural Killer) Cell Therapy
- Macrophage Therapies
- Dendritic Cell Therapy
- Others
- Stem Cell Therapy
- Gene Therapy
- In-vivo Gene Therapy
- Ex-vivo Gene Therapy
By Indication / Therapeutic Area
- Oncology
- Hematologic Malignancies
- Acute Lymphoblastic Leukemia (ALL)
- Non-Hodgkin Lymphoma (NHL)
- Chronic Lymphocytic Leukemia (CLL)
- Solid Tumors
- Glioblastoma
- Pancreatic Cancer
- Melanoma
- Prostate, Breast, Lung Cancer
- Others
- Head and Neck cancer
- Sarcomas
- Ovarian cancer (with experimental CGT trials)
- Hematologic Malignancies
- Genetic Disorders
- Hemophilia A and B
- Spinal Muscular Atrophy (SMA)
- Duchenne Muscular Dystrophy (DMD)
- Beta-thalassemia
- Sickle Cell Disease
- X-linked Adrenoleukodystrophy (X-ALD)
- Others
- Neurological Disorders
- Parkinson's Disease
- Alzheimer's Disease
- Batten Disease
- Huntington's Disease
- ALS (Amyotrophic Lateral Sclerosis)
- Others
- Cardiovascular Diseases
- Heart Failure
- Myocardial Infarction
- Peripheral Artery Disease
- Critical Limb Ischemia
- Others
- Ophthalmology
- Musculoskeletal / Orthopedic Disorders
- Infectious Diseases
- Metabolic Disorders
- Others
By Vector Type (Gene Delivery Method)
- Viral Vectors
- Adeno-Associated Virus (AAV)
- Lentivirus
- Retrovirus
- Herpes Simplex Virus (HSV)
- Adenovirus
- Others
- Non-Viral Vectors
- Lipid Nanoparticles (LNPs)
- Naked DNA/RNA Plasmids
- Electroporation
- Gene gun / microinjection
- CRISPR-Cas Delivery Systems (non-viral)
- Others
By Manufacturing Type
- In-house (Biotech/Pharma-Owned Facilities)
- Contract Development & Manufacturing Organizations (CDMOs)
- Hybrid Models (e.g., early stage in-house, scale-up outsourced)
By End Use
- Hospitals and Specialty Clinics (administering therapies)
- Cancer Treatment Centers
- Research Institutes
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- MEA
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
.webp)
 sales@precedenceresearch.com
 Schedule a Meeting