
CAR T-Cell Therapy Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Competitive Positioning, and Demand Forecast
Deepa Pandey, a healthcare industry expert, highlights that the CAR T-cell therapy market has reached USD 6,083.47 million in 2026 and is on track to reach USD 26,982.30 million by 2035, advancing at a CAGR of 17.88%. Key CAR T-cell therapy market companies shaping the market include ALLOGENE THERAPEUTICS, Lonza, Aurora Biopharma, while major growth segments span by target antigen, by indication / disease type, by type of therapy, by technology / vector used, by manufacturing/delivery method, by end user and region.
Source: https://www.precedenceresearch.com/car-t-cell-therapy-market
 Get a Sample
 Table Of Content


What is the CAR T-Cell Therapy Market Size?
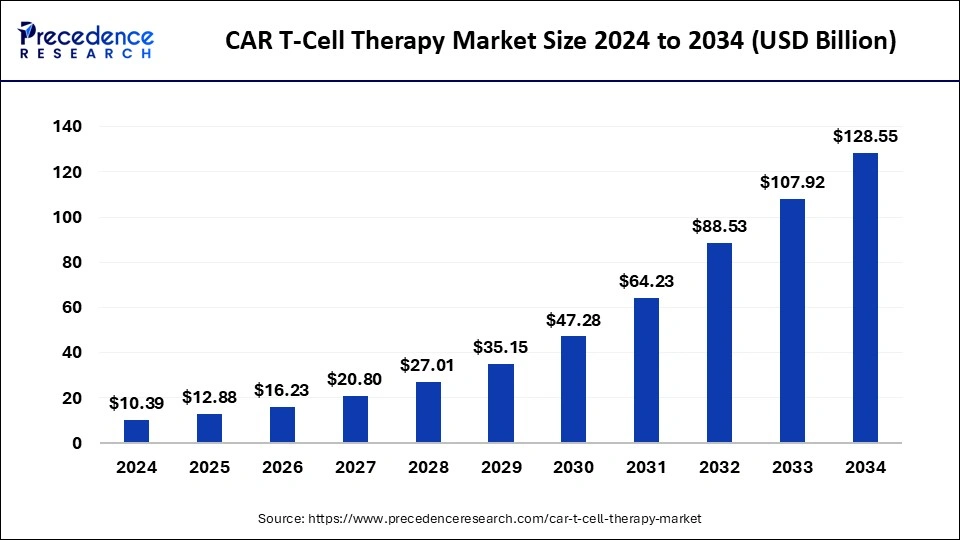
The global CAR T-cell therapy market size is calculated at USD 5,206.15 million in 2025 and is predicted to increase from USD 6,083.47 million in 2026 to approximately USD 26,982.30 million by 2035, expanding at a CAGR of 17.88% from 2026 to 2035. This CAR T-cell therapy market growth is being driven by the rising prevalence of cancer, growing demand for personalized medicine, and a steady stream of FDA approvals for new therapies.
CAR T-Cell Therapy Market Key Takeaways
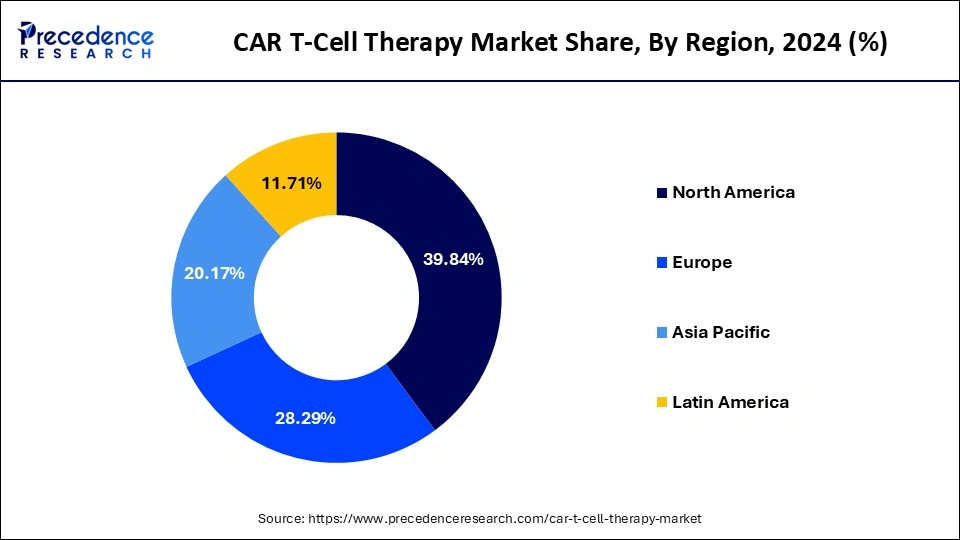
- North America dominates the market with a revenue share of 48.99% in 2025.
- Asia Pacific is expected to grow at the fastest CAGR of 20.36% from 2026 to 2035.
- By target antigen, the CD19 segment led the market share of 62.57% in 2025.
- By target antigen, the BCMA (B-cell maturation antigen) segment is expected to grow at a significant CAGR of 24.17% from 2026 to 2035.
- By indication/disease, the hematologic malignancies segment captured the largest market share of 93.85% in 2025.
- By indication/disease, the solid tumors segment is anticipated to grow at a significant CAGR of 23.66% from 2026 to 2035.
- By type of therapy, the autologous CAR-T cell therapy segment held the biggest market share of 81.1% in 2025.
- By type of therapy, the allogeneic CAR-T cell therapy segment is expanding at a significant CAGR of 23.21% from 2026 to 2035.
- By technology/vector, the viral vectors segment dominated the market with the largest share of 65.5% in 2025.
- By manufacturing method, the centralized manufacturing segment led the market with a major market share of 53.3% in 2024.
- By manufacturing method, the in vivo car t therapy segment is expected to grow at a significant CAGR of 24.92% over the projected period.
- By end user, the hospitals segment held a significant market share of 44.0% in 2025.
What is CAR T-Cell Therapy?
Chimeric antigen receptor (CAR) T-cell therapy is an advanced treatment currently used for certain hematological cancers, including acute lymphoblastic leukemia (ALL), adult and pediatric diffuse large B-cell lymphoma (DLBCL), multiple myeloma (MM), and mantle cell lymphoma (MCL). The therapy works by targeting specific antigens present on the surface of blood cancer cells, and the rising global incidence of cancer is expected to further accelerate development of CAR T-cell therapies for therapeutic use.
AI Integration in the CAR T-cell Therapy Market?
Artificial intelligence is transforming how CAR T-cell treatment is delivered, improving both efficacy and accuracy. AI in CAR T-cell therapy also supports real-time patient monitoring, including through smart wearable devices paired with the Internet of Things, allowing clinicians to track the treatment process and intervene quickly if complications arise.
Automation powered by AI is also optimizing the CAR T-cell production process, improving consistency, accuracy, and manufacturing scale. This reduces the likelihood of human error, lowers costs, and helps expand access to AI-driven cell manufacturing more broadly.
What Factors Are Fueling the Rapid Expansion of the CAR T-cell Therapy Market?
- Rising Cancer Cases: The rise in global cancer incidence is driving demand for better, more targeted treatment options. Given the limited effectiveness of traditional treatments in some cases, CAR T-cell products are increasingly used in both clinical and commercial practice, delivering stronger outcomes, particularly for hematologic malignancies.
- Diverse Applications: CAR T-cell therapy is no longer confined to oncology, with growing exploration into autoimmune and infectious disease applications. This ability to address multiple conditions adds significant value, strengthening the therapy position across the broader pharmaceutical sector.
- Increasing Research and Innovation: Ongoing research and innovation in CAR T-cell therapy continues to accelerate progress. Industry and academic institutions alike are developing new targets, improved safety profiles, and more efficient manufacturing processes. This R&D momentum is unlocking new treatment opportunities, building clinical pipelines, and strengthening the therapy's overall position in the global market.
CAR T-Cell Therapy Market Outlook
- Industry Growth Overview: The CAR T-cell therapy market outlook points to rapid growth between 2025 and 2030, supported by rising cancer cases, higher clinical success rates, and an expanding wave of regulatory approvals. Growth is further reinforced by clinical progress across both autologous and allogeneic cell therapy platforms, with momentum in North America, Europe, and Asia-Pacific.
- Sustainability Trends: Sustainable biomanufacturing is gaining wider focus across the CAR T-cell therapy market, with companies exploring more sustainable cell expansion methods through renewable media and closed-system production. Waste-reducing, more scalable approaches are gaining traction, reflected in ongoing advances in clean bioprocessing technologies and ethically sourced cell components.
- Global Expansion: Major biopharma companies are extending their reach into Asia-Pacific and European markets to tap local expertise, reduce therapy costs, and capture rising regional demand. Companies including Novartis and Gilead are expanding strategic partnerships and manufacturing operations to improve access across emerging oncology markets.
- Primary Investors: Venture capital and major pharmaceutical investment firms continue directing significant capital toward the CAR T industry, drawn by its high efficacy rates and strong, sustained profitability potential. Recent investment activity from organizations including Bain Capital and Pfizer's investment arm signals continued confidence in the next phase of immunotherapy development targeting solid tumors.
- Startup Ecosystem: The CAR T startup ecosystem is developing quickly, with innovative teams working on off-the-shelf (allogeneic CAR T-cell therapy) platforms and exploring AI-driven approaches to next-generation cell-line engineering. Emerging companies such as Cellectis and Arcellx are raising substantial funding to develop treatment options that are more scalable, safer, and more affordable.
Market Scope
| Report Coverage | Details |
| Market Size by 2035 | USD 26,982.30 Million |
| Market Size in 2025 | USD 5,206.15 Million |
| Market Size in 2026 | USD 6,083.47 Million |
| Growth Rate from 2026 to 2035 | CAGR of 17.88% |
| Dominated Region | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | Drug Type, Indication, End User, Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America and Middle East & Africa |
Market Dynamics
Opportunity
Growing Demand for Personalized Medicine
The healthcare landscape continues shifting toward more personalized medicine, and CAR T-cell therapy stands as a leading example of this precision approach. In this treatment, a patient's own T cells are genetically modified to identify and destroy cancer cells, offering a therapy customized to the individual. One of CAR T-cell therapy's central advantages is its ability to target cancer selectively without extensive systemic toxicity, reducing side effects and improving overall patient outcomes.
Advances in genomic sequencing, biomarker detection, and cell engineering technologies continue to expand the possibilities and success rates of this individualized approach. These scientific developments support more accurate patient selection and improved therapy design, ultimately driving higher success rates and a larger addressable patient population, further strengthening CAR T-cell therapy market opportunities.
Restraints
Side effects of CAR-T cell therapy
Like other cancer treatments, CAR T-cell therapies carry serious potential side effects, including significant depletion of antibody-producing B cells and increased infection risk. Cytokine release syndrome (CRS) stands among the most common and severe of these, occurring when T cells release chemical messengers called cytokines that stimulate and direct immune responses as part of their normal function.
In CRS, infused T cells flood the bloodstream with cytokines, which can trigger serious effects such as high fever and sudden drops in blood pressure; in rare cases, severe CRS can be fatal. Another significant concern associated with CAR T-cell therapies involves neurologic side effects, including confusion, seizure-like activity, and impaired speech. The precise cause of these neurologic effects, known as immune effector cell-associated neurotoxicity syndrome (ICANS), remains under investigation.
Segments Insights
Target Antigen Insights
The CD19 CAR T-cell therapy segment dominated the market in 2025, largely due to CD19's consistent and widespread expression across B-cell malignancies, making it a reliable target for treatment. Its broad expression across various stages of B-cell development, including both lymphomas and leukemias, expands the eligible patient pool and creates greater opportunities for successful treatment. CD19-targeted CAR T-cells have demonstrated high response rates and durable remissions in patients with acute lymphoblastic leukemia (ALL) and certain lymphomas, including diffuse large B-cell lymphoma. This track record has supported substantial research and development, leading to established protocols and more manageable manufacturing processes aligned with current treatment strategies.
The BCMA-targeted CAR T-cell therapy segment, meanwhile, is experiencing the fastest growth in the market, driven largely by its targeted approach against multiple myeloma and other B-cell malignancies. BCMA's high expression on malignant plasma cells makes it an effective target capable of inducing a strong immune response. BCMA-targeted therapies such as ciltacabtagene autoleucel and idecabtagene vicleucel have shown strong clinical trial results, including high response rates and durable remissions among patients with relapsed or refractory multiple myeloma, with continued FDA approvals further fueling this segment's expansion.
CAR T-Cell Therapy Market Revenue, By Target Antigen, 2022 to 2024 (USD Million)
| Target Antigen | 2022 | 2023 | 2024 |
| CD19 | 2,297.03 | 2,550.99 | 2,836.91 |
| BCMA (B-cell Maturation Antigen) | 481.71 | 588.81 | 717.87 |
| CD22 | 220.55 | 252.93 | 290.64 |
| GD2 | 121.37 | 142.22 | 166.88 |
| HER2 | 77.53 | 93.92 | 113.61 |
| GPC3 | 63.63 | 77.13 | 93.33 |
| Others (e.g., EGFRvIII, CD7, CD123, mesothelin) | 236.23 | 272.42 | 314.76 |
Indication / Disease Type Insights
The hematologic malignancies segment led the market in 2024, reflecting the therapy demonstrated success in treating cancers, particularly relapsed or refractory B-cell lymphomas and leukemias. CAR T-cell therapy has shown high response rates and durable remissions, especially among patients who have not responded to other treatments. Designed to target specific antigens on cancer cells, CAR T-cell therapy offers a more precise and potentially less toxic approach compared with traditional treatments like chemotherapy, and R&D in the space has heavily focused on hematologic cancers, resulting in approval of multiple CAR T products for these indications.
Meanwhile, the solid tumors segment is seeing rapid growth within the CAR T-cell therapy market, driven primarily by ongoing research aimed at overcoming challenges such as tumor heterogeneity and the immunosuppressive tumor microenvironment. Solid tumors can vary significantly even within the same cancer type, complicating efforts to identify a universal target antigen. Although CAR T-cell therapy has shown strong success in hematological cancers such as leukemia and lymphoma treatment, researchers continue working to address the distinct hurdles solid tumors present in order to improve efficacy and overcome treatment resistance.
CAR T-Cell Therapy Market Revenue, By Indication / Disease, 2022 to 2024 (USD Million)
| Indication / Disease | 2022 | 2023 | 2024 |
| Hematologic Malignancies | 3,308.78 | 3,748.45 | 4,255.12 |
| Solid Tumors | 189.28 | 229.98 | 278.88 |
Manufacturing Method Insights
The centralized manufacturing segment dominated the CAR T-cell therapy market in 2024, largely due to its ability to ensure standardized quality and support commercialization at scale. Centralized facilities, typically run by pharmaceutical companies, can implement rigorous quality control and minimize manufacturing variability, both essential for maintaining consistent product quality and safety, particularly for autologous therapies where each treatment is personalized to the individual patient. The complex, labor-intensive nature of autologous CAR T manufacturing has favored centralized facilities equipped with the infrastructure and expertise needed for large-scale production, essential to the initial commercialization of CAR T therapies.
The in vivo CAR T therapy segment is experiencing the fastest growth in the market, largely because it offers several key advantages over traditional ex vivo methods, including reduced manufacturing complexity, lower costs, faster turnaround times, and potentially broader patient access. In vivo methods bypass the labor-intensive, time-consuming ex vivo process of collecting a patient's T cells, modifying them in a laboratory, and reinfusing them, instead delivering the CAR gene directly into T cells within the body, often using engineered nanocarriers or viral vectors.
Technology / Vector Insights
The viral vectors segment dominated the global market in 2025, owing to their high transduction efficiency and ability to achieve stable gene expression, particularly with lentiviral and retroviral vectors. These vectors effectively integrate the CAR gene into the host T cell's genome, supporting sustained protein expression and long-term efficacy. While some safety considerations remain, ongoing advances in vector design and manufacturing continue to reduce these risks, with genomic integration helping ensure the CAR gene is maintained and expressed throughout the cell's life, including in its progeny.
The dual and multiple antigens targeting CAR T-cell segment is experiencing the fastest growth over the forecast period, driven by its ability to overcome tumor antigen escape, a significant challenge in CAR T-cell therapy. By targeting multiple antigens, these CAR T-cells can continue recognizing and attacking cancer cells even if one antigen is lost, an approach that enhances therapeutic effectiveness, particularly in solid tumors where antigen heterogeneity and variable expression levels are common. Dual and multiple targeting approaches are also improving overall anti-tumor activity and patient survival compared with single-antigen targeting.
CAR T-Cell Therapy Market Revenue, By Technology / Vector Used, 2022 to 2024 (USD Million)
| Technology / Vector Used | 2022 | 2023 | 2024 |
| Viral Vectors | 2,377.64 | 2,655.61 | 2,971.04 |
| Non-viral Vectors | 584.06 | 691.43 | 818.99 |
| Armored CAR T-Cells (enhanced T-cell persistence/activity) | 220.79 | 264.06 | 315.72 |
| Dual/Multiple Antigen Targeting CAR T-Cells | 222.50 | 259.41 | 302.89 |
| Safety Switch-Equipped CAR T Cells | 93.07 | 107.92 | 125.36 |
Type of Therapy Insights
Autologous CAR T-cell therapy maintained its dominant position in the global market in 2025, largely due to its personalized nature and demonstrated success in treating certain blood cancers. This approach is tailored to each patient, minimizing the risk of immune rejection by using the patient's own cells; a patient's T cells are genetically modified and reinfused, avoiding the immune rejection risks associated with donor-derived (allogeneic) therapies. This therapy has shown notable success in treating B-cell lymphomas and leukemia, including aggressive forms resistant to other treatments.
Allogeneic CAR T-cell therapy, by contrast, is seeing the fastest growth in the global market, largely because it addresses challenges associated with autologous therapies, including high costs, lengthy manufacturing timelines, and strict patient selection criteria. Allogeneic approaches draw cells from healthy donors, offering a more accessible, broadly applicable treatment option. These standardized, donor-derived products offer a more reliable option, particularly in regions with limited access to specialized healthcare facilities.
End User Insights
The hospitals segment led the market in 2025, supported by robust infrastructure, multidisciplinary care teams, and the capacity to manage complex treatments and their potential side effects. This dominance is further reinforced by rising investment in oncology facilities and continued advancement in hospital-based treatment protocols. Hospitals maintain specialized facilities, including dedicated operating theaters and intensive care units, essential for administering CAR T-cell therapy, along with multidisciplinary teams of oncologists, nurses, and pharmacists experienced in managing the therapy's complexities. Hospitals also provide a holistic approach to care, spanning pre-treatment evaluation, infusion, and post-treatment monitoring potential side effects.
The contract development and manufacturing organization (CDMO) segment is seeing rapid growth in the CAR T-cell therapy market, driven largely by the complexity and specialized requirements involved in developing and manufacturing these advanced therapies. Many biopharmaceutical companies, particularly smaller ones, lack the resources and expertise to build and maintain in-house production facilities. Partnering with CDMOs allows these companies to manage costs and reduce the financial risk of in-house development, while CDMOs experienced in navigating regulatory requirements can provide critical guidance and help ensure compliance, both essential for bringing new therapies to market.
CAR T-Cell Therapy Market Revenue, By End User, 2022 to 2024 (USD Million)
| End User | 2022 | 2023 | 2024 |
| Hospitals | 1,594.83 | 1,781.32 | 1,992.94 |
| Cancer Treatment Centers | 1,033.37 | 1,178.78 | 1,347.39 |
| Academic & Research Institutes | 447.85 | 501.36 | 562.25 |
| Specialty Clinics | 211.60 | 260.55 | 319.66 |
| Contract Development and Manufacturing Organizations (CDMOs) | 210.41 | 256.41 | 311.77 |
Regional Insights
Which Region Dominated the CAR T-Cell Therapy Market in 2025?
North America dominated the CAR T-cell therapy market, holding the largest share in 2025, driven by significant investment in cell-based research and development. The region benefits from well-established healthcare and research infrastructure, which continues to accelerate development and adoption of CAR T-cell therapy, along with strong regulatory support, substantial clinical trial activity, and a concentration of globally recognized biotechnology companies focused on next-generation CAR T-cell development.
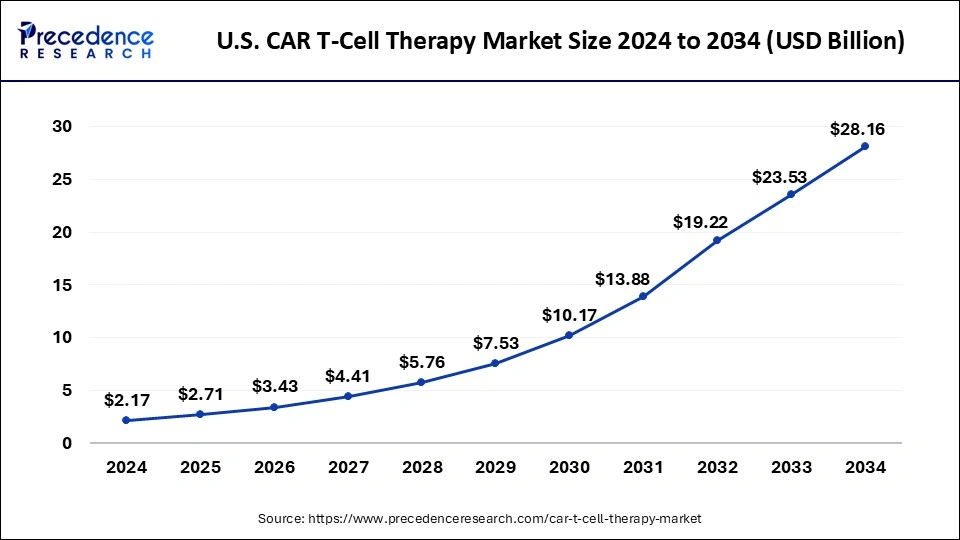
U.S. CAR T-Cell Therapy Market Size and Growth 2026 to 2035
The U.S. CAR T-cell therapy market size is evaluated at USD 2,684.84 million in 2026 and is projected to be worth around USD 11,510.04 million by 2035, growing at a CAGR of 17.47% from 2026 to 2035.
U.S. CAR T-Cell Therapy Market Trends
The U.S. CAR T-cell therapy market has seen significant growth, supported by rising cancer cases alongside substantial investment in research and development that continues to yield more innovative and effective therapies. U.S. researchers are accelerating breakthroughs in genetic engineering, diagnostics, and manufacturing to further improve the efficiency of CAR T-cell therapies. To date, seven FDA-approved CAR T-cell therapies have reached the U.S. market, with several others having secured approval internationally.
Asia Pacific CAR T-Cell Therapy Market Trends
The Asia Pacific CAR T-cell therapy market is expected to grow at the fastest rate over the forecast period, fueled by rising patient demand and a thriving innovation ecosystem. As cancer prevalence continues to rise, demand for cell-based cancer therapies like CAR T continues to grow alongside it. Countries such as Australia, Japan, and South Korea are showing relatively strong growth in this space, each supported by a clear regulatory pathway for CAR T registration and mature medical infrastructure for administration.
Japan CAR T-Cell Therapy Market Trends
The Japan CAR T-cell therapy market is entering a fast-growth phase, driven by infrastructure improvements, expanding indications, technological advances, and supportive regulation. The market offers significant growth opportunities for innovative players aiming to bring transformative cancer treatments to Japanese patients. In May 2025, Cellares Corporation, a California-based integrated development and manufacturing organization specializing in contract manufacturing of cell-therapy products, announced plans to establish its first major Asia development and production hub, a cell therapy manufacturing hub, in the Kashiwa-no-ha district of Kashiwa City, Chiba Prefecture, Japan.
Europe CAR T-Cell Therapy Market Trends
The Europe CAR T-cell therapy market held a significant share in 2025, supported by favorable demographic trends and ongoing improvements in cancer care. Several major European medical centers specialize in CAR T-cell therapy, with factors such as the range of available therapies, research involvement, and institutional reputation shaping each center's standing. Researchers across the region continue exploring additional target antigens to extend CAR T-cell therapy application to a wider range of conditions, including autoimmune diseases.
Germany CAR T-Cell Therapy Market Trends
Germany's CAR T-cell therapy market is evolving rapidly as the country strengthens its position in advanced cancer treatment through pancreatic precision cancer medicine and cell-based immunotherapies. A key trend is the growing adoption of CAR T-cell therapies among patients with relapsed or treatment-resistant blood cancers, supported by expanding clinical experience across specialized treatment centers. At the same time, research efforts are extending the potential use of these therapies into earlier treatment lines and additional cancer types, including solid tumors.
Middle East and Africa CAR T-Cell Therapy Market Trends
The Middle East and Africa CAR T-cell therapy market held a notable share in 2025. The region presents substantial development opportunities, driven in particular by rising healthcare investment and government-led cancer initiatives. Growing collaboration with Western biotechnology firms, alongside the emergence of specialized cancer hospitals, continues to create meaningful opportunities for broader healthcare reform, with South Africa, Egypt, and Ghana establishing themselves as key manufacturing and distribution hubs supporting regional cancer treatment infrastructure.
UAE CAR T-Cell Therapy Market Trends
The United Arab Emirates maintains one of the most advanced private healthcare infrastructures in the region, backed by government initiatives designed to incentivize investment and biotechnology partnerships. Collaborative ventures with global firms and the establishment of modern cancer treatment centers have expanded access to CAR T-cell therapy across the UAE. Government spending on healthcare infrastructure, new research facilities, clinical laboratories, and partnerships with international biopharmaceutical companies all stand among the key factors driving continued market growth.
Latin America CAR T-Cell Therapy Market Trends
The Latin America CAR T-cell therapy market held a considerable share in 2025. CAR T-cell therapy is becoming increasingly accessible across the region, with several treatment centers emerging as leaders in this specialized field. Countries throughout Latin America continue investing in healthcare infrastructure and forging partnerships with outside entities to help localize access to advanced cell therapies.
Brazil CAR T-Cell Therapy Market Trends
Brazil stands as the only country in Latin America to have secured regulatory approval for CAR T therapies treating B-cell malignancies and multiple myeloma, with approved products including axicabtagene ciloleucel (Yescarta), tisagenlecleucel (Kymriah), and ciltacabtagene autoleucel (Carvykti). The country's strong emphasis on biotechnology manufacturing has positioned it at the forefront of biologics development across Latin America.
Competitive Landscape
The CAR T-cell therapy market key players operate within a mature competitive landscape encompassing more than 250 companies and 500 drugs currently in development worldwide. Key opportunities remain concentrated around targeting hematologic malignancies and overcoming the ongoing challenges associated with solid tumors. Supported by strong partnerships and a robust CAR T-cell therapy pipeline, the industry remains well positioned to deliver transformative cancer treatment solutions. Continued advancement across the space is driving further innovation in targeting precision and helping overcome current therapeutic limitations, setting the stage for sustained growth across global cancer care.
CAR T-Cell Therapy Market Companies
- Johnson & Johnson Services, Inc.
- ALLOGENE THERAPEUTICS
- Lonza
- Aurora Biopharma
- Cartesian Therapeutics, Inc.
- Novartis
- Bristol-Myers Squibb company
- Gilead Sciences
- Curocell Inc
- JW Therapeutics
Recent Developments
- In April 2026, a new CAR-T cell therapy targeting advanced gastrointestinal cancers is anticipated to become available in China, as reported by the Jiahui International Cancer Center. This institution is set to lead in offering access to the therapy known as satri-cel (CT041), which is recognized as the world's first CAR-T treatment specifically formulated for solid tumors that target Claudin18.2, a biomarker prevalent in gastric and pancreatic cancers.
- In April 2025, Johnson & Johnson reported that the European Commission had expanded the indication of Darzalex (daratumumab) subcutaneous formulation to include only their multiple myeloma drug combination, bortezomib, lenalidomide, and dexamethasone combination as the treatment of newly diagnosed multiple myeloma (NDMM) patients, including those otherwise ineligible to receive a transplant. It had earlier been indicated in isolated patients who are transplant eligible (ASCT).
- In March 2025, Bristol Myers Squibb declared its plans to buy 2seventy Bio at approximately USD 286 million. The two firms collaborated on Abecma, a CAR T-cell medicine against multiple myeloma.
- In November 2024, the Food and Drug Administration (FDA) approved obecabtagene autoleucel (Aucatzyl, Autolus Inc.), a CD19-directed genetically modified autologous T cell immunotherapy, to be used in treating adult patients with relapsed or refractory B-cell precursor acute lymphoblastic leukemia (ALL).
Segments Covered in the Report
By Target Antigen
- CD19
- BCMA (B-cell Maturation Antigen)
- CD22
- GD2
- HER2
- GPC3
- Others (e.g., EGFRvIII, CD7, CD123, mesothelin)
By Indication / Disease Type
- Hematologic Malignancies
- Acute Lymphoblastic Leukemia (ALL)
- Diffuse Large B-cell Lymphoma (DLBCL)
- Mantle Cell Lymphoma (MCL)
- Follicular Lymphoma (FL)
- Multiple Myeloma (MM)
- Chronic Lymphocytic Leukemia (CLL)
- Hodgkin's Lymphoma
- Other Non-Hodgkin Lymphomas (NHL)
- Solid Tumors
- Neuroblastoma
- Glioblastoma
- Breast Cancer
- Pancreatic Cancer
- Ovarian Cancer
- Lung Cancer
- Prostate Cancer
- Colorectal Cancer
- Others
By Type of Therapy
- Autologous CAR T-cell Therapy
- Allogeneic CAR T-cell Therapy
By Technology / Vector Used
- Viral Vectors
- Lentiviral vectors
- Retroviral vectors
- Non-viral Vectors
- CRISPR/Cas9 gene editing
- Transposons (Sleeping Beauty, PiggyBac)
- mRNA electroporation
- Armored CAR T-Cells (enhanced T-cell persistence/activity)
- Dual/Multiple Antigen Targeting CAR T-Cells
- Safety Switch-Equipped CAR T Cells
By Manufacturing/Delivery Method
- Point-of-Care Manufacturing
- Centralized Manufacturing
- In vivo CAR T therapy (emerging)
- Off-the-shelf / Ready-to-use therapies
By End User
- Hospitals
- Cancer Treatment Centers
- Academic & Research Institutes
- Specialty Clinics
- Contract Development and Manufacturing Organization
By Geography
- North America
- Europe
- Asia-Pacific
- Latin America
- The Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting