
Data Center Pipes Market Size, Key Companies, Company Market Share, User Adoption, Technology Deployment, Revenue Growth, Competitive Positioning, and Demand Forecast
ICT industry specialist Gautam Mahajan estimates the data center pipes market at USD 935.91 million in 2026, with continued technology adoption expected to take the market to USD 5,521.54 million by 2035 at a CAGR of 21.80%. Leading data center pipes market providers such as GF Piping Systems, Victaulic, Aquatherm, IPEX are expanding their capabilities across segments including material, application, data center type and region.
Source: https://www.precedenceresearch.com/data-center-pipes-market
 Get a Sample
 Table Of Content


Data Center Pipes Market Size, Share, Trends, and Growth Forecast 2035
The data center pipes market is estimated at USD 935.91 million in 2026 and is projected to reach USD 5,521.54 million by 2035, expanding at a CAGR of 21.80% from 2026 to 2035.
Key Takeaways
Market Size & Growth Outlook
- Market size in 2026: USD 935.91 million
- Estimated market size in 2027: USD 1,139.94 million
- Projected market size by 2036: USD 5,521.54 million
- CAGR (2026–2035): 21.80%
Regional Market Spotlight
- North America led the market with a 44.80% (USD 344.24 million) share in 2025.
- Asia Pacific accounted for 27.60% (USD 212.08 million) of the market in 2025 and is projected to be the fastest-growing region, at a CAGR of 23.04% from 2025 to 2035.
- Europe accounted for 20.80% (USD 159.83 million) of the market in 2025.
Segmental Spotlight
- By material, Plastic & Composite accounted for 44.60% (USD 342.71 million) in 2025.
- By application, Cooling Systems accounted for 58.40% (USD 448.75 million) in 2025.
- By data center type, Hyperscale accounted for 46.20% (USD 355.00 million) in 2025.
Data Center Pipes Market Size and Forecast, 2025-2035 (USD Million)
The data center pipes market was valued at USD 935.91 million in 2026, the base year. The data center pipes market includes plastic, composite, steel, and copper pipes along with their associated fittings and prefabricated pipe modules, which are utilized for cooling, water supply, firefighting, and drainage applications in data centers. Cooling applications dominated in 2025, accounting for 58.40% due to the heavy use of chilled water, condenser water, and direct liquid cooling circuits in every hall, which require long lengths of piping. In terms of revenue generation, North America was the largest contributor with a 44.80% share in 2025, owing to the high volume of hyperscale and AI data centers under construction in this region.
Demand for data center pipes comes from liquid cooling of AI servers, where water is supplied to the rack and chip level; the rapid construction of hyperscale campuses; and the trend toward corrosion-resistant thermoplastic piping and prefabricated modules.
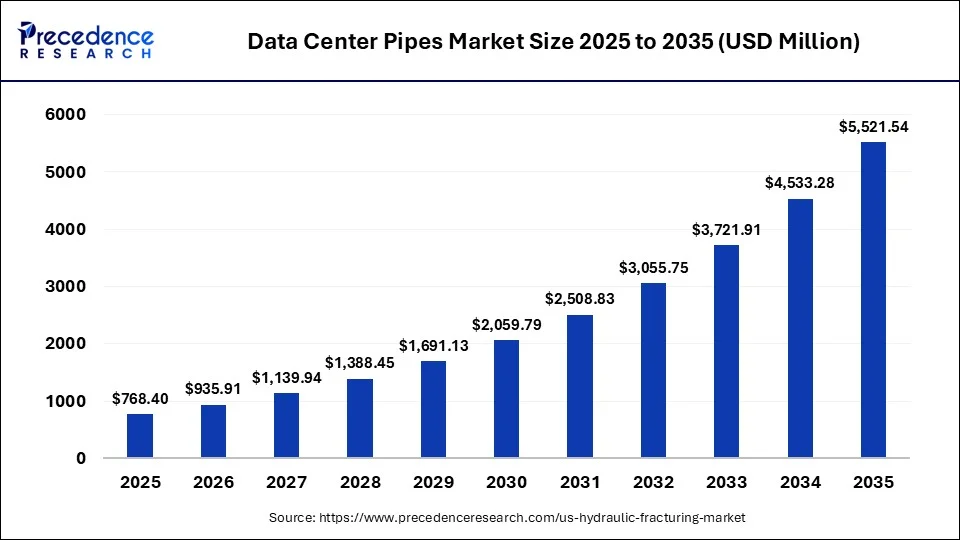
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The global data centre pipes market is expected to grow from USD 768.40 million in 2026 to USD 5,521.54 million in 2035, due to the fact that AI data centers install additional direct-to-chip liquid cooling loops on top of their facility chilled water system, thus increasing the total pipe mileage and value installed per MW. Thermoplastic pipes and modular pipe assemblies are growing their share because of corrosion resistance and faster installation, driving the global market up to USD 2,059.79 million by 2030, and maintaining a 21.80% CAGR in the 2026-2035 period.
- Analyst View: The forecast was built from the new data center capacity under construction in MW, multiplied by pipe mileage and value installed per MW in the facility cooling, liquid cooling, fire protection, and plumbing systems, by material. Intensity of liquid cooling was driven by the percentage of new capacity dedicated to AI and high-density racks, requiring additional cooling loops for racks and technology cooling loops. The total volume was benchmarked against the trend of the revenue and orders from the data centers reported by the leading pipe manufacturers and independent estimates, putting our base year somewhat higher than the comparable numbers.
Market Trends
- Direct liquid cooling is adding pipe loops at the rack and row level.
- Thermoplastic pipes are replacing metal in cooling loops.
- Prefabricated pipe modules are cutting on-site installation time.
- Infrared and electrofusion joints are improving leak-free reliability.
- Pre-insulated pipes support heat reuse and district heating links
- Pipe makers are partnering with cooling and connector suppliers.
Drivers, Restraints and Opportunities
Driver
AI server rooms require direct liquid cooling, which involves connecting water loops to each server rack, adding additional piping beyond the chilled water systems of facilities. Hyperscale and colocation companies are establishing massive campuses at unprecedented speed. They seek corrosion-proof and leakage-proof piping for protecting expensive IT assets and maintaining high purity of cooling water.
Restraint
Restrictions on power supply availability and permitting issues can limit data centre development and pipe demand. Pipe prices are subject to volatility of resin, steel, and copper costs. Some companies are careful about having water near their servers, which hinders installation of liquid cooling systems in existing data centres.
Opportunity
Prefabricated and tested pipe modules can decrease construction time and amount of on-site work. Liquid cooling retrofits of existing data centres involve new pipe demand. Heat reutilization projects connecting data centers to district heating grids require pre-insulated pipe systems.
Market Segmentation: 2025 Share and Value
Data Center Pipes Market by Material 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Plastic & Composite | 44.60% | USD 342.71 million |
| Steel | 31.80% | USD 244.35 million |
| Copper | 16.40% | USD 126.02 million |
| Others | 7.20% | USD 55.32 million |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Plastic and composite materials include polypropylene, polyethylene, PVC-C, and PVDF pipes, which contribute to 44.60% (USD 342.71 million) in the year 2025 due to their non-corrosive nature that maintains water purity in sensitive cooling circuits, lightweight nature and ease of joining using the fusion technique. The steel pipes contribute 31.80% (USD 244.35 million) and are widely used for large chilled water mains and fire protection systems. Copper pipes are used in smaller cooling and plumbing applications and make up 16.40% (USD 126.02 million) of the total market share.
Data Center Pipes Market by Application 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Cooling Systems | 58.40% | USD 448.75 million |
| Water Supply & Plumbing | 16.20% | USD 124.48 million |
| Fire Protection | 15.60% | USD 119.87 million |
| Others | 9.80% | USD 75.30 million |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Cooling systems accounted for 58.40% (USD 448.75 million) in 2025 and are the fastest-growing application, supported by chilled water, condenser water, heat recovery and direct liquid cooling loops. Water supply and plumbing account for 16.20% (USD 124.48 million); fire protection, at 15.60% (USD 119.87 million), covers sprinkler and suppression piping; and other uses such as drainage and fuel lines account for 9.80% (USD 75.30 million).
Data Center Pipes Market by Data Center Type 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Hyperscale | 46.20% | USD 355.00 million |
| Colocation | 32.40% | USD 248.96 million |
| Enterprise | 14.60% | USD 112.19 million |
| Edge | 6.80% | USD 52.25 million |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Hyperscale data centres accounted for 46.20% (USD 355.00 million) in 2025 and are the fastest-growing type because large AI campuses need extensive cooling piping. Colocation, at 32.40% (USD 248.96 million), grows as providers build high-density halls for AI tenants, while enterprise data centres account for 14.60% (USD 112.19 million) and edge sites for 6.80% (USD 52.25 million).
- Analyst View: The value segmentation of these components is based on the length per megawatt of the pipe in each of the cooling systems and their categorization based on materials and type of data centers. The cooling systems dominate because they have the highest pipe diameters and lengths, and also the AI halls will have additional liquid-cooling loops. It is expected that plastic and composite pipes and hyperscale data centers will increase in market share.
Regional Analysis
Data Center Pipes Market by Region 2025 Share & Size
| Region | 2025 Share | 2025 Market Value |
| North America | 44.80% | USD 344.24 million |
| Asia Pacific | 27.60% | USD 212.08 million |
| Europe | 20.80% | USD 159.83 million |
| Middle East & Africa | 3.80% | USD 29.20 million |
| Latin America | 3.00% | USD 23.05 million |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
North America accounted for 44.80% (USD 344.24 million) in 2026, growing on hyperscale and AI campus construction in the United States, where liquid cooling is being adopted fastest. Asia Pacific, at 27.60% (USD 212.08 million), is the fastest-growing region, supported by data centre expansion in China, Japan, India, Singapore, Malaysia and Australia, while Europe, at 20.80% (USD 159.83 million), grows on new capacity in Frankfurt, London, Amsterdam, Paris and the Nordics and on heat reuse projects. The Middle East and Africa, at 3.80% (USD 29.20 million), grows with AI data centre projects in the Gulf states, and Latin America, at 3.00% (USD 23.05 million), is led by Brazil and Mexico.
North America accounted for 44.80% (USD 344.24 million) in 2025. Hyperscale and AI campus construction in the United States drives pipe demand.
Asia Pacific accounted for 27.60% (USD 212.08 million) in 2025 and is the fastest-growing region. New capacity in China, Japan, India and Southeast Asia supports growth.
Europe accounted for 20.80% (USD 159.83 million) in 2025. Major data centre hubs and heat reuse requirements support demand for cooling piping.
The Middle East and Africa accounted for 3.80% (USD 29.20 million) in 2025. AI data centre projects in the Gulf states support growth.
Latin America accounted for 3.00% (USD 23.05 million) in 2025. Data centre construction in Brazil and Mexico supports demand.
- Analyst View: The regional shares were based on data center capacity being constructed in the regions, weighted by the percentage of liquid cooling use in the region and the dollar cost of pipe per megawatt. The region that has the most is North America, as it is the region that has the most pipelines for hyperscale and AI construction. The region that receives the most premium for growth is Asia Pacific.
Top 10 Companies in the Data Center Pipes Market
| Rank | Company Name | Market-Specific Revenue (USD Million) | 2025 Share | Key Products / Business | Headquarters |
| 1 | GF Piping Systems | 96 | 12.49% | PROGEF and SYGEF thermoplastic piping, COOL-FIT, LiquidCore modules | Switzerland |
| 2 | Victaulic | 58 | 7.55% | Grooved mechanical pipe joining for cooling and fire protection | United States |
| 3 | Aquatherm | 34 | 4.42% | Polypropylene piping systems for HVAC and cooling | Germany |
| 4 | IPEX | 30 | 3.90% | Thermoplastic piping systems | Canada |
| 5 | Mueller Industries | 28 | 3.64% | Copper tube and fittings | United States |
| 6 | NIBCO | 24 | 3.12% | Copper, plastic and steel fittings and valves | United States |
| 7 | Wavin | 22 | 2.86% | Plastic piping systems | Netherlands |
| 8 | Viega | 20 | 2.60% | Press-fit pipe joining systems | Germany |
| 9 | Brugg Pipes | 18 | 2.34% | Pre-insulated and flexible pipe systems | Switzerland |
| 10 | ISCO Industries | 16 | 2.08% | HDPE piping systems and fabrication | United States |
Note: Company revenues and shares are 2026 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
GF Piping Systems had the lead in the data centre pipes market with 12.49% (USD 96.00 million) in the 2026 revenue share, followed by Victaulic with 7.55% (USD 58.00 million) and Aquatherm with 4.42% (USD 34.00 million). GF Piping Systems dominates through the provision of specialized thermoplastic solutions for direct liquid cooling and facility cooling; Victaulic through the utilization of grooved jointing techniques, which are commonly used for data centre cooling and fire protection systems, while Aquatherm provides polypropylene piping for cooling loops. The top ten firms represented 45.03% (USD 346.00 million) of the 2026 revenue, and the rest of 54.97% (USD 422.40 million) belongs to regional pipe manufacturers, steel pipe suppliers, and fabricators/mechanical contractors offering prefabricated pipe modules. The market is highly fragmented, with competition based on corrosion resistance, speed of jointing, leak-proofness, and prefabrication, with specialists in thermoplastics, metal pipe manufacturing, and joining systems competing for hyperscale projects.
Recent Developments
- July 2026: GF reported that its orders for direct-to-chip liquid cooling systems doubled year on year in the first half of 2026 and announced a partnership with Parker Hannifin on plug-and-play liquid cooling connections.
- November 2025: GF launched LiquidCore, a prefabricated system combining polymer piping, valves and instrumentation for data centre liquid cooling.
- May 2025: Victaulic presented grooved mechanical pipe joining for data centre cooling and fire protection at Tech Show Frankfurt, highlighting faster installation and reusable couplings.
- April 2025: GF Piping Systems showcased direct liquid cooling solutions for AI data centres, including SYGEF IT rack manifolds, a technology cooling system and prefabricated piping, at HVAC Korea 2025.
Market Segments
By Material
- Plastic & Composite
- Steel
- Copper
- Others
By Application
- Cooling Systems
- Water Supply & Plumbing
- Fire Protection
- Others
By Data Center Type
- Hyperscale
- Colocation
- Enterprise
- Edge
By Region
- North America (U.S., Canada, Mexico)
- Europe (Germany, U.K., France, Italy, Spain, Rest of Europe)
- Asia Pacific (China, Japan, India, South Korea, Taiwan, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East & Africa (GCC, South Africa, Rest of MEA)
Research Methodology
The pipes in the data centers market were described as pipes, fittings, and prefabricated pipe modules of plastics, composites, steel, copper, and other materials used in data centers across the world for cooling, water supply, fire protection, and other purposes. The base year 2025 was constructed bottom-up using the new data center capacity, length, and value per MW by system type and liquid cooling of new capacity and was checked top-down using the revenue and orders data of leading pipe suppliers. Segment-wise, application-wise, data center type-wise and region-wise values were allocated based on material type, application, data center type and regional construction pipeline. All the key estimates were cross-verified using company disclosures, regulations, and industry data, and third-party estimates and inconsistent inputs were discarded. All the segment-wise, application-wise, data center type-wise, and region-wise figures have been brought to the same base year 2025, and the 2026-2035 forecasts have been recalculated using the constant CAGR.
Analyst View: Overall Market
The data center pipes market is experiencing gains from the change towards liquid cooling, where pipes are transformed from being standard building services to being essential cooling facilities. The market forecast ties the demand to new capacity, liquid cooling share, and value per megawatt of the pipes. Thus, the forecast is based on the growth of data center construction and AI usage. The key positives will be the growth of direct liquid cooling and prefabrication.
Sources and References
- GF Piping Systems. "GF Piping Systems showcases direct liquid cooling solutions at HVAC Korea 2025". 2025-04-02. SYGEF IT rack manifolds and DLC cooling system technology. https://mb.cision.com/Main/20131/4128095/3357959.pdf
- Tech Show Frankfurt / Victaulic. "Streamlining data centre cooling and fire protection systems". 2025-05-15. Grooved pipe joining for data centres. https://www.techshowfrankfurt.de/exhibitor-press-releases/streamlining-data-centre-cooling-fire-protection-systems
- BeBeez. "Piping specialist Georg Fischer sees liquid cooling orders double in first half of 2026". 2026-07-21. GF liquid cooling orders, LiquidCore and Parker partnership. https://bebeez.eu/2026/07/21/piping-specialist-georg-fischer-sees-liquid-cooling-orders-double-in-first-half-of-2026/
- Georg Fischer. "Direct Liquid Cooling (DLC) solutions for AI next-generation data centers at DCW London". 2025-03. Thermoplastic DLC piping. https://www.georgfischer.com/en/newsroom/media-releases/newsdetail.html/news/gfps/2025/hq/direct-liquid-cooling-(dlc)-solutions-for-ai-next-generation-data-centers-at-dcw-london
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting