
Diagnostic Testing Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Competitive Positioning, and Demand Forecast
The global diagnostic testing market is shifting from high-volume routine testing toward molecular, oncology, precision and decentralized diagnostics, with growth expected throughout the 2026-2036 forecast period. Routine chemistry and immunoassay remain the volume backbone of the market. Demand is supported by aging populations, rising chronic disease burden, earlier detection and automation, while reimbursement and test mix increasingly determine revenue realization. The report analyzes the market by test type, technology, application, testing site, end user and region, covering reimbursement, test-mix economics, workflow integration, competitive models, M&A, high-value white spaces and scenarios through 2036 for manufacturers, laboratories, investors and other healthcare stakeholders.
Source: https://www.precedenceresearch.com/diagnostic-testing-market
 Get a Sample
 Table Of Content


What is Diagnostic Testing Market Size?
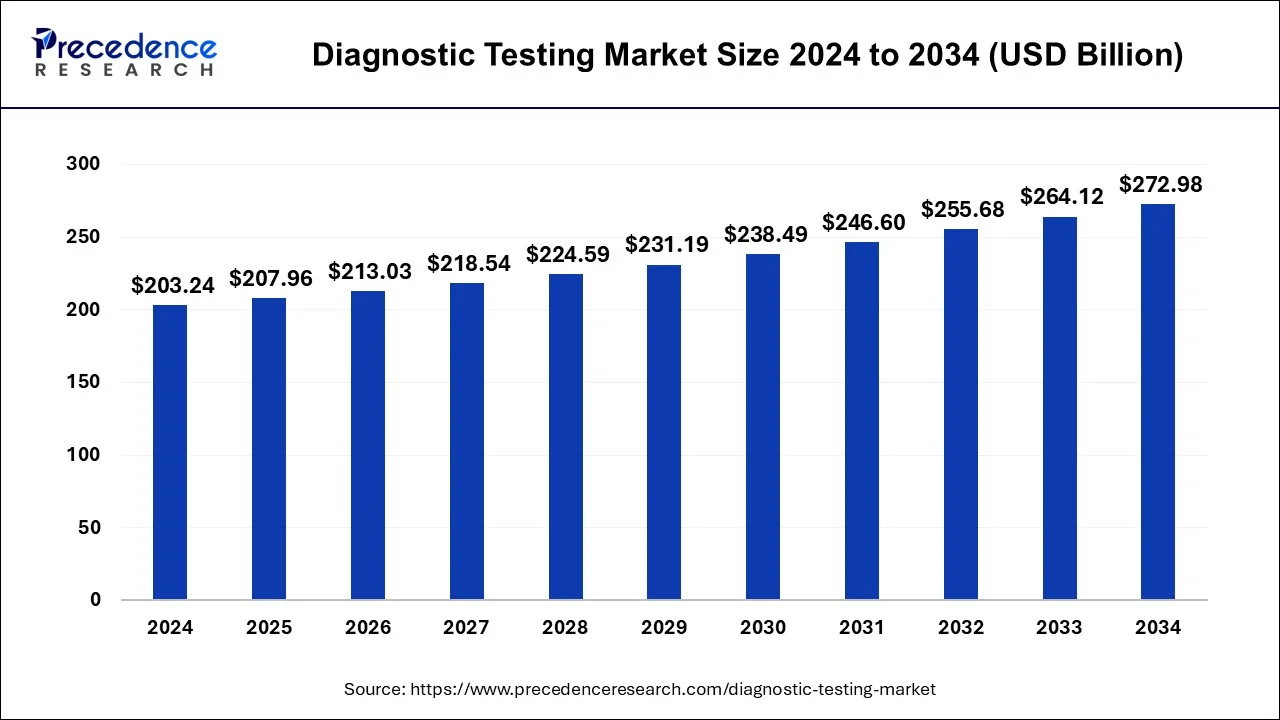
The global diagnostic testing market size calculated is grew to USD 213.03 billion in 2026, and is predicted to surpass around USD 281.56 billion by 2035, poised to grow at a CAGR of 3.08% between 2026 and 2035.
Key Takeaways
- The market includes laboratory-based clinical testing, molecular and genetic testing, pathology, immunoassay, clinical chemistry, microbiology, hematology, point-of-care, and selected home testing, but excludes diagnostic imaging.
- The United States alone performs approximately 14 billion laboratory tests annually across more than 266,000 CLIA-certified laboratories.
- Diagnostic results influence approximately 70% of healthcare decisions, while diagnostic services account for only around 3-5% of healthcare budgets.
- Routine chemistry and immunoassay remain the volume backbone, while molecular, oncology, and genetic testing are the faster-growing revenue pools.
- Preliminary 2027 reimbursement data indicate that Medicare had been paying approximately 16% more than private payers for laboratory services.
- One major U.S. laboratory reported 12.3% growth in requisition volume in 2026, while revenue per requisition increased only 0.1%, illustrating the gap between volume growth and revenue growth.
- bioMérieux expanded its SPOTFIRE installed base to 6,400 systems at year-end 2026, more than doubling the prior-year base.
- Natera generated USD 2.31 billion in 2026 revenue from approximately 3.53 million tests, at a gross margin of approximately 64.7%, illustrating the revenue density of specialty testing.
- Abbott completed its approximately USD 20.6 billion acquisition of Exact Sciences in March 2026, adding differentiated cancer diagnostics to its portfolio.
Competitive rivalry is rated high and buyer power medium to high, while the threat of new entrants is medium. - Base, upside, and downside scenarios run through 2036, driven by reimbursement, liquid biopsy and precision medicine adoption, and point-of-care deployment.
Market Overview - Diagnostic Testing is Shifting from High-Volume Routine Testing Toward Higher-Value Molecular, Precision, and Decentralized Workflows
The market includes laboratory-based clinical testing, molecular and genetic testing, pathology, immunoassay, clinical chemistry, microbiology, hematology, point-of-care testing, and selected home/self-testing applications, but excludes diagnostic imaging. Market estimates vary materially depending on whether they include laboratory services, imaging, research-use products, and genetic testing; the full analysis therefore establishes a consistent market boundary before sizing each opportunity.
The underlying economics are unusually volume-driven. The United States alone performs approximately 14 billion laboratory tests annually across more than 266,000 CLIA-certified laboratories, demonstrating the enormous recurring volume pool supporting reagents, consumables, analyzers, laboratory services, and data platforms. Globally, diagnostic results influence approximately 70% of healthcare decisions, while diagnostic services account for only around 3-5% of healthcare budgets, highlighting a structural mismatch between clinical importance and healthcare spending.
Growth is increasingly shifting toward molecular diagnostics, oncology testing, companion diagnostics, liquid biopsy, infectious-disease panels, pharmacogenomics, decentralized testing, automation, digital pathology, and AI-enabled interpretation. Routine chemistry and immunoassay remain the backbone volume, but the fastest-growing revenue pools increasingly depend on clinical differentiation, reimbursement, workflow integration, and evidence rather than test volume alone.
Key Coverage
- Laboratory versus point-of-care versus home-testing economics
- Routine versus molecular, genetic, pathology, and precision-testing revenue pools
- Test volumes, diagnosis rates, reimbursement, ASP, revenue/test, and utilization
- Regional market structure and diagnostic infrastructure
- Market concentration across manufacturers and laboratory service providers
- Structural shift toward automation, decentralization, and higher-value testing
Test Volume Remains the Core Growth Engine, but Revenue Mix is Moving Toward Higher-Value Diagnostics
The full analysis separates volume growth from price/mix growth. Mature routine testing is likely to see modest pricing expansion, while oncology, genetic, companion, molecular, and specialized pathology testing can generate substantially higher revenue per accession. The incremental opportunity is therefore expected to come disproportionately from test-mix migration rather than an equivalent increase in total test counts.
Key Coverage
- 2019-2026 historical market development
- 2026 base-year estimate
- 2030 and 2035 revenue forecasts
- Base, upside, and downside scenarios
- Revenue/test and test-volume bridges
- Regional and segment contribution to incremental revenue
- Price, mix, and utilization decomposition
Segmentation Analysis - Core Laboratory Supplies Scale, While Molecular, Oncology, Point-of-Care and Genetic Testing Capture Disproportionate Growth
The market is segmented by test type, technology, application, specimen, testing site, end user, business model, and geography. Core laboratory testing, including clinical chemistry, immunoassay, hematology, coagulation, and urinalysis, remains the largest recurring volume pool. Molecular diagnostics and genetic testing represent smaller but faster-growing revenue pools, particularly in oncology, infectious disease, reproductive health, inherited disease, and precision medicine.
Point-of-care testing is gaining strategic importance because it shifts testing closer to the patient and reduces turnaround time. Meanwhile, centralized laboratories retain major advantages in scale, automation, quality control and cost per test.
Key Coverage
- Clinical chemistry, immunoassay, hematology and microbiology
- Molecular diagnostics and PCR
- Genetic and next-generation sequencing-based testing
- Pathology and specialized diagnostics
- Point-of-care and home testing
- Infectious disease, oncology, cardiology, diabetes, reproductive health and other applications
- Hospitals, independent laboratories, physician offices, pharmacies and home settings
Which Market Forces Will Sustain Diagnostic Testing Demand, and Where Will Reimbursement Pressure Constrain Monetization?
The diagnostic testing market is being supported by a combination of rising cancer, diabetes, cardiovascular disease, infectious disease, and age-related conditions, alongside greater screening intensity, earlier disease detection, personalized medicine, and longitudinal monitoring of patients receiving chronic therapies. At the same time, the U.S. reimbursement environment highlights the tension between rising testing demand and revenue realization. Preliminary 2027 reimbursement data indicate that Medicare had been paying approximately 16% more than private payers for laboratory services, reinforcing the importance of payer mix and reimbursement rates in determining laboratory economics.
Our analysis suggests that growth in demand is structurally higher than growth in pricing. Underlying need for diagnostic testing is rising as healthcare systems seek to move toward earlier diagnosis, screening and treatment monitoring, but laboratories are contending with countervailing pressures from reimbursement constraints, labor shortages, instrument capital requirements, utilization management and payer scrutiny of low-value or duplicative testing. Our view is that the most compelling growth opportunities will be increasingly concentrated in testing categories where improved diagnostic accuracy, earlier detection or treatment selection can demonstrate measurable clinical value rather than in incremental increases in routine testing.
We believe the key strategic implication is a widening of the gap between growth in diagnostic volume and growth in diagnostic revenue. Laboratories and diagnostic providers that can improve productivity through automation, optimize repeat-testing economics, manage labor intensity and expand into higher-value clinical applications should be better positioned to leverage rising testing demand and convert it into revenues. This is especially true across oncology, chronic-disease monitoring, preventive screening, precision medicine and underserved emerging-market populations, where diagnostic penetration and need can still fall short of potential.
The report quantifies these dynamics across disease-specific testing intensity, patient and aging demographics, screening penetration, diagnosis rates, testing utilization, reimbursement levels, payer mix, repeat-testing patterns, laboratory productivity, labor constraints and unmet diagnostic needs by geography. It also assesses how these factors impact revenue per test, utilization, margin potential and the relative attractiveness of routine versus specialized diagnostic testing segments.
How Do Reimbursement, Test Mix, and Productivity Determine Diagnostic Testing Profitability?
Diagnostic testing economics vary significantly by test type, reimbursement level, laboratory workflow, and utilization, making a single ASP an incomplete measure of market profitability. High-volume chemistry and immunoassays typically generate lower revenue per test than specialized oncology, genetic, and molecular assays, while pathology and point-of-care testing follow distinct pricing and cost structures. The relevant economic lens therefore extends from reimbursement per test to revenue per requisition, tests per requisition, payer mix, and test mix.
Our analysis suggests that the link between volume growth and revenue growth is non-linear, particularly given test mix and pricing power dynamics. One major U.S. laboratory reported a 12.3% growth in requisition volume in 2026, but revenue per requisition grew by only 0.1%, highlighting the importance of test mix and pricing on revenue realization. We believe that profitability drivers are increasingly determined by the ability to scale testing throughput with an economically favorable mix of routine and specialized assays.
We believe that the key strategic implication is that laboratory economics are increasingly tied to productivity (and cost per test) rather than reimbursement alone. Automation, instrument utilization, reagent-rental economics, and workflow efficiency can have a material impact on the economics of high-volume testing, while specialized assays can bolster revenue per test but with higher technical, labor, and operational complexity. The relative contribution of payer mix, reimbursement exposure, test utilization, and gross margin by test category becomes critical in evaluating sustainable profitability.
The full report reviews ASP and reimbursement by test category, revenue per requisition, revenue per test, tests per requisition, payer mix, instrument placement, reagent-rental economics, gross-margin differences between routine and specialized testing, and automation-driven cost per test to evaluate how pricing and operating efficiency drive lab economics.
What is Driving the Shift from Analyzer-Centric Capacity Toward Integrated, Connected Diagnostic Workflows?
The diagnostic value chain increasingly operates as an integrated workflow spanning specimen collection and transport, sample preparation, reagents and assays, instrumentation, analysis, interpretation, reporting, and clinical decision-making, with laboratory information systems and data connectivity linking these stages. Our analysis indicates that effective diagnostic capacity is no longer determined by instrument capacity alone. Skilled laboratory labor, reimbursement, sample logistics, reagent availability, regulatory clearance, quality systems, data integration, and clinical validation can all constrain the ability to convert installed capacity into completed and clinically actionable tests.
We see that the focus of technology investment is shifting towards workflow integration and recurring-use models. The emergence and growth of high-throughput automation, multiplex molecular testing, syndromic panels, digital pathology, liquid biopsy, NGS, AI-assisted interpretation, miniaturized point-of-care platforms and connected home testing represents an evolution towards faster, scalable and decentralized diagnostic workflows. The installed-base model is of strategic importance as the instrument placements can generate recurring reagent and consumable demand. For example, bioMérieux extended its SPOTFIRE installed base to 6,400 systems at year-end 2026, up more than double from the previous year's base, while BIOFIRE non-respiratory panels generated €598 million in 2026 sales.
We examine that the key strategic implication is that diagnostic competitiveness is increasingly linked to the economics and connectivity of the entire workflow and less to the performance of individual analyzers. Platforms that combine automation, consumables pull-through, data interoperability and clinically validated applications can generate more recurring-revenue characteristics, while the laboratories increasingly need to leverage utilization, turnaround, labor productivity and integration of testing environments.
The full report assesses the end-to-end diagnostic value chain, instrument-reagent recurring-revenue models, laboratory automation and utilization, molecular and multiplex testing, NGS and liquid biopsy, digital pathology and AI, point-of-care and decentralized testing, and data interoperability and laboratory information systems to evaluate how the technology adoptions are transforming effective capacity and industry economics.
How Do Scale, Installed Base, Reagent Recurrence, and Specialty Testing Shape Diagnostic Competition?
The diagnostic testing market is structured around three distinct competitive models: global diagnostic-platform manufacturers, specialized diagnostic innovators, and laboratory service providers. Scale-based players benefit from installed instruments, reagent pull-through, broad test menus, distribution infrastructure, and long-term customer relationships, while specialized companies compete through differentiated assays, clinical evidence, proprietary biomarkers, and higher revenue per test. Our analysis indicates that competitive position is therefore determined by the quality of revenue and recurring economics, not company revenue alone.
We believe there is a structural difference between platform manufacturers and specialty laboratories due to installed-base economics. Large instrument base installations can provide continued reagent and consumable revenue even if the number of instruments installed plateaus, while specialty labs can provide increased revenues from test volume expansion without a similar instrument base. In 2026, Roche's CHF sales for its Diagnostics segment totaled CHF 13.8 billion, of which CHF 7.6 billion came from its Core Lab, CHF 2.5 billion from its Molecular Lab, CHF 2.0 billion from its Near Patient Care and CHF 1.7 billion from its Pathology Lab segments, with its diagnostic solutions reaching approximately 258 million lives globally.
In our opinion, specialty testing is establishing a second path to competition (in terms of revenue density and clinical differentiation). In 2026, Natera posted a revenue of USD 2.31 billion, representing a gross margin of approximately 64.7% for the year, with the company conducting about 3.53 million tests, while Guardant Health posted revenue of USD 982 million, comprising approximately 276,000 oncology tests for the year. The economics in these examples show that diagnostic platforms can be much more profitable per test when there is clinical differentiation and complexity within the application.
The full report provides a detailed analysis of the competitive landscape based on platform manufacturers, specialty diagnostic companies and lab service providers, featuring installed-base scale, recurring reagent/consumable revenue, specialty-testing revenue density, lab consolidation, market concentration and fragmentation, technology differentiation and application-specific positioning to highlight the business models driving competitive advantage within the diagnostic testing market.
Which Competitive Metrics Will Define Leadership Beyond Market Share and Revenue Scale?
The diagnostic testing market requires market-share estimates based on diagnostic-specific revenue, rather than allocating total corporate revenue to diagnostics. Our analysis indicates that competitive position is best assessed through a combination of revenue, test volume, growth, profitability, installed base, recurring revenue, assay breadth, geographic reach, R&D intensity, regulatory approvals, and specialty-testing exposure. This approach distinguishes platform scale from the underlying strength and quality of diagnostic revenue.
The strategic takeaway is that market share is not enough to measure competitive advantage, and that is our view. The economics of a company with a big installed base and a good portion of recurring reagent revenue are quite different from a company that's growing mainly with requisition volume, and the specialized testing providers may realize more value from clinical differentiation and better revenue per test. The report thus includes a comparison of scale and revenue quality such as installed instruments, reagent pull-through, growth, and profitability, among other items, in terms of recurring versus non-recurring revenue.
The full report measures top 5 and top 10 market concentration within the prescribed universe of diagnostics tests and identifies the companies that performed best on measures of diagnostic revenue, test volume, requisition volume, revenue per test, revenue per requisition, recurring revenue, installed base, reagent pull-through, growth, gross margin, and profitability to differentiate market size from sustainable competitive strength.
How is Competitive Advantage Shifting Toward Multiplexing, Precision, and Integrated Diagnostic Workflows?
Product benchmarking spans clinical chemistry, immunoassay, hematology, microbiology, molecular diagnostics, pathology, genetic testing, point-of-care, and specialty oncology assays, allowing the report to distinguish companies with broad diagnostic portfolios from those concentrated in higher-value applications. Our analysis indicates that portfolio breadth remains important for scale, but competitive differentiation increasingly depends on the depth of capabilities within molecular, genetic, oncology, and decentralized testing.
We believe that competition in technology will no longer be around a single assay, but on how workflows can be integrated and used in clinical settings. The report compares the installed base, regulatory status, commercial deployment, R&D investment and clinical application of PCR, multiplex PCR, NGS, mass spectrometry, digital pathology, AI-assisted interpretation, automation, decentralized testing and liquid biopsy. These dimensions differentiate existing technologies that are commercially adopted from those technologies that may need additional clinical validation and/or regulatory expansion to be competitive.
In our opinion, the most important competitive gap is between stand-alone diagnostic products and integrated testing workflows. The sample-to-answer processing and interpretation, clinical decision support and longitudinal data can be applied to more points in the diagnostic journey than providers with a primary focus on individual tests. Application-level positioning is then evaluated in oncology, infectious disease, women's health, cardiometabolic disease, transplantation, pharmacogenomics and population screening, which present significant differences in clinical need and uptake.
The full report compares the breadth of the product menu, molecular and NGS capabilities, oncology and liquid-biopsy experience, platforms for point-of-care and decentralized testing, digital pathology and AI, clinical and regulatory experience, and application-specific competitive positions to identify where technological differentiation is gaining commercial and clinical ground.
Where Do Geographic Localization, Manufacturing Footprints, and Laboratory Networks Create Competitive Advantage in Diagnostics?
The analysis shows that the geographical competitive advantage has become the result of growing market size and local operating infrastructure. North America is currently the highest value diagnostic market, and Asia Pacific offers a great opportunity for incremental volume growth due to population size, growing healthcare infrastructure and testing penetration. In the case of India, the IVD market is estimated to be around USD 2.9 billion in 2026, and the narrow IVD definition projects a growth rate of around 9.5% CAGR until 2030.
We believe that localization is now a growing part of market access and supply resiliency. This means that manufacturing footprint, reagent localization, laboratory-network density, distributor coverage, direct sales, hospital relationships, public-sector tenders and local regulatory capabilities are among the elements of competitive benchmarking. These may impact testing reliability, customer reach, regulatory implementation and scaling of testing across disparate health care systems.
The strategic takeaway is that market size or growth rates are not enough measures for geographic expansion in our perception. The manufacturing and the supply of reagents should be based upon local demand, and the laboratory networks and the channel structure should ensure good distribution of the diagnostic platforms to the hospitals and the physicians, as well as to the laboratories and other testing sites. This has led to materially different competitive dynamics in developed markets and emerging markets, especially in areas where direct sales, distributors, public procurement, and partnerships in the local market all exist.
The full report examines regional and country-level competitive positioning across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. It compares market share, reagent localization, laboratory-network density, distributor versus direct-sales models, hospital and physician relationships, public-sector tender exposure, and emerging-market expansion strategies. The analysis assesses how localization and customer access influence competitive positioning.
How is M&A Reshaping Diagnostic Competition Toward Integrated Cancer, Molecular, and Laboratory Platforms?
Our analysis suggests that rather than just another commodity testing volume, diagnostic M&A is starting to focus on capabilities that are differentiated. The focus of acquisition activity is on specialty testing and oncology diagnostics, molecular platforms, laboratory networks and complementary technologies, and part of the solution is to broaden clinical depth, application scope, and access to existing lab infrastructure.
The recent transaction of Exact Sciences Corporation to Abbott for about USD 20.6 billion in March 2026 is an example of such a strategic shift. By acquiring Cologuard, Oncotype DX and other cancer diagnostics, Abbott brings a proven diagnostic platform and a differentiated oncology diagnostic capability to its portfolio. The arrangement also highlights an approach for well-known vendors to gain rapid market access to higher-margin specialty testing by acquiring a small business and offering existing commerce systems.
We believe that future consolidation is expected to be increasingly driven by capabilities that will grow clinical differentiation, technology depth and geographic or laboratory network access. Acquisition value, clinical support, commercialization potential and portfolio integration are all factors that are relevant to the quality of the portfolio being acquired, its clinical evidence, commercial reach and integration potential, along with the headline deal value and the target revenue.
The full report consists of an analysis of 2024-2026 acquisitions and partnerships, the value of deals and target revenue, oncology and molecular diagnostics transactions, laboratory-network consolidation, technology acquisitions, geographic expansion, and emerging M&A themes, and looks at how the consolidation of diagnostics is changing the competitive landscape in the market.
Which Diagnostic Business Models are Shaping Competitive Positioning and Growth?
The competitive landscape is characterized by distinct business models rather than a single path to scale. Our analysis indicates that platform leaders, laboratory service providers, specialty diagnostics innovators, genomics and liquid-biopsy challengers, and regional specialists compete through different combinations of scale, recurring revenue, clinical differentiation, network density, and market access. Detailed company profiles therefore assess diagnostic revenue, test volumes, product portfolio, technology, geographic footprint, manufacturing, R&D, regulatory approvals, strategic investments, M&A, margins, and growth opportunities across the 20-25 selected companies.
We believe that scale offers various competitive advantages within the context of the business model. Large installed base and recurring reagent revenue are important attributes for platform leaders, while testing volume, network density, and procurement efficiency are critical drivers for laboratory scale leaders. Specialty diagnostics innovators are able to capture the higher dollar value for differentiated tests while genomics and liquid biopsy challengers focus on higher-value clinical applications. Local knowledge of reimbursement, distribution, and regulatory systems can be used to benefit regional experts. The size of such laboratory-service models can be seen from the revenue generated by Sonic Healthcare, which reached A$9.6 billion in FY2026, and the revenue of Labcorp, with approximately USD 14.0 billion in revenue and approximately 175 million patients served in FY2026.
The important strategic takeaway is that company performance needs to be measured according to the business model, not just the size of the revenues. The report thus evaluates the competitive positioning of each company based on the composition of its portfolio, the extent of its technological capabilities, geographic reach, pipeline, M&A activity and operating economics and identifies scale advantages that are considered to be established versus those that could be gained through strategic investment in the future.
The full report includes detailed profiles that feature a financial and diagnostic exposure, market role and estimated market share breakdown, product and application positioning, geographical and laboratory deployments, R&D and technology pipeline, M&A and partnerships, competitive strengths and weaknesses and growth opportunities breakdown for a selected universe of companies.
Where Do Diagnostic Penetration Gaps Create the Most Actionable White-Space Opportunities?
Our analysis indicates that the largest white-space opportunities occur where diagnostic penetration remains below clinical need and where testing can be expanded through economically viable delivery models. Key areas include underserved emerging-market testing, decentralized diagnostics, preventive screening, oncology early detection, infectious-disease multiplexing, companion diagnostics, pharmacogenomics, home testing, and AI-supported interpretation. These opportunities differ in both clinical value and commercialization requirements, making penetration, reimbursement, and delivery infrastructure important dimensions of opportunity assessment.
We assess that diagnostic availability gaps are particularly relevant where disease burden is high, but testing access remains limited. The opportunity analysis therefore compares diagnostic penetration across developed and emerging healthcare systems and identifies applications where greater testing availability could address unmet clinical needs. It also evaluates lower-cost and decentralized platforms where expanding access does not require replicating the full infrastructure of centralized laboratory networks.
In our view, the strategic implication is that white space is defined not simply by low testing penetration, but by the intersection of clinical need, affordability, accessibility, and reimbursement. Opportunities in point-of-care testing, preventive screening, oncology early detection, molecular infectious-disease testing, home diagnostics, and AI-enabled workflows therefore require assessment of both the addressable patient population and the economics required to convert unmet need into sustainable testing demand.
The full report quantifies emerging-market diagnostic penetration gaps, preventive screening opportunities, point-of-care and decentralized testing potential, oncology early-detection applications, molecular infectious-disease testing, home diagnostics, AI-enabled diagnostic workflows, and reimbursement-driven white spaces to identify where underpenetrated testing categories offer the clearest expansion opportunities.
How Do Regulatory Barriers, Recurring Diagnostic Demand and Technology Fragmentation Shape Market Attractiveness?
Our analysis indicates that the diagnostic testing market combines meaningful structural barriers with persistent underlying demand. Supplier power is medium, as specialized reagents, instruments, and molecular platforms can create switching barriers, although large laboratory networks retain procurement leverage. Buyer power is medium to high, reflecting increasing negotiation around price, utilization, and outcomes. The threat of new entrants is medium, with regulatory approval, clinical validation, reimbursement, and laboratory infrastructure limiting entry while software-enabled and specialty tests can access narrower niches. The threat of substitutes is low to medium, as individual testing technologies can be replaced but diagnostic testing remains fundamental to clinical care. Competitive rivalry is high, reflecting competition among global platforms, specialty diagnostics companies, and vertically integrated laboratory networks.
Our assessment is that regulation and reimbursement remain central determinants of commercial scalability. PESTLE analysis evaluates the influence of healthcare expenditure, aging populations, infectious-disease surveillance, AI and genomics, diagnostic regulation, reimbursement reform, data privacy, laboratory quality requirements, and consumables sustainability on market development. These factors can affect both the pace of technology adoption and the economics of delivering diagnostic services across different healthcare systems.
In our view, the key strategic implication is that market attractiveness depends on the interaction between demand durability and the ability to convert innovation into reimbursed, scalable testing. Markets with strong healthcare spending, persistent diagnostic demand, manageable regulatory pathways, expanding testing access, and opportunities for technology adoption can support greater investment intensity, while reimbursement constraints, regulatory complexity, and infrastructure gaps can limit margin potential despite significant clinical need.
The full report assesses Porter's Five Forces, regulatory barriers, reimbursement conditions, healthcare spending, technology disruption, diagnostic-access gaps, regional attractiveness, investment intensity, and margin potential to determine how industry structure and external market forces influence the relative attractiveness of diagnostic testing opportunities.
How Will Diagnostic Testing Evolve from Higher Test Volumes Toward Greater Clinical Value per Test?
The base case anticipates continued expansion of the diagnostic testing market toward approximately USD 280-300 billion by 2035, with growth increasingly concentrated in molecular diagnostics, oncology, genetic testing, preventive screening, decentralized testing, and automated laboratory workflows. Our analysis indicates that the next phase of market expansion will depend not only on increasing testing volumes but also on greater adoption of diagnostics that deliver actionable clinical information.
Our assessment is that the market trajectory will remain highly sensitive to reimbursement, technology adoption, and regulatory execution. The upside case assumes faster reimbursement adoption for novel diagnostics, stronger penetration of liquid biopsy and precision medicine, greater molecular-testing utilization, and accelerated deployment of point-of-care platforms. The downside case assumes persistent reimbursement pressure, slower adoption of premium diagnostics, regulatory delays, and continued price compression across mature laboratory testing.
In our view, the most significant strategic transition is to more clinically actionable tests. Routine testing will remain the volume foundation of the market, but future revenue pools are increasingly likely to favor diagnostics that influence therapy selection, enable earlier disease detection, monitor treatment response, or extend testing beyond traditional laboratory settings. This shift places greater importance on clinical utility, reimbursement support, workflow integration, and the ability to demonstrate measurable value per test.
The full report develops 2030 and 2035 market scenarios and evaluates the outlook for molecular and genomic testing, point-of-care and home-testing penetration, pricing and reimbursement, laboratory automation, future profit pools, technology adoption, and emerging competitive models to identify the factors most likely to shape the next phase of diagnostic testing market growth.
Key Strategic Questions Addressed
- What is the 2026-2036 revenue and test-volume trajectory of the global diagnostic testing market?
- Which diagnostic technologies will capture the largest incremental revenue pools?
- How will point-of-care and decentralized testing reshape laboratory economics?
- Which diagnostic applications offer the strongest revenue and margin potential?
- How will reimbursement and laboratory consolidation affect competitive positioning?
- Where are the largest geographic and application-level diagnostic white spaces?
- Which diagnostic profit pools are most likely to expand through 2036?
Diagnostic Testing Market Segments
By Test Type
- Clinical Chemistry
- Immunoassay
- Hematology
- Coagulation Testing
- Microbiology
- Molecular Diagnostics
- Genetic Testing
- Pathology and Specialized Diagnostics
- Urinalysis
- Other Diagnostic Tests
By Technology
- Polymerase Chain Reaction (PCR)
- Multiplex PCR
- Next-Generation Sequencing (NGS)
- Immunoassay Technology
- Mass Spectrometry
- Digital Pathology
- Automated Diagnostic Systems
- AI-Assisted Diagnostic Interpretation
- Other Technologies
By Application
- Infectious Diseases
- Oncology and Cancer Diagnostics
- Cardiovascular Diseases
- Diabetes and Metabolic Disorders
- Reproductive Health
- Genetic and Inherited Diseases
- Women's Health
- Transplantation Testing
- Pharmacogenomics
- Preventive Screening and Other Applications
By Specimen Type
- Blood
- Urine
- Tissue
- Saliva
- Swabs
- Other Biological Specimens
By Testing Site
- Centralized Laboratories
- Point-of-Care Testing
- Home-Based Testing
- Decentralized Testing Facilities
By End User
- Hospitals
- Independent Diagnostic Laboratories
- Physician Offices and Clinics
- Pharmacies
- Home Healthcare Settings
- Other Healthcare Facilities
By Business Model
- Diagnostic Instrument Manufacturers
- Reagents and Consumables Suppliers
- Laboratory Testing Service Providers
- Specialty Diagnostic Companies
- Integrated Diagnostic Platform Providers
By Region
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
.webp)
 sales@precedenceresearch.com
 Schedule a Meeting