



Lung Cancer Diagnostics Market Size, Key Companies, Trends, Segments, and Forecast 2026-2034
Lung Cancer Diagnostics Market (By Type: Non-small cell lung cancer, Small cell lung cancer; By Test: CA test, HER2 test, ALK test, Angiogenesis Inhibitors, EGFR Mutation test, KRAS Mutation test; By End Use: Hospitals and clinics, Diagnostic Laboratories, Others) - Global Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2034
Source: https://www.precedenceresearch.com/lung-cancer-diagnostics-market
 Get a Sample
 Table Of Content


What is Lung Cancer Diagnostics Market Size?
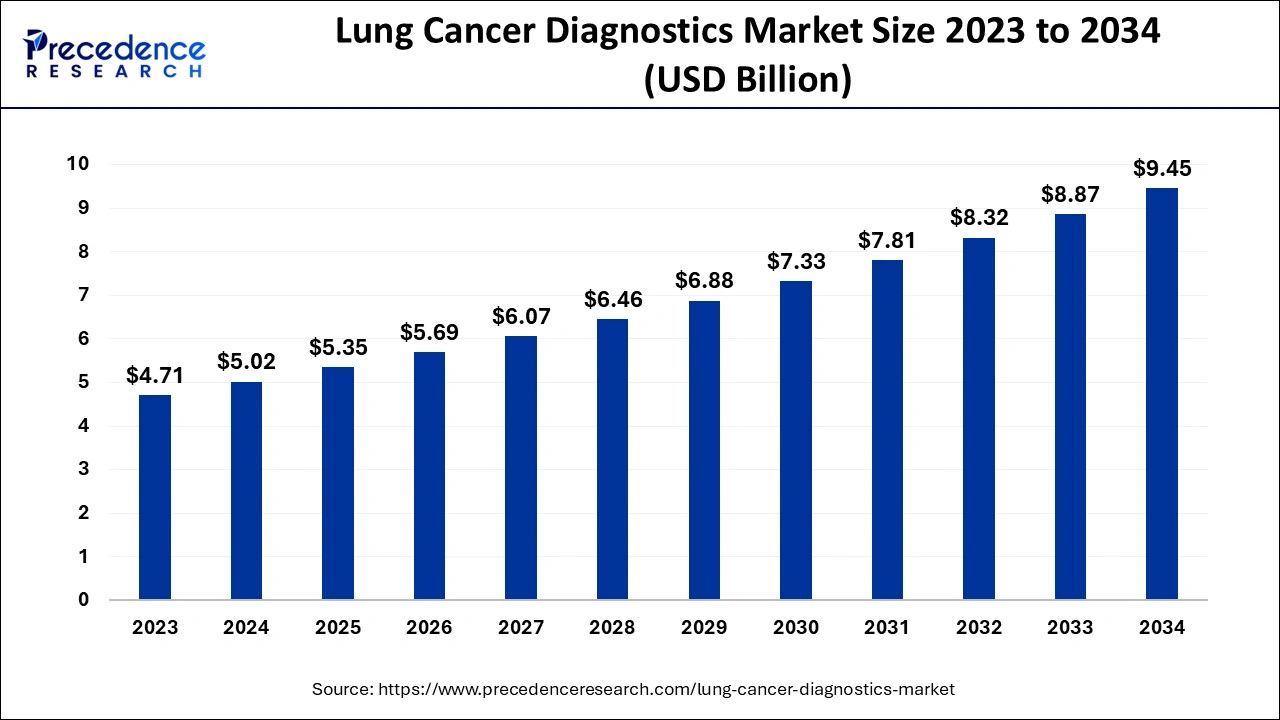
The global lung cancer diagnostics market size was estimated at USD 5.69 billion in 2026 and is projected to reach approximately USD 9.45 billion by 2034, representing a CAGR of 6.53% from 2026 to 2034. Smoking prevalence, increasing awareness of early detection, and advances in diagnostic technologies may influence demand for lung cancer diagnostics. Also, the increasing demand for innovative diagnostic tools and services in imaging technologies like CT scans can fuel market growth further.
Market Highlights
- North America dominated the lung cancer diagnostics market with the largest market share of 47.33% in 2026.
- By type, the non-small cell lung cancer (NSCLC) segment led the lung cancer diagnostics market in 2026.
- By type, small-cell lung cancer (SCLC) is expected to grow at the fastest rate over the forecast period.
- By test, the EGFR mutation tests segment dominated the lung cancer diagnostics market in 2026.
- By test, the HER2 test segment is anticipated to grow at the fastest rate during the forecast period.
- By end use, the hospitals and clinics segment has held the major market share of 49% in 2026.
- By end use, the diagnostic laboratories segment is anticipated to show the fastest growth over the projected period.
Market Overview
Lung cancer develops when abnormal cells grow uncontrollably in the lungs. The two main categories are non-small cell lung cancer (NSCLC) and small cell lung cancer (SCLC). It is mainly caused by frequent exposure to substances like asbestos, cigarette smoke, and air pollution. The two main types of lung cancer are non-small cell lung cancer (NSCLC) and small cell lung cancer (SCLC), which differ in their characteristics and treatment approaches. Symptoms may include shortness of breath, chest pain, persistent cough and, coughing up blood.
Role of AI in lung cancer diagnostics
Artificial Intelligence (AI) can analyze CT scans to detect symptoms associated with lung cancer and analyze a patient's risk of developing lung cancer in the future. AI can also be utilised to help radiologists interpret CT scans. Furthermore, AI can find patterns in DNA fragments in the blood that are related to lung cancer. These applications may support earlier identification of suspicious findings, but diagnosis and treatment decisions require appropriate clinical evaluation and validation.
Lung Cancer Diagnostics Market Growth Factors
- Technological advancements that enhance diagnostic accuracy and enable early detection and treatment are in high demand which can lead to lung cancer diagnostics market growth.
- Increasing adoption of diagnostic methods for non-small cell lung cancer may support market growth during the forecast period.
- Increasing investments in research and development for early screening can drive market growth further.
Lung Cancer Diagnostics Market Outlook
- Industry Growth Overview: Between 2026 and 2034, this market is expected to rise significantly due to the rising cases of lung cancers in various countries along with rapid adoption of AI-enabled diagnostics tools by diagnostics centres for detecting lung cancer.
- Major Investors: Numerous diagnostics companies are actively entering this market, drawn by collaborations, R&D and joint ventures. Various market players such as Illumina Inc, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Agilent Technologies, Qiagen, Abbott, Bio-Rad and some others have started investing rapidly for developing advanced diagnostic tools for examining lung cancer.
- Startup Ecosystem: Several startup brands are engaged in developing advanced diagnostic tools for detecting cancers. The prominent startup brands dealing in lung cancer diagnostics includes DeepHealth, Qure.ai, bioAffinity Technologies and some others.
Market Dynamics
Drivers
Increasing awareness of early detection and screening
As public education campaigns increase awareness about potential risk factors for lung cancer such as environmental pollutants and smoking, people may be more likely to seek preventive healthcare measures, including recommended screening. Additionally, the advocacy efforts by various medical organizations can further optimize awareness prompting medical providers to prioritize lung cancer diagnosis and screening in their practice.
Restraint
Availability of Alternative Diagnostic Methods
The availability of more cost-effective and accessible alternative diagnostic practices can impact market growth negatively. Some potential alternative diagnostic methods are NGS sequencing, Blood-based screening, and Targeted DNA enrichment methods. Lung cancer is sometimes diagnosed at an advanced stage, highlighting the importance of appropriate screening, timely diagnostic evaluation, and access to validated testing.
Opportunity
Increasing Demand for Specialized Diagnostic Solutions
Lung cancer risk generally increases with age, supporting the clinical importance of risk-based screening and timely diagnostic evaluation in eligible populations. The elderly population often witnesses comorbidities and has unique healthcare requirements. Furthermore, the increasing geriatric population in many regions, especially in developed countries creates a lucrative opportunity for lung cancer diagnostics.
Segment Insights
Type Insights
The non-small cell lung cancer (NSCLC) segment led the lung cancer diagnostics market in 2026. The dominance of the segment can be attributed to the increasing need for targeted drug therapy, imaging, and immunotherapy treatment options. NSCLC is further categorised into adenocarcinoma, squamous cell carcinoma and large cell carcinoma. In addition, NSCLC is the most common kind of lung cancer that takes place in people who have a long history of smoking.
The small-cell lung cancer (SCLC) is expected to grow at the fastest rate over the forecast period. The growth of the segment can be linked to the growing technological developments in SCLC treatment options such as bronchoscopy biopsy and imaging. SCLC is further categorized into small-cell carcinoma and combined small-cell carcinoma. A family history of lung cancer may be associated with increased risk, although smoking and other factors also influence lung cancer risk.
Test Insights
The EGFR mutation tests segment dominated the lung cancer diagnostics market in 2026.The dominance of the segment can be credited to the increasing demand for biomarker testing, treatment options and clinical assessment for EGFR. Certain EGFR mutations can drive tumor growth in NSCLC and may inform treatment selection, making EGFR mutation testing clinically important for eligible patients. Moreover, liquid biopsy can provide a less invasive way to identify certain actionable tumor alterations in selected patients with advanced or metastatic lung cancer.
The HER2 test segment is anticipated to grow at the fastest rate during the forecast period. the HER2 test measures the quantity of the human epidermal growth factor receptor 2 (HER2) protein in a cancer cell. HER2 is a protein that controls cell growth and differentiation for normal cell growth. Other treatment solutions like pills that inhibit HER2 from growing in the body are gaining traction among healthcare professionals, leading to segment growth further.
End Use Insights
In 2026, the hospitals and clinics segment led the lung cancer diagnostics market by holding largest market share. The dominance of the segment can be driven by facilities with advanced imaging technologies and superior diagnostic tools offered by hospitals and clinics for precise detection of lung cancer. Furthermore, they also possess multidisciplinary groups of pathologists, radiologists, and oncologists to achieve treatment goals. This segment is the main facility for administering complicated treatments including chemotherapy and surgical procedures.
The diagnostic laboratories segment is anticipated to show the fastest growth over the projected period. The growth of the segment can be linked to the increasing contribution of the laboratories in detecting and treating cancer coupled with the personalised treatment plan offered by them based on the patient profile. The laboratory tests comprise ultrasound, X-rays, MRI & CT scans, and PET scans among others.
Regional Insights
North America's Lung Cancer Diagnostics Leadership Driven by High Healthcare Spending and Early Detection Initiatives
North America dominated the lung cancer diagnostics market in 2026. The dominance of the region can be attributed to the developed healthcare infrastructure, extensive reimbursement regulations, and high healthcare spending for diagnosis of cancer. Moreover, the healthcare industry in the region has experienced an increase in patient pool, due to poor diet habits, unhealthy lifestyles, and growing cases of stage-IV lung cancer in many individuals.
In North America, the United States definitely plays a leading role in this, with government-supported programs like the National Lung Cancer Screening Trial and a growing use of AI-based imaging. According to the CDC, in 2026, lung cancer remained the largest cause of cancer death in the U.S., stressing the importance of early detection, which led to national implementation of low-dose computed tomography of CT screening for high-risk individuals.
U.S. Lung Cancer Diagnostics Market Size and Growth 2026 to 2034
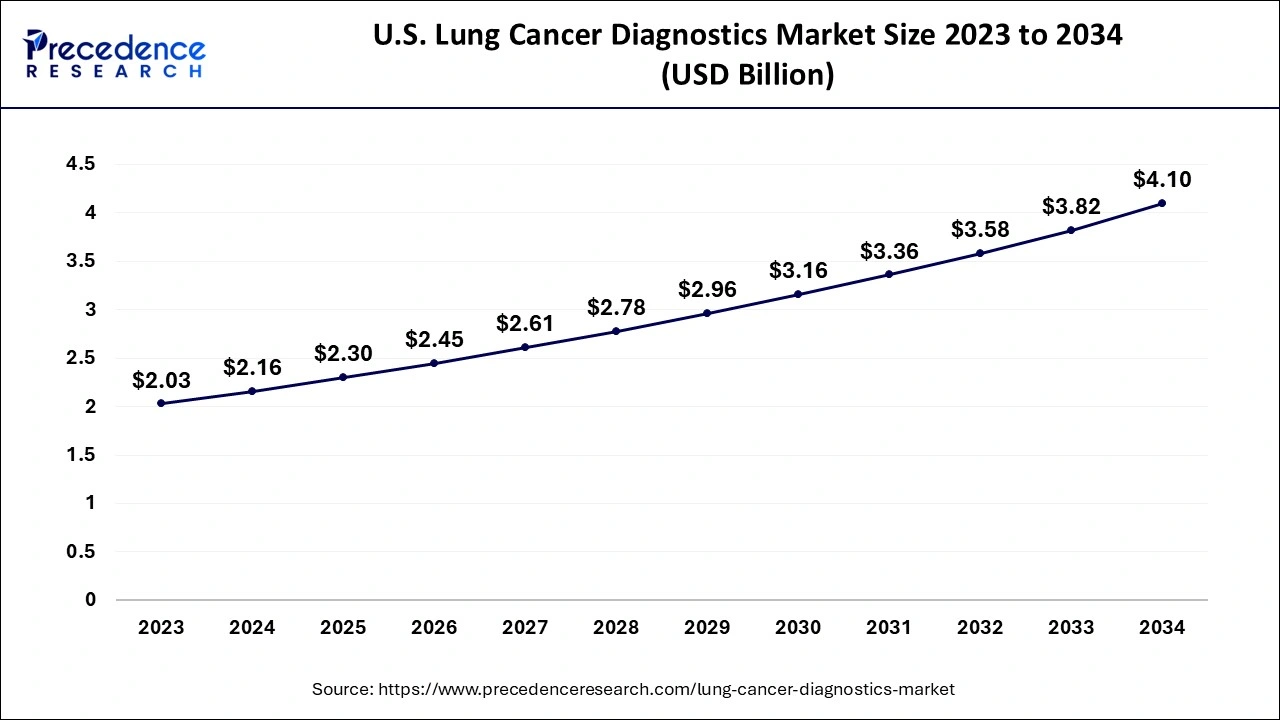
The U.S. lung cancer diagnostics market size is estimated at USD 2.45 billion in 2026 and is expected to be worth around USD 4.10 billion by 2034, growing at a CAGR of 6.62% from 2026 to 2034.
Asia Pacific's Lung Cancer Diagnostics Growth Driven by AI Adoption and Government Healthcare Initiatives
Asia Pacific region is expected to show significant growth over the studied period. The growth of the region can be credited to the increasing adoption of innovative diagnostics technologies and growing prevalence of lung cancer in the region. Furthermore, the market is ready to expand because of awareness programs arranged by healthcare organizations and government for early cancer detection.
Asia Pacific is growing at the fastest rate due to increasing lung cancer incidence, coupled with increased access to diagnostics. In 2026, China is leading the region's effort by scaling its Healthy China 2030 plan, integrating AI-powered tools and CT imaging into the public health system. Pilot programs in cities like Shanghai were helpful in improving early detection Levels. Increased government funding, and local to global partnerships to make diagnostics cheap and much more affordable, especially in semi-urban locations, are all factors contributing to rapid growth across the value of Asia.
Lung Cancer Diagnostics Market Companies
- F. Hoffmann-La Roche Ltd
- Thermo Fisher Scientific
- Illumina Inc
- Agilent Technologies
- Qiagen
- Abbott
- Bio-Rad
- Neogenomics Laboratories
- bioMérieux
- Myriad Genetics, Inc
Recent Developments
- In July 2025, Lunit collaborated with Microsoft. This collaboration is done for developing an AI-enabled cancer detection tool in the U.S.
(Source: https://www.prnewswire.com) - In May 2025, Gene Solutions announced a blood-based cancer testing development. Add the product name, intended use, validation evidence, and direct company announcement before describing it as an AI-powered lung cancer detection test.
- In April 2025, Optellum partnered with Bristol Myers Squibb. This partnership is aimed at developing an AI-enabled lung cancer diagnosis solution.
(Source: https://optellum.com)
Lung Cancer Diagnostics Market Segments
By Type
- Non-small cell lung cancer
- Small cell lung cancer
By Test
- CA test
- HER2 test
- ALK test
- Angiogenesis Inhibitors
- EGFR Mutation test
- KRAS Mutation test
By End Use
- Hospitals and clinics
- Diagnostic Laboratories
- Others
By Region
- North America
- Asia Pacific
- Europe
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
