



Perovskite Solar Cell Market Size, Key Companies, Company Market Share, Power Generation Capacity, Energy Consumption, Pricing Trends, Investment Analysis, Competitive Positioning, and Demand Forecast
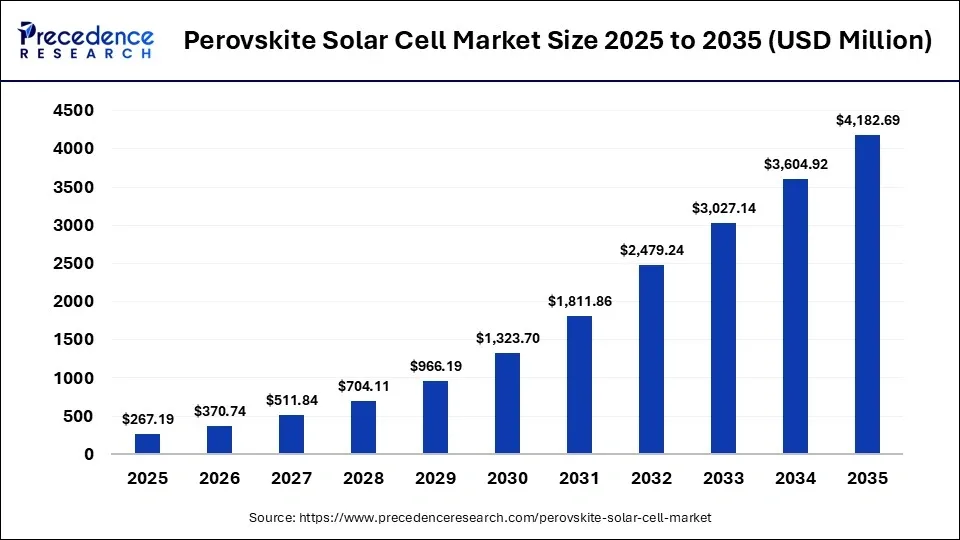
The perovskite solar cell market is worth roughly USD 370.70 million in 2026 and is on track to reach USD 4,182.69 million by 2035, a CAGR of 31.66%. Several things are pushing it forward: perovskite-silicon tandem cells keep getting more efficient, manufacturing is starting to scale, and demand is growing for solar that packs more power into less space. Lightweight and flexible panels are also reaching customers. Tandem modules have passed 24% efficiency, and cells are closing in on 30% and beyond, which makes the commercial case much stronger.
Source: https://www.precedenceresearch.com/perovskite-solar-cell-market
 Get a Sample
 Table Of Content


What is the Perovskite Solar Cell Market Size?
The global perovskite solar cell market size is from USD 370.70 million in 2026 to nearly USD 4,182.69 million by 2035, growing at a strong CAGR of 31.66% from 2026 to 2035.
Overview - Perovskites are Moving from Laboratory Efficiency Records to Commercial Tandem Solar Manufacturing
The market is still young, so current commercial revenue says little about how much this technology matters. Perovskites can take solar efficiency beyond the practical limit of conventional crystalline silicon. At present, the Asia Pacific region is the largest regional market. North America is one of the regions that is expected to see rapid growth in commercialization of the technology.
The key change happening is the transition from single-junction cells to perovskite-based tandems. Commercially, tandem modules are already achieving efficiencies of over 24%, while large-scale prototypes are reaching cell efficiencies of over 30%. The maximum efficiency achievable with perovskite-based tandem cells can theoretically reach 43%, compared to 29-30% with single-junction silicon cells. This advantage is most significant where land costs, grid access, or other balance-of-system costs are high.
Perovskite is not set to replace silicon so much as to add efficiency on top of it. Early buyers are large utility projects, space-limited sites, building-integrated solar, specialty mobility and lightweight uses. What decides success is shifting too: lab efficiency now counts for less than durability, manufacturing yield, encapsulation, lead management, bankability and lifetime energy output.
Key Coverage
- Why tandem is the main route to market
Commercial modules above 24% efficiency, with cells above 30% demonstrated
Asia Pacific's role as the largest manufacturing and demand base
Utility-scale and high-efficiency uses as the first real revenue pool
A close look at commercial readiness, capacity, yield, durability and technology economics
Market Size and Forecast - A Small Current Revenue Pool is Creating a Large Incremental Efficiency Opportunity
That growth comes mainly from new high-efficiency capacity, tandem module launches and uses where extra watts per square meter change the project math, not from replacing the silicon panels already installed. North America and Europe matter because land and labor are expensive there. Asia Pacific matters because of its manufacturing base and the sheer scale of its solar deployment.
The report models base, upside and downside cases. They depend on how fast commercialization moves, how reliable modules prove to be, whether financing is available, how manufacturing yields develop, what policy incentives do, and how quickly established silicon makers add perovskite top cells to their lines.
Key Coverage
- Regional contribution and growth
- Commercial versus pilot-scale revenue
- Tandem versus single-junction economics
- Base/upside/downside scenarios
- Market maturity and commercialization curve
Segmentation Analysis - Tandem Architecture is Becoming the Primary Value Pool
Cell architecture, product form, manufacturing method, application, end-use, and geography divide the market. Tandem cells made of perovskite and silicon are the leading commercial opportunity. The market lets firms retain much of their silicon production while simply adding a perovskite layer on top.
Product form splits the market into rigid and flexible cells, and cell architecture splits it into planar and mesoporous designs. Flexible perovskites earn less today, but they hold considerable long-term potential, especially in lightweight and portable uses.
Utility-scale solar generation is the largest commercial application today, followed by residential and specialty uses, which should grow faster from a smaller base. Building-integrated photovoltaics, lightweight mobility and indoor low-light settings are the next opportunities to open up.
Key Coverage
- Tandem versus single-junction share
- Rigid versus flexible technology
- Planar versus mesoporous architecture
- Utility, commercial, residential, and BIPV
- Aerospace, mobility, and specialty applications
- Revenue, efficiency, and growth by segment
- Segment-level commercialization readiness
Market Dynamics - Efficiency, Land Economics and Manufacturing Yield are Reshaping the Investment Case
The principal growth driver is the economic value of generating more electricity from the same physical footprint. A module operating around 25-27% efficiency can materially improve energy output per square meter relative to mainstream silicon modules, particularly where land and installation costs constrain project economics.
The primary restraint remains durability. Perovskites are sensitive to moisture, oxygen, heat, ultraviolet exposure and operational stress, requiring advanced encapsulation and stability engineering. The industry is therefore shifting from a laboratory metric of peak efficiency toward efficiency × lifetime × yield × manufacturing cost as the real commercialization equation.
In our view, the deciding factor will not be record laboratory efficiency but whether a maker can deliver >25-year bankable performance while achieving high factory yield at competitive $/W.
Key Coverage
- Efficiency economics
- Durability and degradation
- Manufacturing yield
- Silicon compatibility
- Encapsulation requirements
- Lead-management challenges
- Financing and bankability
- Commercialization bottlenecks
Pricing and Cost Analysis: The Real Advantage is Lower System Cost per Watt, Not Simply Lower Cell Cost
Perovskite layers are deposited very thin, which can cut semiconductor material use and opens the door to low-temperature coating, printing or vapor deposition. Even so, early manufacturing costs stay high because of low utilization, small production volumes, yield losses and specialized equipment.
What matters for pricing is $/W at the module and system level, not the cost of the cell alone. Higher efficiency trims spending on land, racking, cabling and other balance-of-system items, and tandem modules can charge a premium for it. That trade works best in utility projects, where non-module costs often make up the large majority of total installed cost.
The full analysis benchmarks module ASP, manufacturing cost per watt, efficiency-adjusted cost, premium versus conventional silicon, yield losses, encapsulation costs, and expected learning-curve effects.
Key Coverage
- $/W module economics
- Efficiency-adjusted pricing
- Manufacturing cost
- Encapsulation and materials cost
- Premium versus silicon
- Balance-of-system savings
- Cost-down trajectory
- Gross-margin potential
Demand-Supply, Value Chain and Technology: Commercial Scale-Up is Becoming the Primary Bottleneck
The supply chain encompasses precursor materials, transport layers, conductive layers, substrates, silicon bottom cells, deposition equipment, encapsulation materials, module assembly, and project deployment. There are opportunities for suppliers of specialist equipment and supplies because the perovskite ecosystem is not yet fully standardized, in contrast to typical PV.
Pilot lines, demonstration plants, and early gigawatt-scale projects continue to disperse industrial capacity. While bigger publicized projects are heading toward multi-gigawatt objectives, several manufacturing operations are aiming for 100-200 MW-class lines, the nominal production.
Technology development is rapidly moving toward slot-die coating, evaporation, inkjet deposition, scalable annealing, advanced transport layers, and tandem integration. Commercially relevant demonstrations have achieved module efficiencies above 24%, while industrial research has reported large-area tandem efficiencies approaching or exceeding 30%.
Key Coverage
- Raw-material and component economics
- Deposition technologies
- Pilot and gigawatt-scale capacity
- Factory yield and utilization
- Tandem integration
- Encapsulation
- Manufacturing equipment
- Technology maturity and patent positioning
Regulation and Sustainability: Lead Management and Lifecycle Performance Will Determine Bankability
Regulators are paying closer attention to lead-containing perovskite formulations, along with recycling, encapsulation, occupational exposure, consumer safety and lifecycle impact. The technology's sustainability case rests on the very small amount of material needed in the active layer, a benefit that has to be weighed carefully against end-of-life handling and disposal.
Certification is now a condition of market entry. Tandem devices must show durability under outdoor exposure, thermal cycling and humid conditions, so their testing path ends up looking much like that of conventional silicon modules.
Key Coverage
- PV certification requirements
- Durability standards
- Lead containment
- Recycling economics
- Lifecycle emissions
- Environmental compliance
- Product warranty requirements
- Bankability criteria
Competitive Landscape: The Market is Splitting Between Technology Specialists and Incumbent Silicon Manufacturers
Winning in perovskite solar now depends less on who builds the best lab cell than on who can make it at scale, protect the technology and earn customers' trust. Four groups of players are emerging. Specialist developers hold the core technology, while tandem-focused manufacturers turn that technology into finished modules. Large silicon producers are working out where perovskite could fit within their existing factory layouts without major disruption. Equipment and materials suppliers sit behind all three groups, providing the tools, chemicals and inputs the others depend on to operate day to day.
Five things increasingly decide a company's standing: efficiency at commercial scale, manufacturing yield, durability, intellectual property and existing PV production infrastructure. Companies that can fold perovskite into a silicon line they already run start with a built-in edge, since the plant, the supply chain and the customer relationships are already in place and paid for.
Commercial evidence is already emerging. Oxford PV shipped 24.5%-efficient tandem modules commercially and has demonstrated 26.9% module efficiency. Its Brandenburg operation represents an early industrialized perovskite-on-silicon manufacturing platform. (oxfordpv.com)
At the other end of the scale-up spectrum, UtmoLight has reported a 150 MW pilot line and a progression toward gigawatt manufacturing, including a reported 0.72 m² module efficiency of 18.1%. (utmolight.com)
As a result, laboratory efficiency, certified module efficiency, pilot capacity and commercially bankable output can differ widely from one company to the next. The full report keeps these indicators apart instead of treating them as interchangeable measures of market leadership.
Tentative Leading Company Universe - 22 Companies Shaping the Perovskite Solar Cell Market
| Company | Headquarters | Market Position | Core Strength | Major Applications / Segments |
| Oxford PV | UK | Commercialization leader | Perovskite-silicon tandem | Utility, residential |
| UtmoLight | China | Scale-up specialist | Large-area perovskite modules | Utility |
| Microquanta Semiconductor | China | Early industrial pioneer | Perovskite modules | Utility, commercial |
| Renshine Solar | China | Technology specialist | Perovskite manufacturing | Utility |
| GCL Perovskite | China | Industrial challenger | Large-scale PV integration | Utility |
| WonderSolar | China | Emerging specialist | Perovskite modules | Utility, commercial |
| Caelux | US | Tandem technology specialist | Perovskite-coated glass | Utility, commercial |
| Tandem PV | US | US manufacturing challenger | Perovskite-silicon tandem | Utility |
| Swift Solar | US | High-efficiency specialist | Lightweight tandem | Utility, specialty |
| Saule Technologies | Poland | Flexible PV specialist | Flexible perovskite | BIPV, IoT |
| Solaronix | Switzerland | Materials specialist | Perovskite materials/cells | Specialty |
| Energy Materials Corporation | US | Technology developer | Perovskite materials/processes | PV |
| Hanwha Qcells | South Korea/US | Incumbent tandem developer | Silicon-perovskite integration | Utility, residential |
| LONGi | China | Global PV incumbent | Tandem R&D and scale | Utility |
| Trina Solar | China | Global PV incumbent | Tandem manufacturing | Utility |
| JinkoSolar | China | Global PV incumbent | High-efficiency tandem | Utility |
| JA Solar | China | PV scale leader | Tandem development | Utility |
| Canadian Solar | Canada | Global PV manufacturer | Advanced PV integration | Utility |
| First Solar | US | Thin-film technology leader | Advanced thin-film PV | Utility |
| Panasonic | Japan | Advanced PV developer | Tandem/next-generation PV | Residential, specialty |
| Toshiba | Japan | Technology developer | Perovskite technology | BIPV, specialty |
| Sekisui Chemical | Japan | Flexible/BIPV specialist | Film-based perovskites | BIPV |
This is a tentative market-specific universe rather than a validated market-share ranking.
Market Share and Competitive Ranking - Revenue Leadership is Still Concentrated in a Small Commercial Base
In light of the market still being in its early commercialization phase, accurate global market shares are less relevant than in mature silicon PV technology. The current leading commercial entities command a large share of the identified perovskite revenues, whereas many firms operate at a pilot or pre-commercial level.
It is for that reason that the study separates commercial revenue share, pilot capacity share, patent strength, and announced manufacturing capacity. It avoids the mistake of ranking a firm with a multi-gigawatt announced facility ahead of suppliers of commercial modules.
Key Coverage
- Top 5 and Top 10 competitive positions
- Commercial revenue share
- Pilot capacity
- Announced capacity
- Efficiency leadership
- Patent positioning
- Commercialization stage
- Share-gain potential
Competitive Benchmarking - Manufacturing Readiness is Becoming More Important Than Laboratory Records
Oxford PV currently represents the clearest commercial reference point, having moved from laboratory development into commercial module shipment. (oxfordpv.com)
Tandem PV provides an important US manufacturing challenger, with a 40 MW annual nameplate demonstration facility opened in California in 2026 and plans targeting high-volume manufacturing later in the decade. (Tandem PV)
Chinese specialists are competing through larger pilot and manufacturing programs, while established silicon manufacturers are leveraging existing HJT, TOPCon, and module infrastructure. Manufacturing-equipment development is also accelerating, with one integrated tandem production solution designed around 200 MW annual capacity per line, demonstrating the industry's movement toward standardized industrial equipment. (PV Tech)
Key Coverage
- Revenue and growth
- Efficiency
- Manufacturing scale
- Yield readiness
- Patents
- RandD
- Geographic reach
- Commercial deployment
Technology and Product Portfolio Benchmarking: Which Perovskite Architecture is Best Positioned to Win the Commercialization Race?
Five perovskite technology routes are taking shape: perovskite-on-silicon tandem, all-perovskite tandem, flexible perovskite, rigid junction perovskite and perovskite-coated silicon modules. They are not all equally close to market, though. Perovskite-on-silicon tandem has moved ahead as the most commercially viable, mainly because it combines perovskite's light absorption with silicon's already-mature manufacturing base. Its theoretical efficiency ceiling of about 43.3% lies beyond anything a single-junction silicon cell can ever reach.
Record lab efficiencies alone no longer settle the question of who leads this market. Developers now have to prove that their modules scale, last and make financial sense over their full life. Tandem has an edge here because it can draw on the proven infrastructure of the silicon PV industry. All-perovskite and flexible designs open up interesting possibilities for later, but they face tougher reliability and manufacturing problems today. Buyers and investors have therefore moved from headline efficiency to module efficiency, degradation rate, manufacturing yield, encapsulation quality and cost per watt, a set of tests that favors approaches delivering real efficiency gains without forcing manufacturers to rebuild entire production lines from scratch.
Over the short to medium term, perovskite-silicon tandem is best placed to gain commercial traction, mainly in utility-scale projects, commercial rooftops, space-limited sites and any setting where extra output per unit of area strengthens the business case. Flexible and lightweight perovskite devices may instead open up newer markets such as building-integrated photovoltaics, the automotive industry and aviation, among others. In the end, it is commercial viability, not lab achievement, that will be the deciding factor in this race.
The report compares these competing architectures across cell architecture, substrate compatibility, tandem arrangement, module architecture, efficiency, flexibility, encapsulation, durability, fabrication process, application suitability, commercial readiness and technical path forward. It also evaluates the cost-per-watt gains that come from efficiency improvements, flags the areas where each technology still needs work, and identifies which architectures are closest to commercialization.
The report also provides a structured database of technology and product details, covering company, technology architecture, cell technology, module technology, reported efficiency, manufacturing process level, substrate, tandem structure, flexibility, encapsulation method, applications, location of operation, capacity, commercialization status and year. With it, users can filter and compare perovskite platforms side by side by technology, company, region and commercialization status, and track how each one has progressed over time.
Application and Geographic Competition - Utility Solar Leads, but Specialty Applications Offer Higher Strategic Differentiation
Utility-scale solar is the primary near-term opportunity because the value of higher efficiency can be directly translated into increased power density and lower land-related costs. Residential applications are attractive where roof area is constrained, while BIPV, mobility, aerospace and low-light indoor applications provide differentiated opportunities where lightweight construction or spectral response matters more than lowest $/W.
Geographically, China remains the center of manufacturing scale, Europe retains strong technology and industrialization capabilities, while the United States is accelerating domestic manufacturing and commercialization. India is emerging as a major future manufacturing opportunity, with recent commercialization agreements targeting multi-gigawatt tandem production.
Recent Indian partnerships include programs targeting approximately 4 GW and additional agreements totaling roughly 10 GW of potential module production, highlighting the country's transition from conventional silicon manufacturing toward next-generation tandem capacity.
Manufacturing and Capacity Benchmarking - The Industry is Moving from Megawatt Demonstration to Gigawatt Ambition
Manufacturing benchmarking evaluates actual operating capacity separately from announced capacity. Current commercial and pilot operations range from tens to hundreds of megawatts, while several developers are targeting gigawatt-scale production.
The key KPI is therefore effective commercial output, combining nameplate capacity, yield, uptime, efficiency and qualification status. A 1 GW plant operating at low yield is strategically less valuable than a smaller facility consistently producing bankable modules.
Key Coverage
- Facility count
- Nameplate capacity
- Effective output
- Utilization
- Yield
- Capacity additions
- Localization
- Vertical integration
- Manufacturing cost per watt
Customer, Channel, and Strategic Development Analysis: Bankability is the Next Commercial Gate
Early customers are likely to be utility developers, specialist power installers and developers of high-efficiency projects. These are the buyers who see real, measurable value in generating more power from a smaller footprint of land or roof. Winning them is hard, though, because the bar is high. Modules need credible warranties, low degradation, acceptance by investors and strong long-term performance, and together these requirements decide whether a project can secure financing and move ahead to construction.
Licensing, manufacturing partnerships and tie-ups with established solar companies are playing a growing role in how the technology reaches customers. A patent license is increasingly the quickest way to get a product to market. One such deal already lets a Chinese manufacturer make and sell perovskite-based solar products in China, backed by the licensor's patents. (oxfordpv.com)
New partnerships also point to a shift from laboratory work toward shared technology development. Large solar projects are being used to test real-world performance before any long-term deals are signed. (Swift Solar)
MandA and Company Profiles - Intellectual Property, Manufacturing Expertise and Ability to Bring Products to Market are the Key Strategic Assets
MandA is still less developed here than in proven technologies, but the logic behind it is becoming clearer. Major solar manufacturers can acquire perovskite intellectual property, while technology companies can gain access to production facilities, manufacturing know-how and established sales channels.
The company profiles cover the 22-company group and examine each firm's revenue, perovskite involvement, RandD and patents, performance records, production sites, output levels, partnerships, technology roadmaps, regions of operation, planned products, revenue plans, investments made, expansion plans and the weaknesses each one currently faces.
Strategic Positioning and Opportunity Analysis - The Winners Will Combine Efficiency, Yield and Bankability
Several distinct competitive archetypes are likely to emerge in this market: commercialization leaders, scale leaders, technology leaders, manufacturing challengers, flexible-PV specialists and incumbent silicon companies.
In the market, the highest value white spaces involve high efficiency utility modules, lightweight modules, BIPV, constrained rooftop applications and emerging markets where land or grid connection economics favor power density. An important opportunity involves combining perovskite top cells with existing TOPCon and HJT manufacturing platforms instead of creating entirely new PV architectures.
Key Coverage
Technology leadership
Scale leadership
Manufacturing readiness
IP strength
Geographic expansion
Utility opportunity
BIPV opportunity
Flexible PV opportunity
Licensing opportunity
Import-substitution opportunities
Industry Structure - Competitive Rivalry is High, but Entry Barriers are Rising
| Force | Assessment | Market-Specific Rationale |
| Supplier Power | Medium | Specialized materials and deposition equipment remain concentrated |
| Buyer Power | Medium–High | Large solar developers demand bankability and competitive $/W |
| New Entrants | Medium | R&D entry is accessible, industrial scale-up is difficult |
| Substitutes | High | Silicon, TOPCon, HJT and other emerging PV technologies compete directly |
| Rivalry | High | Numerous technology platforms are competing for commercialization leadership |
PESTLE and Market Attractiveness - Technology Risk is High, but the Strategic Upside is Exceptional
Political: domestic solar manufacturing incentives and energy-security policies support localization.
Economic: falling solar-system costs and rising electricity demand strengthen the efficiency premium.
Social: demand for low-carbon electricity continues to expand.
Technological: efficiency, durability, deposition, and tandem integration remain decisive.
Legal: certification, lead containment, recycling, and IP protection are critical.
Environmental: lifecycle performance, material recovery, and low-carbon manufacturing increasingly influence procurement.
Overall market attractiveness is assessed as Highly Attractive for technology developers and strategic investors, but Moderate for undifferentiated manufacturers because commercialization risk, capital requirements and competition from rapidly improving silicon technologies remain substantial.
Future Outlook - Perovskite Solar Moves Toward a 2030 Commercialization Inflection Point
Growth is moving more from laboratory scale devices toward certified modules and tandem manufacturing. The upside case assumes durability improves faster than expected, gigawatt-scale manufacturing succeeds, bankability is accepted quickly and module efficiencies approach 30% across commercial products. The downside case assumes slow reliability validation, manufacturing yield problems, limited access to financing and continued cuts in conventional silicon costs.
Our analyst view is that perovskite will complement rather than replace silicon. The strongest near term commercial model is perovskite on silicon tandem technology. Flexible, BIPV and specialty applications offer longer term growth opportunities.
The main competitive question through 2030 will shift from "Who can reach the efficiency?" to "Who can produce high efficiency modules repeatedly at a low cost and with 25 year bankability?
Key Strategic Questions Addressed
- How large is the global perovskite solar cell market in 2025, and how quickly can it exceed USD 1 billion?
- Which perovskite architectures will capture the largest commercial revenue pools through 2030?
- What efficiency threshold is required for perovskite-silicon tandems to achieve compelling project economics?
- How quickly can pilot capacity transition into bankable gigawatt-scale production?
- What manufacturing yield and degradation rates are required for mainstream adoption?
- Which applications can support premium pricing for high-efficiency perovskite modules?
- How will perovskite economics compare with TOPCon, HJT, and other advanced silicon technologies?
- Which companies possess the strongest combination of IP, manufacturing capability, and commercialization readiness?
- Which announced capacities represent genuine production opportunities versus longer-term ambitions?
- Where will the next major perovskite manufacturing hubs emerge?
- How will licensing and strategic partnerships reshape technology ownership?
- Which companies are best positioned to capture utility-scale tandem demand?
- Where are the largest geographic and application white spaces?
- How will durability, recycling, and lead-management requirements affect market adoption?
- What will determine the future winners of the perovskite solar cell market by 2030-2035?
Perovskite Solar Cell Market Segments
By Cell Architecture
- Single-Junction Perovskite Solar Cells
- Perovskite-Silicon Tandem Solar Cells
- 2-Terminal (2T)
- 4-Terminal (4T)
- All-Perovskite Tandem Solar Cells
- Perovskite-Perovskite Tandem Cells
- Other Emerging Architectures
By Product Form
- Rigid Perovskite Solar Cells
- Flexible Perovskite Solar Cells
- Perovskite Solar Modules
- Perovskite-Silicon Tandem Modules
- Perovskite Coated Glass / Laminates
- Custom / Specialty Solar Products
By Technology / Manufacturing Process
- Solution-Based Deposition
- Spin Coating
- Slot-Die Coating
- Inkjet Printing
- Spray Coating
- Vapor-Based Deposition
- Thermal Evaporation
- Vacuum Deposition
- Hybrid Vapor-Solution Processing
- Sheet-to-Sheet Processing
- Roll-to-Roll Processing
- Laser Patterning and Interconnection
- Advanced Encapsulation Technologies
- Other Emerging Manufacturing Processes
By Application
- Utility-Scale Solar Power
- Commercial and Industrial Solar
- Residential Solar
- Building-Integrated Photovoltaics (BIPV)
- Agrivoltaics
- Portable and Off-Grid Power
- Vehicle-Integrated Photovoltaics (VIPV)
- Aerospace and Space Applications
- Indoor / Low-Light Energy Harvesting
- Consumer and IoT Devices
- Other Specialty Applications
By End Use
- Electricity Generation
- Buildings and Infrastructure
- Transportation
- Consumer Electronics
- Industrial and Commercial Facilities
- Agriculture
- Aerospace and Defense
- Remote and Off-Grid Systems
- IoT and Low-Power Devices
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Netherlands
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Taiwan
- Australia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
