
U.S. Behavioral Health Market Revenue, Key Companies, Company Product Portfolio, Diagnostic Testing Volume, Adoption Rates, Pricing Metrics, Supply Chain Performance, Market Share Analysis, and Innovation Trends
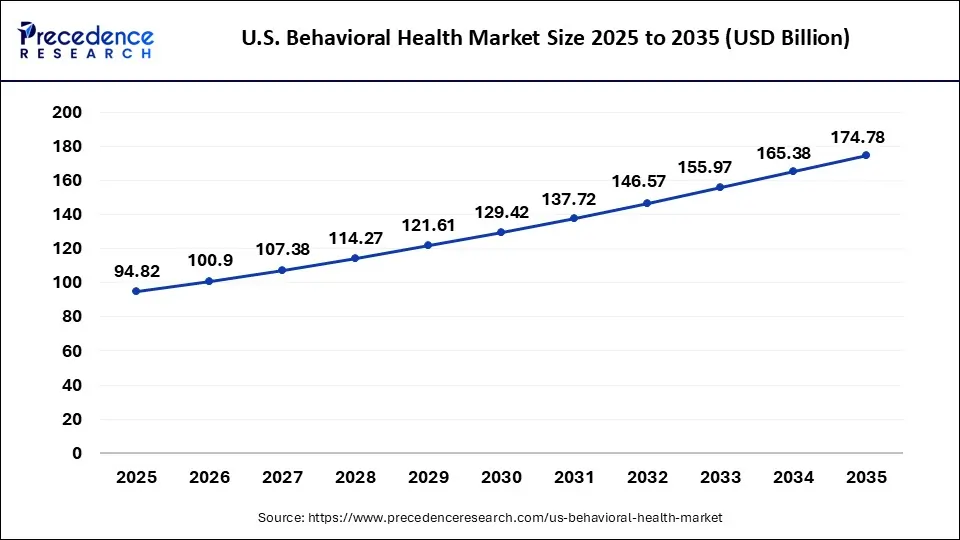
Deepa Pandey, a Healthcare Industry Expert, highlights that the U.S. behavioral health market has reached USD 100.9 billion in 2026 and is on track to reach USD 174.78 billion by 2035, advancing at a CAGR of 6.31%. Key U.S. behavioral health market companies shaping the market include Acadia Healthcare, CuraLinc Healthcare, IBH Population Health Solutions, while major growth segments span by service, by disorder, by end user.
Source: https://www.precedenceresearch.com/us-behavioral-health-market
 Get a Sample
 Table Of Content


What is the U.S. Behavioral Health Market Size?
The U.S. behavioral health market size is projected to grow from USD 100.9 billion in 2026 to USD 174.78 billion by 2035, registering a CAGR of 6.31%, reflecting sustained growth across the broader U.S. mental health market. Growth is driven by the rising prevalence of anxiety, depression, and substance abuse disorders. It is also fueled by expanding adoption of telehealth and digital behavioral health platforms, increasing government funding, and AI-powered mental health solutions. These solutions are improving early diagnosis, personalized treatment, and patient access. The outpatient counseling segment dominated the market in 2025 due to its affordability and accessibility. Home-based treatment services are expected to witness the fastest growth, supported by remote care technologies, virtual therapy, and rising demand for convenient mental healthcare.
Market Highlights
- By Service, the outpatient counseling segment has held the maximum revenue share in 2025.
- By Disorder, the anxiety & depression segment has held the largest revenue share in 2025.
- By End User, the outpatient clinics segment has accounted revenue share in 2025.
Digital Shift and Rising Disorders Drive the Boom in U.S. Behavioral Health
Behavioral health is characterized by the wellbeing of mind, body, and spirit. Behavioral symptoms include low mood, lack of positive emotion, and a range of associated physical, emotional, and cognitive issues, such as substance abuse disorders, personality disorders, depression, or other addictive behaviors, all central to the broader mental health treatment market.
According to SAMHSA's 2023 National Survey on Drug Use and Health, an estimated 22.8% of U.S. adults, or 58.7 million people, experienced any mental illness in the past year. Meanwhile, 23.0%, or 59.2 million people, received mental health treatment during that period, an increase of 3.4 million from the year before. (Source: navisclinical.com, SAMHSA 2023 NSDUH) Therefore, the persistently high prevalence of mental disorders, together with rising demand for substance use disorder treatment, continues to drive the U.S. behavioral health market.
The rise in adoption of digital behavioral health services during the COVID-19 pandemic opened new avenues for key participants in the market. Moreover, the detrimental impact on many people's mental health during the pandemic accelerated the adoption of various technologies to combat the situation. Therefore, improved access to behavioral health care in the U.S., paired with the growing prevalence of mental disorders, continues to fuel market growth. In addition, sustained funding for managing behavioral health issues has had a positive impact on the U.S. behavioral health market. However, gaps in Medicare coverage and inadequate reimbursement for mental care services continue to impede market growth.
Mental disease and drug abuse disorders are both examples of behavioral health illnesses. Mental illnesses are diagnosable conditions marked by persistent and severe changes in thought, emotion, and/or behavior. Substance use disorders are illnesses caused by the misuse of alcohol or other drugs, including prescriptions. People who require behavioral health care may have one or both illnesses, as well as physical co-morbidities.
Mental health is a crucial part of a person's total health. The public commonly thinks of a "healthy individual" as someone free of medical diseases, but a perfectly healthy person is in a state of complete bodily, mental, and social well-being. Furthermore, excellent mental health entails much more than the absence of mental illnesses or disabilities. A wide range of social, biological, and psychological elements all play a role in determining an individual's mental health. External variables, such as stress, socioeconomic situations, prejudice, and violence, are frequently a component of the equation. Individuals with good mental health are more likely to be able to work efficiently, cope with the regular demands of daily life, and contribute to their families and communities.
- In June 2025, legislation to expand Medicaid coverage for behavioral health treatment facilities was introduced by the
U.S. House of Representatives. This bill aims to improve access to behavioral health care nationwide by removing long-standing Medicaid funding restrictions for behavioral health treatment in specific facilities, providing new flexibility for states and communities to meet growing behavioral health needs.
What is the role of AI in the U.S. Behavioral Health Market?
By providing users with insights into their emotional patterns over time, AI in mental health applications empower individuals to cultivate a deeper understanding of their emotions and triggers, equipping them with valuable skills for effectively managing emotions and building healthier responses to challenges. AI has the potential to improve early detection, provide personalized treatment options, and offer support through innovative platforms that may transform how we approach mental wellness, making care more accessible and less stigmatized.
Ethical AI-powered behavioral health tools respect individual autonomy and empower users to make informed decisions about their treatment options. Human oversight is important to ensure that AI interventions complement rather than replace human judgment and agency. AI can provide real-time interventions and improved diagnostic accuracy, ultimately improving the treatment of depression and anxiety.
- In June 2025, the US launch of Wysa Gateway, an AI-powered chatbot designed to streamline how therapy providers and health plans facilitate patient access to care, was announced by Wysa, the global leader in AI-guided mental health support.
Market Trends
Several forces are shaping the broader digital behavioral health landscape and adjacent telehealth mental health services space:
- Technological innovations in digital health technologies
- Increasing healthcare expenditure on behavioral health
- Rising prevalence of mental health disorders
- Changing demographics
- Growing demand for telehealth services
- Rising government funding for mental health programs
- Growing availability of effective treatments
Market Outlook
- Industry Growth Offerings: The market is growing through expanded tele-mental health services, digital therapeutics, integrated care models, and increased investment in addiction treatment, part of a broadly positive behavioral health industry outlook. Rising demand for personalized therapy, employer-backed mental health programs, and technology-driven care solutions further supports market expansion.
- Global Expansion: The market is expanding globally through growing adoption of telehealth platforms, cross-border digital therapeutics, and partnerships with international providers. Increasing awareness of mental health, rising demand for evidence-based care, and technology-driven treatment models support global penetration.
- Startup Ecosystem: The U.S. behavioral health startup ecosystem is expanding with digital therapy platforms, AI-driven diagnostics, virtual counseling services, and tech-enabled addiction treatment solutions, reinforcing momentum across the broader tele-mental health market. This momentum is reflected in the broader digital health funding environment. U.S. digital health startups raised $14.2 billion across 482 deals in 2025, a 35% year-over-year increase and the highest annual total since 2022. AI-enabled companies captured more than half of all funding. (Source: Rock Health, 2025 year-end funding report) Momentum has carried into 2026 as well. Mental-health-focused startups were among the standout raises: telepsychiatry provider Talkiatry closed a $210 million Series D, and hybrid mental health provider Grow Therapy raised $150 million, among the largest deals of the first quarter. (Source: Fierce Healthcare, April 2026)
As per the National Alliance on Mental Illness (NAMI), drawing on data from the U.S. Department of Justice, the Centers for Disease Control and Prevention (CDC), and the Substance Abuse and Mental Health Services Administration (SAMHSA), the following prevalence figures are commonly cited:
Prevalence of Mental Illness in the US
- 1 in 5 US adults experiences mental illness every year
- 1 in 20 US adults experiences serious mental illness every year
- 1 in 6 US youth aged 6-17 experience some kind of mental disorder yearly
- Approximately 50% of lifetime mental illness begins by age 17, and about 75% by age 24
- Suicide is the second leading cause of death among people aged 10-34
More recently, the American Psychological Association's 2025 Stress in America survey found that societal division and disconnection remain significant drivers of poor mental health nationwide. In the survey of more than 3,000 U.S. adults, 62% cited societal division as a major source of stress. Half of respondents reported feelings of emotional disconnection, including feeling isolated, left out, or lacking companionship. The survey also found that adults experiencing high levels of loneliness were far more likely to report chronic health issues, including depression and anxiety disorders, than those with low loneliness levels. (Source: APA, Stress in America 2025)
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 94.82 Billion |
| Market Size in 2026 | USD 100.9 Billion |
| Market Size by 2035 | USD 174.78 Billion |
| Growth Rate from 2026 to 2036 | CAGR of 6.31% |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | Service, Disorder, and End User |
Market Dynamics
Restraint
Limited access to behavioral health services:
Limited access to behavioral health services remains one of the persistent behavioral health access barriers in the U.S. system. It includes the social stigma of mental health treatment and conditions, limited availability of mental health education and awareness, a lack of mental health care professionals and services, and financial barriers to treatment. Untreated mental illness can cause severe emotional, behavioral, and physical health problems. We can experience positive well-being even if we are living with a mental health condition. Having access to effective treatment that helps manage symptoms, along with the presence of safe, stable, and nurturing relationships and environments, can help.
Behavioral health services face several well-documented problems. They often don't work as well for young people, and they are applied unevenly to people in deprived areas. Community treatment orders show clear shortcomings, and racial disparities in how services are used remain shocking. People detained under the Act also don't have enough say in their own treatment. About 60% of people with diagnosable mental health conditions don't get treatment, reflecting a persistent mental health treatment gap nationwide.
Trends in Digital Behavioral Health Marketspace
Employer-focused startups
Employers remain a central focus among leading digital behavioral health firms, with startups such as Lyra Health and Spring Health continuing to expand employer mental health benefits tailored to working professionals. These services include behavioral coaching and advice on how to maintain a healthy work-life balance, forming the backbone of many workplace behavioral health programs. Individuals use these programs, but they also assist employers in providing mental health treatment options for their employees. Behavioral health data and insights are provided by startups in this industry to their employers. They also contain a variety of activities and lifestyle change advice, as well as treatment options.
Telehealth platforms lead the pack
Telehealth has become firmly established as the leading modality for behavioral health delivery, anchoring the broader telepsychiatry market. According to data cited from the American Medical Association, behavioral health leads telehealth adoption among all specialties. 85.9% of psychiatrists report providing virtual video visits weekly, and 56.9% use telehealth for more than 20% of their weekly visits. (Source: SecureVideo, Telehealth Statistics in 2025, citing AMA data)
Separately, a JAMA Psychiatry study analyzing national data found that 27.8% of U.S. adults receiving outpatient mental health care in 2021-2022 received all of their care via telehealth, with another 21.5% using a hybrid model of virtual and in-person care. (Source: Becker's Behavioral Health, November 2025) Platforms specializing in virtual mental health care, such as Talkiatry, Grow Therapy, and SonderMind, continue to gain traction. They bridge the gap between patients and behavioral health professionals, including psychiatrists, psychologists, and counselors, whether through chat, video, or phone-based sessions.
Meditation and sleep-tracking platforms take the spotlight
Platforms that support meditation and sleep tracking remain popular tools within the broader mental wellness apps category, addressing stress, sadness, and insomnia, among other mental health concerns. Calm, a leading entrant in the meditation and sleep app market that reached unicorn status in February 2019, has continued to scale its user base and content library as demand for self-guided mental wellness tools has grown across the broader population.
The intersection of behavioral health and chronic disease management
The overlap between behavioral health chronic disease management and mental health care remains substantial. According to the CDC, about 90% of the nation's $5.3 trillion in annual health care expenditures are for people with chronic and mental health conditions, underscoring how closely intertwined these two areas of care have become. (Source: CDC, Fast Facts: Health and Economic Costs of Chronic Conditions) An aging population and cultural changes are both contributing to a steady rise in these long-term health issues.
Digital behavioral health firms that specialize in treating chronic disease patients have continued to grow in prominence as care increasingly shifts toward remote and hybrid delivery within a broader integrated care model. Companies such as Omada Health and Vida Health remain established players in this space. The broader chronic-condition and behavioral health funding environment has continued to attract substantial venture investment, part of the wider $14.2 billion raised across U.S. digital health in 2025. (Source: Rock Health, 2025 year-end funding report)
Opportunity
Payer-based strategy to provide opportunities for market growth
In the United States, the personal and societal costs of behavioral health disorders, such as mental health and substance abuse, are widely established, large, and growing, creating an opening for a stronger payer behavioral health strategy. Even setting aside the pandemic's lingering effects, the underlying trends are concerning: elevated suicide rates, a sharp rise in drug overdose mortality in recent years, and a shorter life expectancy among persons with serious mental illness. These figures point to a mental health care system that remains under strain and is not yet fully prepared to meet ongoing national demand.
Several system-level barriers hinder access to behavioral health care. There is a nationwide deficit of behavioral health providers, which is unlikely to improve substantially in the next decade. Because of low compensation, many established providers do not join insurance networks, and patients typically decline treatment when faced with high out-of-pocket costs. There are several evidence-based therapies available in behavioral health, but only a few practitioners consistently administer these interventions.
Despite a national need for measurement-based behavioral health care, the use of outcome measures is limited due to a lack of provider adoption and technology infrastructure to measure and report results on a large scale. As a result, a substantial share of Americans with mental illnesses still do not receive treatment. Even when they do, quality isn't consistently measured, and there's reason to believe it's often low.
New solutions are needed to address these issues, and not simply from policymakers and healthcare providers. Payers, whose influence on behavioral health care access has been questioned or condemned, now have a chance to improve the future. Payers have traditionally focused primarily on cutting behavioral health costs, frequently in collaboration with carve-out corporations, contributing to the current inaccessible and fragmented system. However, there is rising awareness of the harmful impact of behavioral health problems on overall health and costs, which is especially important for accountable care organizations (ACOs) and other risk-bearing entities.
As a result, Blue Cross and Blue Shield of North Carolina (Blue Cross NC), a not-for-profit health insurer serving over four million people, has continued a long-term plan to improve behavioral health access, quality, and efficiency. This illustrates a broader shift toward value-based behavioral health reimbursement. Eliminating carve-out, integrating care, raising payment through value-based reimbursement, deploying point solutions at scale, and quantifying effect are the five actions outlined in this plan. This model exemplifies how payment reform can spur the establishment of a flexible and responsive behavioral health system, particularly during times of high demand.
Segments Insights
Service Insights
The outpatient counseling market dominated in 2025. Outpatient counseling is more prevalent due to its convenience, affordability, and greater availability than inpatient facilities. It enables patients to receive professional help without leaving home. This treatment model is popular for cases of anxiety, depression, and eating disorders, and it is used where long-term hospitalization and constant supervision are not needed.
The home-based behavioral health segment is expected to experience the fastest growth. As the reach of telehealth and digital health platforms increases, home-based behavioral health services are expanding in popularity. New online counseling options, including video calls, virtual group therapy, and mobile applications, are providing greater access and convenience to treatment.
Disorder Insights
Growth in the anxiety and depression treatment market accounts for the largest share of the market, as mental health becomes a growing concern amid social pressure, isolation, and stressful life events. Increasing awareness of mental health, a higher incidence of diagnosis, and ongoing research and advancement in behavioral health treatment are stimulating demand for behavioral healthcare services. Early detection and increased accessibility to therapy are additional drivers of segment growth.
The substance abuse treatment market is expected to experience the fastest growth. The alcohol, opioid, and marijuana use segments will be a key growth area, likely to expand as misuse of these substances continues to rise. Increased awareness of addiction treatment and an expanding number of rehabilitation centers are driving demand for behavioral health services.
End User Insights
The outpatient mental health clinics segment dominated the market in 2025, as many patients suffer from mild to moderate behavioral health issues that are not severe enough to require hospitalization. These clinics offer patients access to affordable and useful treatments. Other factors, such as behavioral health integration into primary healthcare and increasing use of telepsychiatry, are also enhancing the diagnostic, treatment coordination, and patient care experience.
The home care behavioral health segment is expected to grow at the fastest CAGR. Patients are increasingly seeking behavioral healthcare at home, and home care is on the rise. New remote monitoring technologies, wearable devices, online support systems, and virtual consultations are making treatment more convenient and safer. The increasing shift toward digital healthcare solutions among providers and patients is fueling robust demand for home-based care.
Government Initiatives
- Costing Privilege: Precision in Medicare behavioral health reimbursement operations has spread awareness of reimbursement policy through new billing codes. Different codes have been developed for various conditions, highlighting the business side of medical billing. The popular RCM process promoted by healthcare companies underscores the high-end performance and role of these codes. Efforts by state and federal programs around these new billing codes help specialists and suitable therapists bill Medicare. This enables the continuation of mental health therapies in the medical space, treating it as a central part of an individual's good mental state and wellness.
- Promote wellness: Mental health awareness programs and strong investment in federal initiatives through SAMHSA represent a meaningful contribution by regional government. The Mental Health Parity and Addiction Equity Act reinforces a broader mental health parity policy signaling strict physical and mental care oversight across both private and public sectors.
- Robust Infrastructure: Supportive infrastructure is like making space for healing. Coordinating programs like Homekey promise substantial funding for home-based therapy beds and housing support for disturbed and stressed individuals.
- Support to Telehealth: Medicare telehealth continues to be a boon to homecare trends. Acceptance by legal authorities has enabled substantial expansion of this market, with remote behavioral health sessions gaining efficiency under this legal permission.
Collaboration Landscape
- Effective Alliances: The combination of consulting psychiatrists, behavioral care managers, and primary care doctors brings momentum to mental and physical health treatment, a hallmark of the broader integrated behavioral health care approach. This alliance sets a standard of care built around a single mission of detecting and treating mental disorders at the earliest possible point.
- Digitization Addition: Collaboration with digital platforms and health charts not only frames a routine timetable but also manages payments and technology pattern integration, reinforcing the wider collaborative care model taking hold across the industry.
Strategic Growth Opportunities
- High Growth Commercial Opportunities: Flexible display and visual component commercialization, along with modern home care settings, fuel both display footprint and remote care, expanding the reach of the broader digital therapeutics market. This paves the way for modern mobile devices to meet health needs. The promotion of emerging partnerships is a benefit to the respective medical settings tied to each partner's native professional identity.
- Emerging Technology Opportunities: The technological advantage involves software development and AI mental health technology intervention in the clinical process and costing department. The cloud advantage and chatbots represent a strong business strategy for tech expertise in this market.
Value Chain Analysis
The following stages reflect the broader behavioral health drug development pipeline and the surrounding behavioral health regulatory compliance landscape:
Clinical Trials
- Clinical trials in U.S. behavioral health focus on evaluating new therapies, preventive approaches, and treatment methods for mental and behavioral disorders.
- These studies help determine the safety, effectiveness, and real-world impact of drugs, devices, and therapeutic interventions.
They play a vital role in advancing care for conditions such as depression, anxiety, addiction, and personality disorders. - Key Players: National Institute of Mental Health (NIMH), NIH, FDA, Johnson & Johnson, Pfizer, AbbVie, Eli Lilly.
Formulation and Final Dosage Preparation
- Formulation and dosage development for U.S. behavioral health drugs focuses on ensuring optimal effectiveness, safety, and stability while meeting strict FDA standards.
- The industry is shifting toward personalized treatment options and innovative delivery systems to improve patient outcomes and adherence.
Modern approaches aim to address limitations of conventional formulations, such as slow onset or poor tolerability. - Key Players: Johnson & Johnson, Eli Lilly, Pfizer, AbbVie, Bristol Myers Squibb, FDA, NIH.
Regulatory Approvals
- U.S. behavioral health regulatory approvals require navigating a layered framework of federal and state rules that differ by service type, provider category, and technology used.
- Compliance areas include state licensing requirements, federal standards such as HIPAA and mental health parity laws, and FDA oversight for digital and clinical products.
These regulations ensure patient safety, data protection, and quality of care. - Key Players: FDA, SAMHSA, CMS, State Health Departments, ONC.
Top Vendors and their Offerings
- Acadia Healthcare: Acadia Healthcare provides inpatient and outpatient behavioral health services, including treatment for mental illness, addiction, mood disorders, and trauma. It operates specialty hospitals, residential programs, and comprehensive care centers across the U.S.
- CuraLinc Healthcare: CuraLinc Healthcare offers employee-focused behavioral health solutions, including EAP programs, mental wellness support, substance-use management, and digital therapy tools. Their services emphasize early intervention, care coordination, and improved access to behavioral health resources.
- IBH Population Health Solutions: IBH delivers integrated population health and behavioral health services, including EAP programs, telehealth counseling, substance abuse support, and wellness management. They focus on personalized care, data-driven interventions, and improving mental health outcomes for organizations.
- Universal Health Services (UHS): UHS operates one of the largest behavioral health networks in the U.S., providing inpatient psychiatric care, outpatient therapy, addiction treatment, and specialty behavioral programs for children, adults, and seniors through hospitals and treatment centers.
- Behavioral Health Group, Inc.: BHG focuses on opioid addiction treatment through medication-assisted therapy, counseling, and recovery support. Its clinics provide methadone, buprenorphine programs, and integrated behavioral health services to support long-term recovery and patient stabilization.
Challenges to Implementation of Telehealth
| Level | Additional Challenges |
| Individual client and provider | Increasing access to and comfort using telehealth |
| Interpersonal client-provider relationships |
|
| Organizational |
|
| Regulatory and reimbursement environments | Complying with federal, state, and local regulations |
Key Benefits for Patrons
Strategic Growth Opportunities
This behavioral health market research covers the following:
- The study provides an in-depth analysis along with the current trends and future estimations of the U.S. Behavioral Health market to elucidate imminent investment pockets.
- A comprehensive behavioral health industry analysis of the factors that drive and restrict market growth is provided.
The quantitative analysis of the industry from 2016 to 2027 is provided to enable stakeholders to capitalize on prevailing market opportunities. - An extensive analysis of the key segments of the industry is provided to understand the profitability of the various types of products.
- The key players and their strategies are analyzed to understand the competitive outlook of the market.
Recent Developments
- In April 2026, Optimi Health launched an Ibogaine Initiative to extend its Health Canada-licensed GMP platform for manufacturing and supplying ibogaine. This development coincides with the U.S. taking initial steps toward a federal policy framework focused on psychedelic drug research and access. (Source: https://investingnews.com)
- In June 2025, Wysa launched Wysa Gateway, an AI chatbot, in the US to enhance mental health patient intake. It automates clinical screenings, offering a quicker, precise, and tailored access route to therapy for providers and health plans. (Source: https://www.businesswire.com)
- In August 2025, the U.S. launch of ZILOY, a GenAI-powered integrative mental health platform developed by wholly owned subsidiary QuantumNexis, was launched by Healthcare Triangle, Inc., a leader in digital transformation solutions, including managed services, cloud enablement, and data analytics for the healthcare and life sciences industries.
- In December 2024, Youth Mental Health Tracker, backed by SHOWTIME/MTV, Melinda Gates, was launched by Surgo Health. The tracker highlights youth mental health across the U.S. through data, stories, and surveys. A related white paper offers recommendations for policymakers.
Segments Covered in the Report
By Service
- Home-Based Treatment Services
- Outpatient counseling
- Emergency mental health services
- Inpatient hospital treatment
- Intensive care management
By Disorder
- Bipolar Disorder
- Anxiety Disorder
- Depression
- Post-Traumatic Stress Disorder
- Eating Disorder
- Substance Abuse Disorder
- Others
By End User
- Outpatient Clinics
- Hospitals
- Rehabilitation Centers
- Homecare Setting
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
.webp)
 sales@precedenceresearch.com
 Schedule a Meeting