
U.S. Home Healthcare Market Size, Procedure Volume, Healthcare Spending, Technology Adoption, Reimbursement Analysis, Cost Structure , and Growth Outlook
U.S. Home Healthcare Market (By Type: Device, Services; By Device: Diagnostic & Monitoring Devices, Therapeutic Devices, Home Mobility Assist Devices; By Services: Rehabilitation, Telehealth, Respiratory Therapy, Infusion Therapy, Unskilled Homecare) - Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2035
Source: https://www.precedenceresearch.com/us-home-healthcare-market
 Get a Sample
 Table Of Content


What is the U.S. Home Healthcare Market Size in 2026?
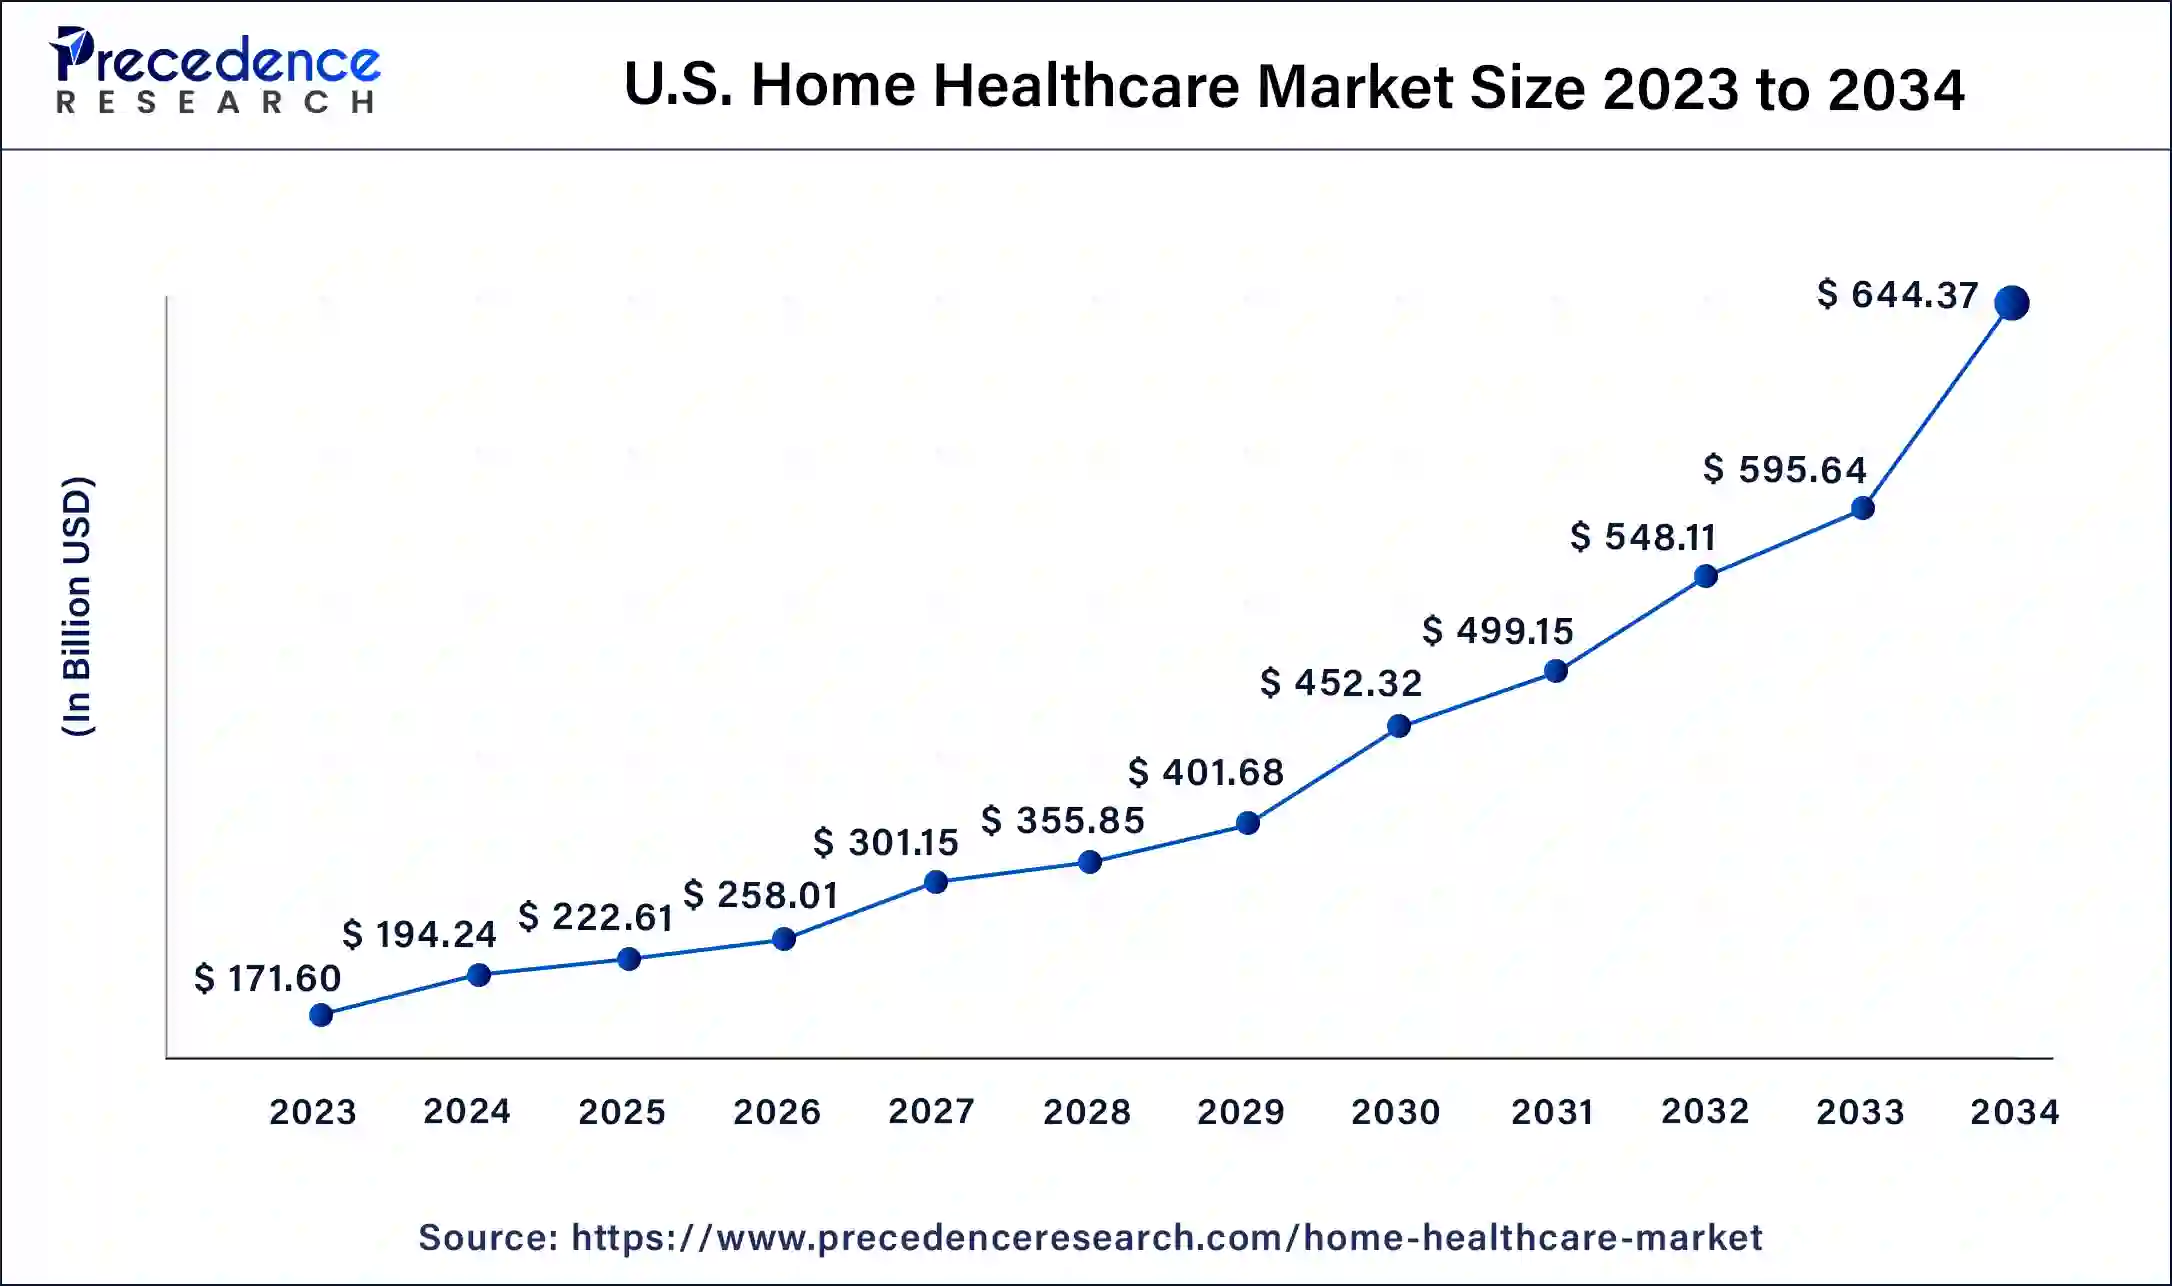
The U.S. home healthcare market size is calculated at USD 222.61 billion in 2025 and is predicted to increase from USD 258.01 billion in 2026 to approximately USD 692.30 billion by 2035, expanding at a CAGR of 12.01% from 2026 to 2035. There is a growing importance of home healthcare for America's elderly population due to rising chronic disease prevalence, an aging population, and increasing healthcare costs that reshape care delivery.
Key Takeaways
- By types, the services segments hold a significant market share of 52.4% in 2025.
- By devices, the home mobility assist devices segment has held the largest market share of 39.96% in 2025.
- By services, the rehabilitation segment captured the biggest revenue share of 55.06% in 2025.
Market Overview
A various range of medical services is provided at home for injury and illness by home healthcare. Home healthcare main advantage is that it is less expensive, more convenient, and as effective as hospital-based or nursing care. There is significant growth in the geriatric population in the U.S. As the geriatric population increases there is an increase in age-related disorders, such as diabetes, osteoarthritis, and dementia. Sedentary lifestyles and excessive alcohol intake are factors contributing to the rise in the incidence of lifestyle illnesses. During the projected period, the market is likely to be driven by the rising prevalence of target illnesses. For instance, according to the American Heart Association, around 83.6 million individuals in the United States suffer from one or more forms of cardiovascular illnesses, with approximately 42.2 million persons over 60.
How can AI Impact the U.S. Home Healthcare Market?
AI-powered algorithms help in the analysis of massive medical databases to diagnose diseases early, support clinical decision-making, and tailor treatment plans. AI is transforming the medical industry by optimizing treatment plans, improving diagnosis accuracy, and streamlining healthcare processes. AI enhances diagnostic accuracy in pathology, radiology, ophthalmology, and dermatology by analyzing images using deep learning algorithms. AI improves healthcare operations through AI-powered virtual assistants, robotic-assisted surgeries, and electronic health record automation.
U.S. Home Healthcare Market Trends
- The increasing prevalence of chronic diseases in the U.S. is driving the market. Conditions such as diabetes, heart disease, and respiratory disorders necessitate ongoing care and monitoring, which can be effectively managed at home.
- Technological advancements are transforming home healthcare service delivery, with innovations like telehealth platforms, remote patient monitoring devices, and mobile health applications enhancing providers' ability to deliver care directly to patients' homes.
- As the number of elderly individuals in the country increases, there is a rise in the demand for services tailored to this demographic. This highlights the necessity for specialized care that accommodates the unique and complex needs of older adults.
- Patients and families in the region are increasingly recognizing the financial benefits of adopting home-based care compared to traditional hospital settings. This shift is prompting healthcare systems to expand their home-based service offerings.
- There is a rapid surge in demand for services that emphasize preventive measures, such as health screenings and wellness programs, potentially reducing overall healthcare expenditures.
Market Outlook
- Industry Growth Overview: The U.S. home healthcare market continues to see massive growth due to a rapid shift of providers and patients to home health options. Patients look for favorable opportunities for convenient, personalized care in a comfortable setting. Providers look for the benefits of aging in place, hospital at home, preventive care, and at-home health tech.
- Sustainability Trends: The sustainability efforts focus on achieving goals by supporting efficiency due to the growing environmental awareness within the healthcare sector. It will create a new avenue for savings and benefit communities. Sustainability is embraced in healthcare across a health and hospital system enterprise. It is embraced in operations, purchasing, procurement, maintenance, and new models of care.
- Startup Ecosystem: Startups across the U.S. home healthcare market include businesses that aim to transform the face of healthcare services. Some of these businesses also work collaboratively with private and government insurers. They make efforts to simplify the process for patients as a key part of their business strategies.
- Global Expansion: It is accelerated by the key benefits of home healthcare for elderly and medically fragile patients. It is expected that personalised home health nursing will improve quality of life with cost-effective care at home. Home care is chosen over hospitalization due to the lower risk of hospital-acquired infections, better cost-effectiveness, higher patient satisfaction, autonomy, and empowerment.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 222.61 Billion |
| Market Size in 2026 | USD 258.01 Billion |
| Market Size by 2035 | USD 692.30 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 12.01% |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | Type, Device, Services |
Market Dynamics
Drivers
Rapid growth in the elderly population
As the aging population is more prone to chronic diseases, this increases the demand for healthcare as well as the burden on the government and health systems. For instance, according to the United Nations Department of Economic and Social Affairs, there were 703 million individuals aged 65 and over in the world in 2019; by 2050, this amount is predicted to rise to 1.5 billion. Furthermore, the number of individuals aged 80 and up is expected to increase by 2050, from 143 million in 2019 to 426 million. T the unnecessary hospital admission and readmissions and the time and cost involved in traveling to meet healthcare professionals are reduced due to home healthcare.
Rising incidence of chronic diseases
Chronic illness is a long-term illness that can be managed but not cured. Chronic illness treatment and management have become a serious problem. Approximately half of all home healthcare patients have at least one chronic condition, and this figure is anticipated to rise in the coming years. Chronic illnesses, which disproportionately impact older persons, lead to disability, lower quality of life, and raise long-term care expenditures, creating an array of potential for various home healthcare organizations.
As healthcare expenses rise, there is a greater demand for cost-effective healthcare delivery
The key factor driving the adoption of services for homecare settings during the forecast period is the increasing healthcare expenditure in the U.S. For instance, according to an article published in 2021, by the American Journal of Managed Care (AJMC), the cost reduction in home healthcare management in a recent randomized trial was 19%. Further, the market will be boosted by the growing demand for respiratory therapy services and infusion services at home.
Restraints
Concerns regarding patient safety
The nurse-physician relationship in-home care entails less face-to-face interaction, and the nurse is responsible for performing evaluations and conveying results. This aspect influences patient safety and outcomes. Another distinguishing feature of home healthcare is that professionals provide medical treatment to each patient in his or her own location. However, there may be external aspects that pose dangers to patients that are difficult to exclude. To handle such incidents, hospitals have well-equipped environmental safety departments.
Opportunities
Telehealth's rising popularity and unexplored developing regions
The fast increase in the global elderly population, the growing incidence of chronic illnesses (including COPD and asthma), and the cost benefits of home care equipment and services (in comparison to hospital visits) are the primary factors driving the growth of the home healthcare industry. COVID-19 has resulted in a significant increase in the usage of telehealth. Consumer usage has skyrocketed, with 11 percent of US consumers adopting telehealth in 2019 and 46 percent currently using telehealth to replace canceled healthcare appointments.
In April 2025, ScienceSoft released proprietary research exploring the adoption of telemedicine in the United States. the report estimates that, by the end of 2026, around 30% of all medical appointments in the United States will be via telemedicine technologies. The research has shown the adoption of telemedicine by different medical specialties, with mental health leading the way (38.3% of all mental health encounters were done via telehealth in 2024). 78.6% of hospitals in the U.S. have installed a telemedicine solution.
Challenges
Shortage of home care workers
Home healthcare is a booming industry, with a high need for home care providers/workers. According to the US Bureau of Labor Statistics' employment predictions for 2014-2024, home healthcare occupations such as personal care aides and home health aides are among the top ten. As the demand for home healthcare increases the demand for workers also increases.
Segments Insights
Type Insights
The services segment dominated the US home healthcare market with a revenue share of 52.4% in 2025. Healthcare services offered to patients at home depend on their diagnosis and according to care plans outlined by their physician. Services can range from doctor and nursing-based care to physical, occupational, and speech therapy or specialized medical services. The demand for home healthcare services has grown rapidly in the United States due to the country's growing elderly population. According to projections by the US Census Bureau, the number of people aged 65 and above is likely to reach 83.9 million by 2050, nearly double that in 2012. Nursing is the most commonly utilized home healthcare service, especially for elderly adults. Nursing care includes the provision of services such as medicine administration, wound dressing, ostomy care, and monitoring patient vitals.
The devices segment is projected to expand rapidly in the market in the coming years. A home medical device is intended for use in a non-clinical environment and is usually managed, at least partially, by the user. Rising hospitalization costs in the United States and a shortage of care facilities are putting pressure on the medical infrastructure and compelling individuals to opt for home-based healthcare options. Even complex devices such as dialysis machines and ventilators are being retrofitted to operate at home.
Device Insights
The diagnostic and monitoring devices segment dominated with a revenue share of 30.04% in 2025. Diagnostic and monitoring devices cover a wide range of equipment, including testing kits for measuring different chemicals and parameters in blood or urine and various types of meters and monitors for keeping track of specific vitals such as pulse, oxygen levels, etc. Standard diagnostic and monitoring devices include thermometers, blood pressure cuffs, glucometers, and pulse oximeters. Home healthcare usually involves monitoring one or more critical patient parameters to deliver timely and accurate medicine administration.
By device, the home mobility assist devices segment is predicted to witness significant growth in the US home healthcare market over the forecast period. An impending rise in the geriatric population in the country over the next few years is expected to drive demand in this segment. Mobility assist devices ease the burden of caregiving by creating a safer, more accessible environment for the sick, disabled, and aged. They make daily tasks more manageable for those with mobility, hearing, and vision impairments.
US Home Healthcare Market, By Devices, 2020-2023 (USD Billion)
| Devices | 2020 | 2021 | 2022 | 2023 |
| Diagnostic & Monitoring Devices | 6,703.8 | 7,614.5 | 8,515.3 | 9,607.0 |
| Therapeutic Devices | 6,670.2 | 7,585.6 | 8,493.3 | 9,593.6 |
| Home Mobility Assist Devices | 9,304.6 | 10,420.7 | 11,489.7 | 12,780.1 |
By Services
The rehabilitation segment accounted for a considerable revenue share of 55.06% in 2025. Rehabilitation services are a crucial part of healthcare and aim to enable children, elders, and adults with disabilities to operate as independently as possible and participate in society through work, education, recreation, etc. According to the World Health Organization, an estimated 2.4 billion people globally currently live with a condition that can benefit from rehabilitation. Demand for rehabilitation is fueled by demographic changes in the world population with increasing number of people living longer and a higher instance of chronic illness and disability.
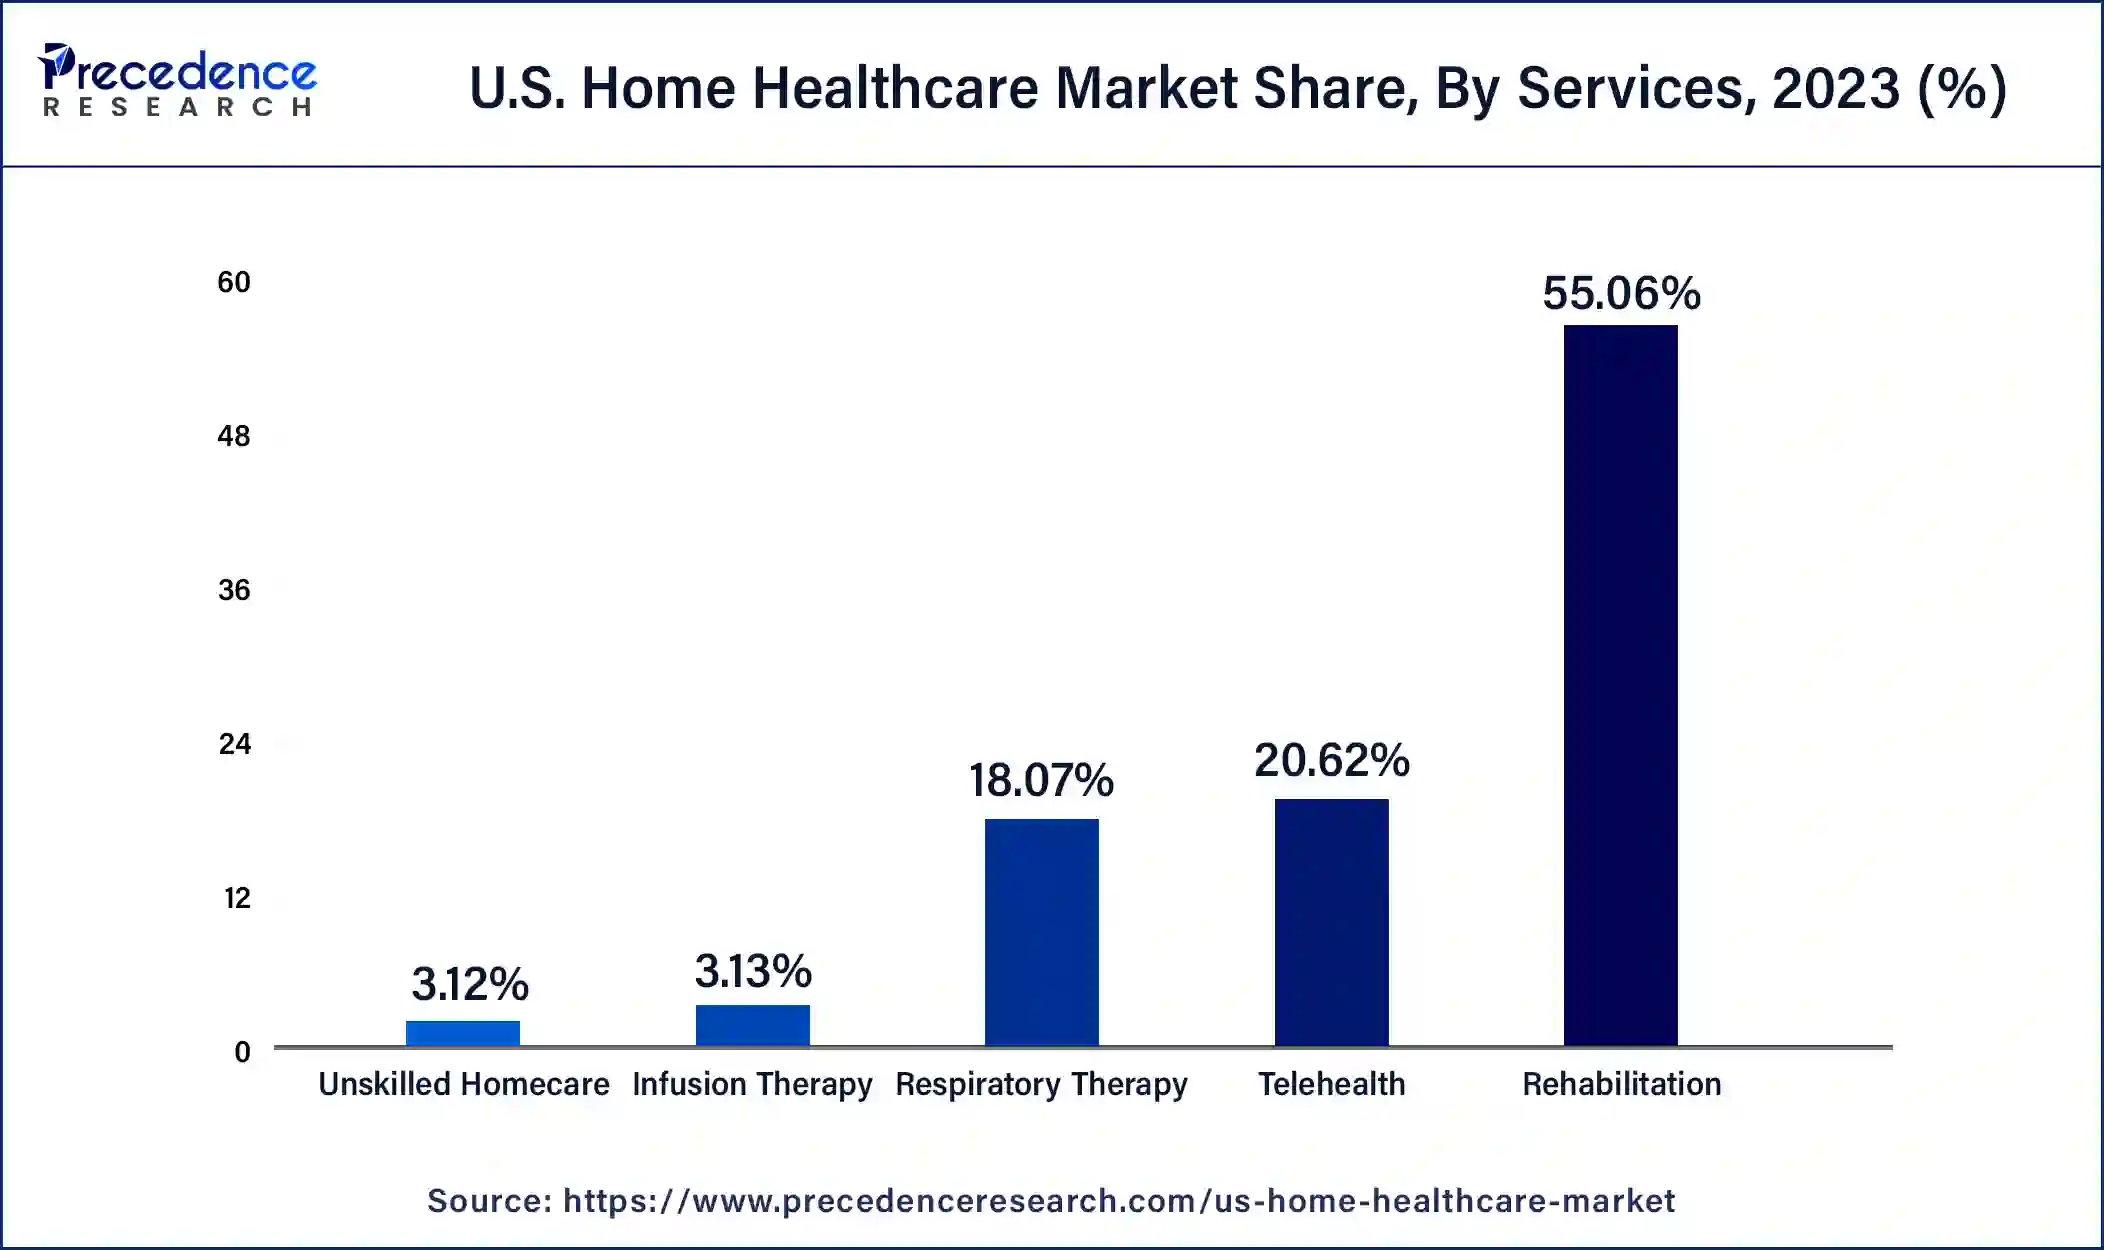
By services, the telehealth segment is expected to gain a significant market share from 2026 to 2035. Demand for telehealth services surged during the pandemic, offering several benefits to medical staff and patients, such as improving care delivery, patient outcomes, and preventive care. Telehealth services include palliative care, chronic disease management, transitional care, mental health, and more.
US Home Healthcare Market, By Services, 2020-2023 (USD Billion)
| Services | 2020 | 2021 | 2022 | 2023 |
| Rehabilitation | 37,118.8 | 41,169.9 | 44,951.2 | 49,508.6 |
| Telehealth | 11,604.2 | 13,698.3 | 15,882.2 | 18,537.4 |
| Respiratory Therapy | 12,101.7 | 13,451.6 | 14,719.6 | 16,248.7 |
| Infusion Therapy | 2,048.0 | 2,293.7 | 2,529.1 | 2,813.6 |
| Unskilled Homecare | 2,123.6 | 2,348.7 | 2,557.0 | 2,807.8 |
Country-Level Analysis
The US home healthcare market is witnessing strong growth, fueled by a growing aging population and a rising preference for in-home care services. As more individuals aim to maintain independence and quality of life, demand for healthcare services delivered at home continues to expand nationwide. This trend is further supported by technological advancements and the optimization of remote monitoring and telehealth solutions, enabling providers to deliver effective care without requiring in-person visits.
There is a strong emphasis on cost-effective healthcare solutions, which is encouraging both patients and healthcare providers to explore more home-based alternatives, as they are more affordable than traditional hospital care. Moreover, the country's supportive and robust regulatory environment is supporting the expansion of home healthcare services. Various policies aimed at enhancing access to care and improving reimbursement models are underway, encouraging more providers to enter this market.
Supply Chain Analysis
R&D
- In this stage, the R&D focus areas are agentic AI, advanced remote monitoring, point-of-care diagnostics, and hyper automation and integration.
- Key Players: Medtronic, Abbott Laboratories, Koninklijke Philips N.V., ResMed Inc., Honor Technology, Adaptive Health, the Helper Bees, etc.
Distribution to Hospitals, Pharmacies
- In this stage, the core distribution network is designed to handle manufacturing inputs in bulk amounts and transform them into facility-level shipments.
- Key Players: McKesson Corporation, Cencora, Cardinal Health, Inc., CVS Health, Walgreens Boots Alliance, UnitedHealth Group, Medline Industries, LP, and Owens & Minor, Inc.
Patient Support and Services
- This stage prioritizes digital patient onboarding, in-home comprehensive assessment, collaborative care planning, service delivery, remote monitoring, and value-based discharge.
- Key Players: Maxim Healthcare, CenterWell Home Health, Amedisys, Inc., BAYADA Home Health Care, UnitedHealth Group, Kaiser Permanente, etc.
Competitive Landscape
The U.S. home healthcare market is driven by favorable reimbursement, hospital-at-home models, AI and remote patient monitoring, cost-effectiveness, etc. The top home healthcare service providers are UnitedHealth Group, Humana, Encompass Health, Enhabit Home Health & Hospice, BAYADA Home Health Care, and Home Instead. Moreover, the top companies in medical equipment and infrastructure are Medtronic, Abbott Laboratories, ResMed, Koninklijke Philips, Cardinal Health, and McKesson. Medical equipment and device manufacturers are Medtronic plc, Abbott Laboratories, Fresenius Medical Care, GE HealthCare Technologies Inc, and Cardinal Health, Inc.
Clinical and personal care service providers are UnitedHealth Group, LHC Group, BAYADA Home Health Care, Home Instead, and Encompass Health Corporation. R&D efforts focused on optimizing operations through AI and cloud integration, and building remote monitoring and wearable systems. The medical device and smart hardware leaders heavily invest to scale smart infusion pumps, continuous glucose monitoring, and remote patient monitoring equipment.
Top Companies and Their Offerings
- ResMed Inc.: ResMed Inc. provid 2024, Masimo announced FDA clearaes a comprehensive portfolio for the US home healthcare market aimed on sleep apnea and COPD treatment, thus, combining cloud-connected devices, masks, as well as digital health software. Their solutions involve AI-driven monitoring and SaaS platforms to enhance patient compliance and provider efficiency.
- GE Healthcare: GE HealthCare provides the US home healthcare market advanced, connected technologies aiming on remote patient monitoring, AI-enabled diagnostics, and even portable imaging.
- Invacare Corporation: Invacare Corporation aims on mobility, respiratory, and even home care products. They provide premium solutions for long-term care and home medical equipment providers, thus, specializing in powered or manual wheelchairs, patient transfer aids, oxygen concentrators, and daily living aids promoted to promote patient independence.
- Amedisys: Amedisys provides a comprehensive suite of services, which includes hospice, palliative care, personalized home health, and high-acuity, hospital-level care. They aim on chronic disease management, injury or illness recovery, along with skilled nursing to improve patients' quality of life.
- LHC Group, Inc.: LHC Group, Inc. offers comprehensive in-home healthcare services, which includes skilled nursing, personal care, hospice, and therapy, across 37 states.
U.S. Home Healthcare Market Companies
- Baxter International Inc.
- Abbott.
- ResMed Inc.
- GE Healthcare
- Invacare Corporation
- Amedisys
- LHC Group, Inc.
- Medline Industries
- BAYADA Home Health Care
- F. Hoffmann-La Roche Ltd
Recent Developments
- In October 2025, LHC Group (U.S.) announced a strategic partnership with a leading telehealth provider to enhance its remote patient monitoring capabilities. This move is significant as it aligns with the growing trend of digital health solutions, allowing LHC Group (US) to offer more comprehensive care while reducing hospital readmissions. The integration of telehealth services is likely to improve patient outcomes and operational efficiency, positioning the company favorably in a competitive market.
- In August 2025, Visiting Angels (U.S.) expanded its franchise network by adding 20 new locations across the Midwest. This expansion reflects the company's commitment to increasing accessibility to home care services. By enhancing its footprint, Visiting Angels (US) not only strengthens its market presence but also responds to the rising demand for in-home care, which is crucial for maintaining a competitive advantage in a growing market.
Segments Covered in the Report
By Type
- Device
- Services
By Device
- Diagnostic & Monitoring Devices
- Therapeutic Devices
- Home Mobility Assist Devices
By Services
- Rehabilitation
- Telehealth
- Respiratory Therapy
- Infusion Therapy
- Unskilled Homecare
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting