
Vapor Deposition Market Trends, Leading Companies, Company Revenue / Sales Performance, Subscriber Growth, Pricing Strategies, Cloud Adoption, Infrastructure Expansion, Competitive Landscape, and Industry Outlook
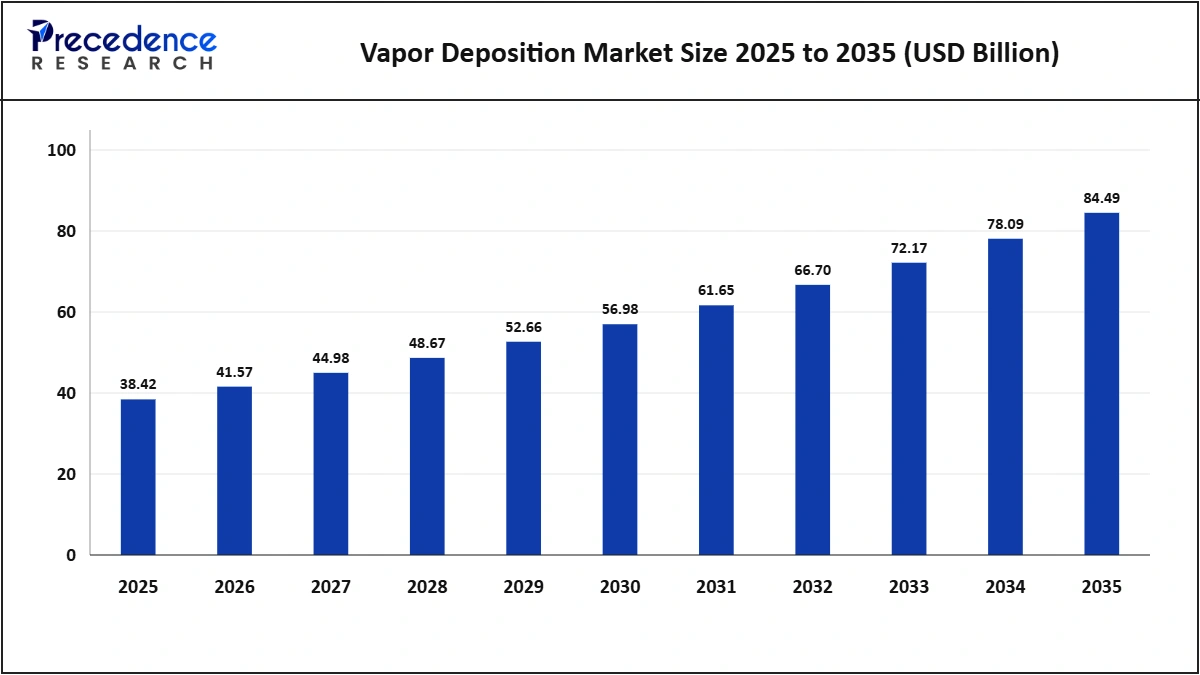
ICT industry specialist Gautam Mahajan estimates the vapor deposition market at USD 41.57 billion in 2026, with continued technology adoption expected to take the market to USD 84.49 billion by 2035 at a CAGR of 8.20%. Leading vapor deposition market providers such as Applied Materials, Lam Research, Tokyo Electron, ASM International are expanding their capabilities across segments including technology, category, application, end user and region.
Source: https://www.precedenceresearch.com/vapor-deposition-market
 Get a Sample
 Table Of Content


Vapor Deposition Market Size, Share, Trends, and Growth Forecast 2035
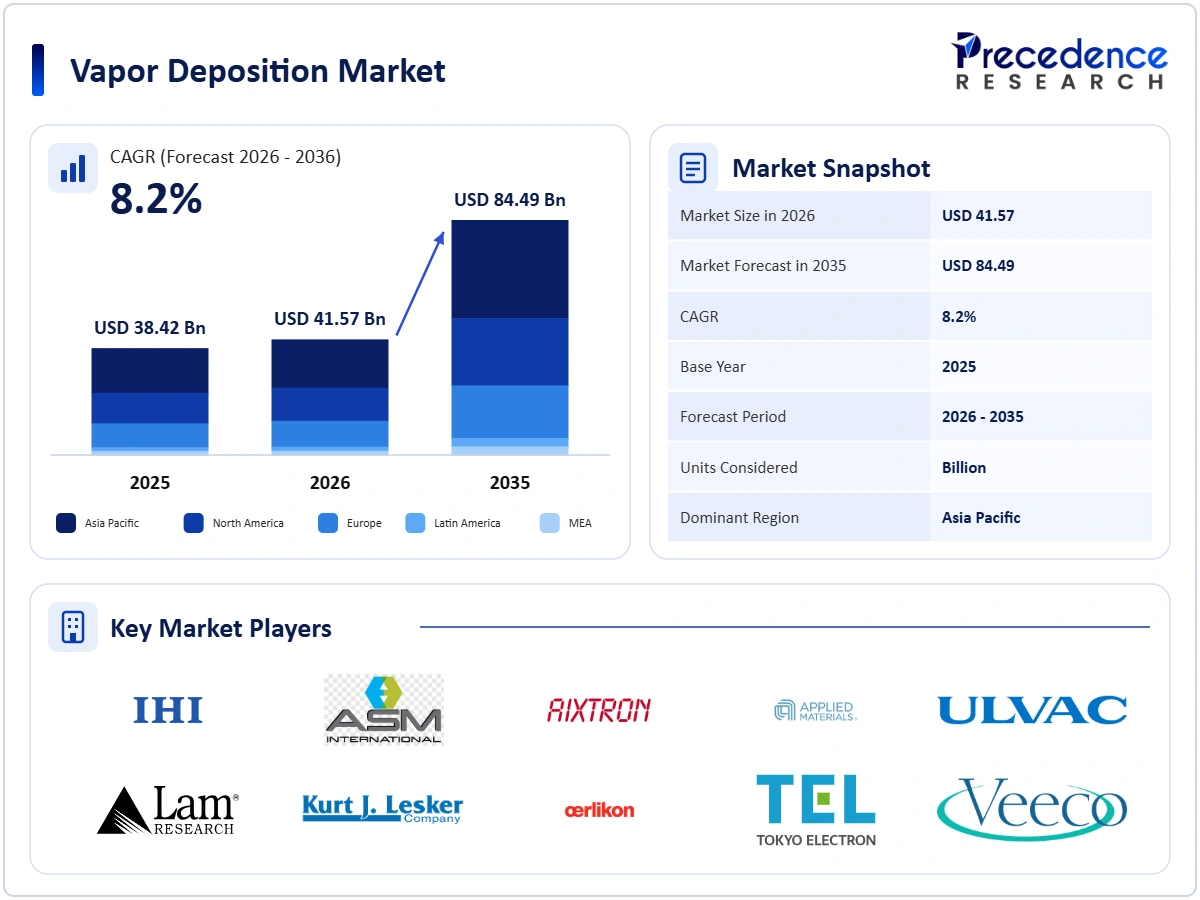
The vapor deposition market is forecasted to expand from USD 41.57 billion in 2026 to USD 84.49 billion by 2035, growing at a CAGR of 8.20% from 2027 to 2036.
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 38.42 billion
- Estimated market size in 2026: USD 41.57 billion
- Projected market size by 2035: USD 84.49 billion
- CAGR (2026-2035): 8.2%
Regional Market Spotlight
- Asia Pacific dominated the vapor deposition market in 2025, accounting for 41.8% of global revenue, valued at USD 16.06 billion. It is projected to be the fastest-growing region, with a CAGR of 9.05% from 2025 to 2035.
- North America represented 28.6% of the market in 2025, generating USD 10.99 billion in revenue.
- Europe held a 22.4% market share in 2025, with revenue reaching USD 8.61 billion.
Segmental Spotlight
- By technology, Chemical Vapor Deposition (CVD, ALD, MOCVD) accounted for 53.2%, valued at USD 20.44 billion in 2025.
- By category, equipment was valued at USD 19.82 billion, equivalent to 51.6% in 2025.
- By application, microelectronics accounted for 36.4% in 2025.
- In 2025, based on end user, electronics & semiconductors accounted for 43.2%, valued at USD 16.6 billion.
Vapor Deposition Market Size and Forecast, 2025-2035 (USD Billion)
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The vapor deposition market is projected to expand from USD 38.42 billion in 2025 to USD 84.49 billion by 2035, registering a CAGR of 8.20% from 2026 to 2035. Market growth reflects the increasing complexity of semiconductor manufacturing, particularly the deposition requirements of gate-all-around transistors, 3D NAND, and advanced DRAM. Demand for PVD hard coatings across tooling, automotive, and medical device industries also contributes to expansion. Growing production of wide-bandgap power devices, solar cells, and optical components further broadens the market's application base. Revenue is projected to reach USD 56.98 billion by 2030.
Analyst View: Semiconductor demand was linked to wafer starts and the number of deposition steps per wafer at each technology node. Industrial demand to tool, automotive, and medical device output. The total was cross-checked against the deposition revenue of leading equipment makers and coating service providers and against published estimates, which places our base year slightly above comparable figures. The growth rate reflects rising deposition intensity in advanced chips and steady industrial coating demand, adjusted for the cyclical nature of semiconductor spending.
Market Trends
- Gate-all-around transistors now require additional ALD and CVD steps for each wafer.
- Molybdenum is replacing tungsten in chip metallization processes.
- MOCVD capacity is expanding for gallium nitride power devices.
- Advanced arc PVD is improving tool coating performance.
- Manufacturers are outsourcing more industrial coating to service providers.
- Low-temperature plasma deposition is enabling 3D memory and packaging.
Drivers, Restraints, and Opportunities
Driver
Advanced logic and memory chips use more thin-film layers and more complex 3D structures, which increase the number of deposition steps per wafer. Rising demand for AI and data centers is driving investment in leading-edge fabs and advanced packaging. Gallium nitride and silicon carbide power devices designed for EVs and data centres rely on MOCVD and epitaxy tools for their fabrication.
Restraint
Expenditure on semiconductor equipment is cyclical and can fall sharply when chip demand weakens. Export controls on advanced equipment limit sales to some markets and create uncertainty for suppliers. Deposition systems and precursors are expensive, and some processes use hazardous gases that require strict safety controls.
Opportunity
New fabs in the United States, Europe, Japan, and India will need large volumes of deposition equipment. Hard and functional coatings for EV parts, hydrogen components, and medical implants offer growth for PVD equipment and services. New materials such as molybdenum and advanced dielectrics create demand for new deposition tools and precursors.
Vapor Deposition Market Segmentation: 2025 Share and Value
Vapor Deposition Market By Technology 2025 Share & Size
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
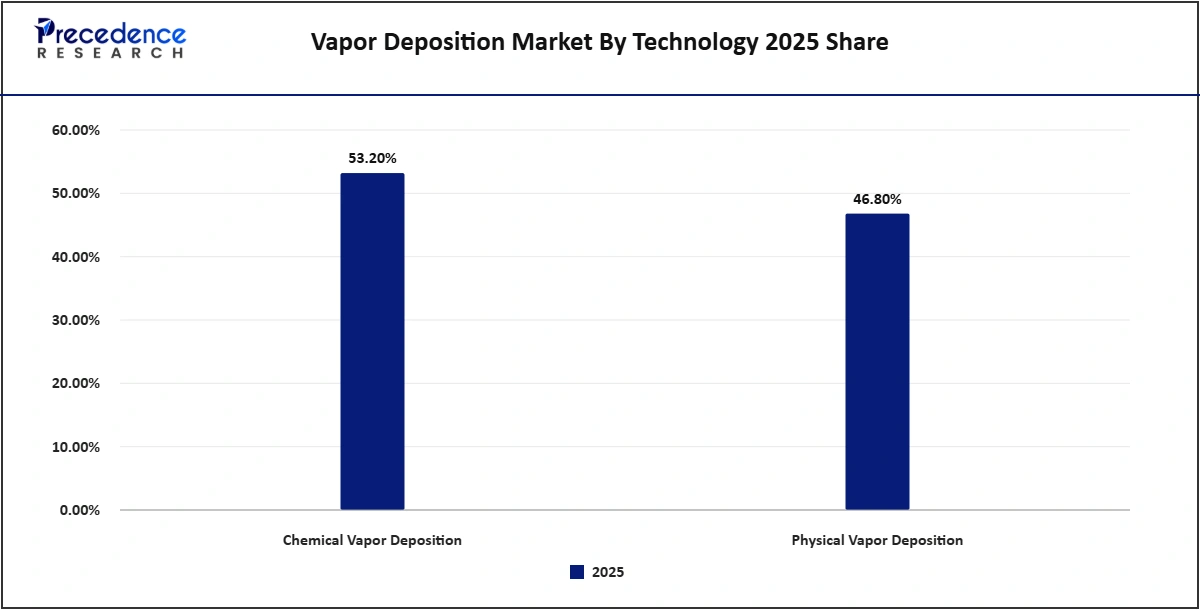
Chemical vapor deposition (CVD) accounted for 53.2% of the vapor deposition market in 2025, with revenue reaching USD 20.44 billion. Its leading position reflects the need for uniform thin-film layers in advanced logic and memory chips with complex, high-aspect-ratio structures. Atomic layer deposition (ALD) and metal-organic chemical vapor deposition (MOCVD) support the production of gate-all-around transistors, 3D NAND memory, and gallium nitride devices. Physical vapor deposition (PVD) represented the remaining 46.8% of the market, valued at USD 17.98 billion. It serves semiconductor metallisation and the application of hard, wear-resistant, and decorative coatings to industrial tools, automotive components, and consumer goods.
Vapor Deposition Market By Category 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Equipment | 51.6% | USD 19.82 billion |
| Coating Services | 28.2% | USD 10.83 billion |
| Materials | 20.2% | USD 7.76 billion |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
In 2025, equipment represents 51.6% of the market, valued at USD 19.82 billion. This segment is popularized by semiconductor deposition tools, which are characterized by their high per-system prices. Coating services were valued at USD 10.83 billion, equivalent to 28.2% of the market, as companies in sectors such as tool manufacturing, automotive, and medical devices increasingly outsource PVD and CVD coating work to specialized providers. Additionally, materials, which include precursors and sputtering targets, are predicted to constitute 20.2% of the market, valued at USD 7.76 billion.
Vapor Deposition Market By Application 2025 Share & Size
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
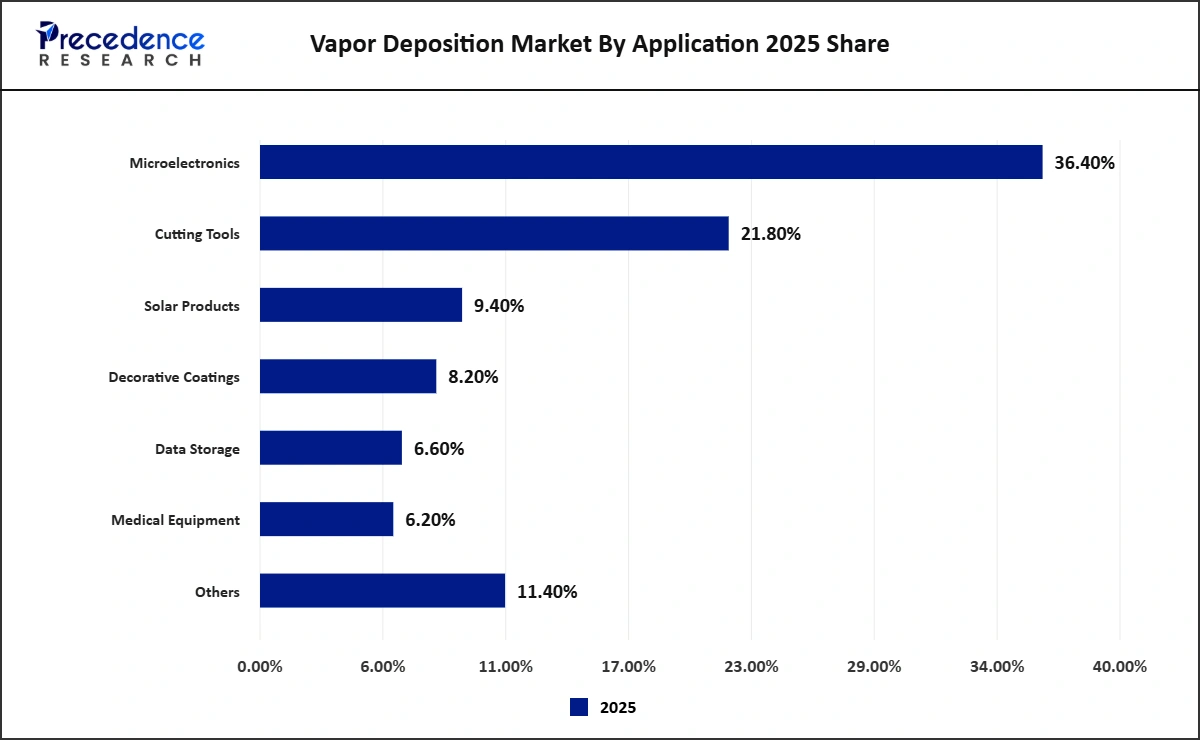
Microelectronics represented the largest application segment in the vapor deposition market in 2025, accounting for 36.4% of revenue, equivalent to USD 13.98 billion. Demand is driven by advances in semiconductor, display, and electronic component manufacturing. Cutting tools ranked second, with a 21.8% share valued at USD 8.38 billion, supported by the use of hard coatings to improve tool durability and service life. Solar products accounted for 9.4% of the market, generating USD 3.61 billion, while decorative coatings represented 8.2%, valued at USD 3.15 billion. Data storage applications contributed 6.6% of revenue, or USD 2.54 billion, and medical equipment accounted for 6.2%, equivalent to USD 2.38 billion. Other applications, including optics and aerospace components, collectively represented 11.4% of the market, valued at USD 4.38 billion.
Vapor Deposition Market By End User 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Electronics & Semiconductor | 43.2% | USD 16.60 billion |
| Automotive | 16.4% | USD 6.30 billion |
| Industrial & Machinery | 14.2% | USD 5.46 billion |
| Energy | 9.2% | USD 3.53 billion |
| Medical | 7.4% | USD 2.84 billion |
| Aerospace & Defense | 5.6% | USD 2.15 billion |
| Others | 4% | USD 1.54 billion |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
In 2025, the electronics and semiconductor sector dominated the market, with a valuation of USD 16.6 billion, accounting for 43.2% of the total market. The automotive industry followed, with 16.4%, estimated at USD 6.3 billion, mainly for coatings for engine parts, power electronics, and sensors. Industrial and machinery applications were valued at USD 5.46 billion, representing 14.2%, while the energy sector was expected to hold 9.2%, equivalent to USD 3.53 billion.
The medical industry accounted for 7.4%, estimated at USD 2.84 billion. By comparison, the aerospace and defense sectors captured 5.6%, or USD 2.15 billion, while other sectors made up 4%, equating to USD 1.54 billion.
- Analyst View: According to our analysis, CVD leads because new chip structures add more ALD and CVD steps than PVD steps. We expect CVD and electronics to gain share as chip complexity rises, while coating services gain share as more manufacturers outsource industrial coating.
Regional Analysis
Vapor Deposition Market By Region 2025 Share & Size
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
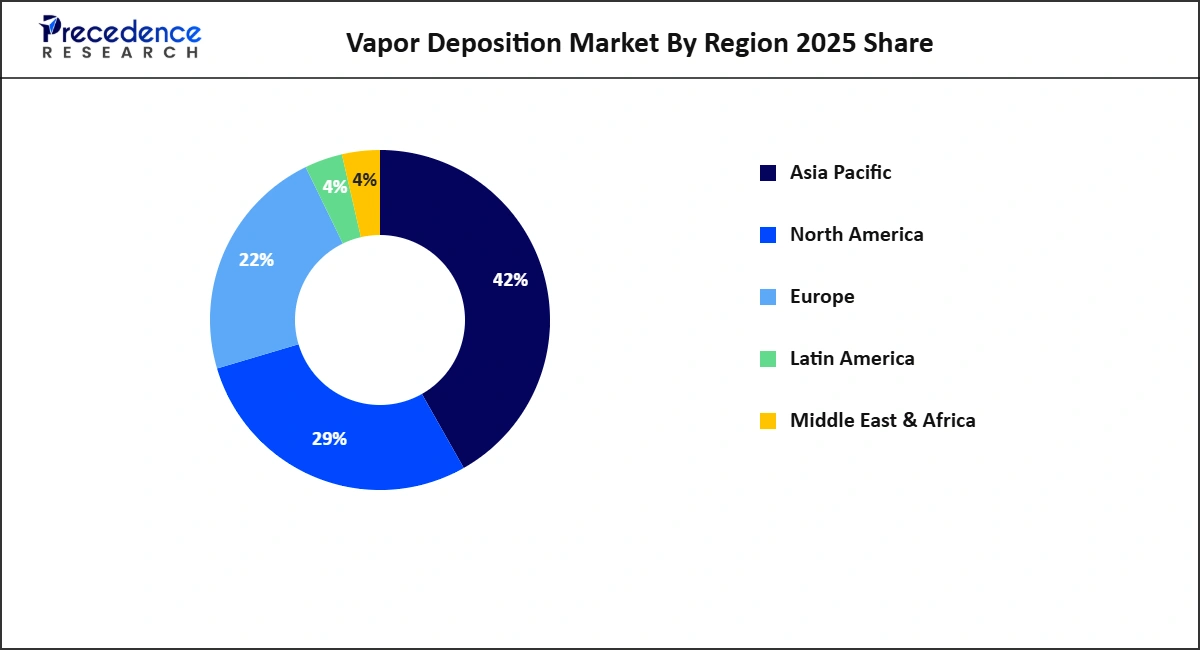
Asia Pacific accounted for 41.8% of the market in 2025, owing to the presence of semiconductor fabs in Taiwan, South Korea, China, and Japan, as well as robust display production and a significant tool and automotive coating industry. North America attained 28.6% of the market, driven by new chip fabrication investments and strong demand from leading deposition equipment manufacturers, aerospace, and medical coating sectors. Europe, with a 22.4% share, shows growth due to advancements in power semiconductors, automotive and tool coatings, along with contributions from its equipment and coating service companies.
Latin America, at 3.6% (USD 1.38 billion), and the Middle East and Africa, at 3.6% (USD 1.38 billion), are smaller markets supported by automotive, tooling, and energy industries.
Asia Pacific, valued at USD 16.06 billion, covers 41.8% of the market in 2025, making it the fastest-growing region. The demand is largely driven by chip, display, and electronics manufacturing in Taiwan, South Korea, China, and Japan.
North America captures 28.6% of the vapor deposition market in 2025, with revenue reaching USD 10.99 billion. Regional demand is supported by new investments in semiconductor fabrication facilities and the presence of leading deposition equipment manufacturers.
Europe accounted for 22.4%, valued at USD 8.61 billion in 2025. The region is growing due to improved power semiconductors, automotive, and tool coatings, with contributions from its equipment and coating service companies.
Latin America, valued at USD 1.38 billion, represents 3.6% of the market in 2025. Automotive and tooling industries in Brazil support demand.
The Middle East and Africa accounted for 3.6%, with a valuation of USD 1.38 billion in 2025. With development in the energy industry and growing electronics investment, the region is expected to show growth.
Analyst View: Asia Pacific leads because most global chip, display, and electronics production is located there. We assign Asia Pacific the highest growth premium because new fab capacity and domestic equipment demand continue to expand faster there than elsewhere, although new fabs in North America and Europe narrow the gap.
Top 10 Companies in the Vapor Deposition Market
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | Applied Materials | 7.2 | 18.74% | CVD, ALD, PVD and epitaxy systems for semiconductors | United States |
| 2 | Lam Research | 4.6 | 11.97% | CVD, ALD and electrochemical deposition systems | United States |
| 3 | Tokyo Electron | 4.1 | 10.67% | Thermal processing, CVD and ALD systems | Japan |
| 4 | ASM International | 2.4 | 6.25% | ALD and epitaxy systems | Netherlands |
| 5 | Oerlikon | 1.2 | 3.12% | PVD coating systems and coating services (Oerlikon Balzers) | Switzerland |
| 6 | ULVAC | 0.95 | 2.47% | Sputtering and CVD systems for electronics and displays | Japan |
| 7 | AIXTRON | 0.65 | 1.69% | MOCVD and CVD systems for GaN, SiC and optoelectronics | Germany |
| 8 | IHI Corporation | 0.42 | 1.09% | PVD and CVD coating equipment and services (IHI Ionbond, Hauzer) | Japan |
| 9 | Veeco Instruments | 0.35 | 0.91% | MOCVD, ion beam and laser processing systems | United States |
| 10 | Kurt J. Lesker Company | 0.18 | 0.47% | PVD and vacuum deposition systems and materials | United States |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
The top 10 companies cover an estimated 57.39% of the global vapor deposition market, while the remaining 42.61% is shared among Chinese deposition equipment makers, specialist PVD system builders, regional coating service providers, and precursor and target suppliers.
Applied Materials holds the leading position in the market with an 18.74% market share, offering the widest range of semiconductor deposition technologies including CVD, ALD, PVD, and epitaxy. It is followed by Lam Research at 11.97%, primarily leveraging CVD and ALD tools for memory and logic applications, and Tokyo Electron at 10.67%, focusing on thermal and ALD systems.
The market is mainly concentrated in semiconductor equipment, dominated by a few large suppliers, whereas the industrial coating equipment and services sector is more fragmented, focusing on film quality, throughput, and process expertise.
Recent Developments
- June 2026: Applied Materials unveiled the Centris Spectral SiN ALD system, which uses microwave plasma to deposit silicon nitride films inside 3D structures for gate-all-around transistors and DRAM.
- February 2025: Lam Research unveiled the ALTUS Halo as the industry's first atomic layer deposition (ALD) tool designed for molybdenum metallization in high-volume semiconductor manufacturing.
- September 2024: Oerlikon Balzers introduced the INVENTA PVD coating system, featuring Advanced Arc Technology (AAT) to boost efficiency and precision.
Vapor Deposition Market Segments
By Technology
- Chemical Vapor Deposition (CVD, ALD, MOCVD)
- Physical Vapor Deposition (PVD)
By Category
- Equipment
- Coating Services
- Materials
By Application
- Microelectronics
- Cutting Tools
- Solar Products
- Decorative Coatings
- Data Storage
- Medical Equipment
- Others
By End User
- Electronics & Semiconductor
- Automotive
- Industrial & Machinery
- Energy
- Medical
- Aerospace & Defense
- Others
By Region
- North America (U.S., Canada, Mexico)
- Europe (Germany, U.K., France, Italy, Spain, Rest of Europe)
- Asia Pacific (China, Japan, India, South Korea, Taiwan, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East & Africa (GCC, South Africa, Rest of MEA)
Research Methodology
The vapor deposition market was defined as chemical and physical vapor deposition equipment and deposition materials. Coating services are sold worldwide for semiconductor, electronics, tooling, automotive, energy, medical, and other uses. The 2025 base year was built bottom-up from wafer fab equipment spending, deposition steps per wafer, and industrial coating output, multiplied by equipment, material, and service prices. Checked top-down against the deposition revenue of leading equipment makers and coating service providers.
Segment, regional, and company values were allocated from technology, category and end-use volumes and regional fab and industrial capacity. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year. The 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: Overall Market
The vapor deposition market is led by semiconductor equipment, where rising chip complexity steadily increases deposition intensity, and is supported by a broad industrial coating base. Our estimate links demand to wafer fab spending, deposition steps per wafer, and industrial coating output, so the forecast follows chip technology roadmaps and manufacturing activity. The main upside comes from gate-all-around transistors, 3D memory, and power devices, while the main risks are cyclical chip spending and export restrictions.
Sources and References
- Applied Materials. "Applied Materials unveils deposition and selective etch systems to advance 3D chip scaling". 2026-06-15. Centris Spectral SiN ALD system. https://mfn.se/one/a/applied-materials/applied-materials-unveils-deposition-and-selective-etch-systems-to-advance-3d-chip-scaling-5f30f95a
- Lam Research. "Lam Research ALTUS Halo for molybdenum atomic layer deposition". 2025-02-26. First ALD tool for molybdenum metallization. https://www.storagenewsletter.com/2025/02/26/lam-research-altus-halo-for-molybdenum-atomic-layer-deposition-for-semiconductor-metallization/
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting