
Liquid Biopsy Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Clinical Trial Trends, Market Share, and Demand Forecast
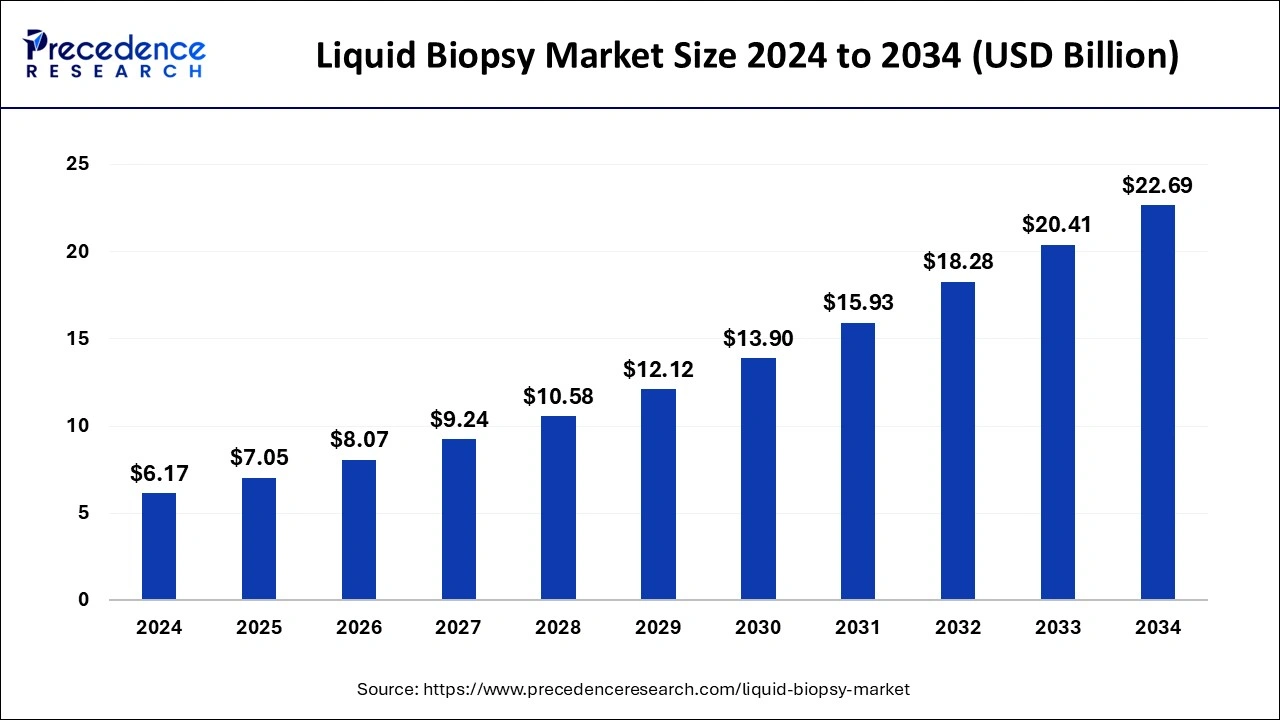
The global liquid biopsy market was valued at USD 8.07 billion in 2026 and is projected to reach USD 24.87 billion by 2035, expanding at a CAGR of 13.44% from 2026 to 2035. Market growth is driven by the rising incidence of cancer, increasing demand for non-invasive diagnostic testing, and growing adoption of precision medicine. Advancements in next-generation sequencing (NGS), AI-powered diagnostics, and biomarker technologies, along with increasing investments in oncology research and early cancer detection, are further accelerating the adoption of liquid biopsy solutions worldwide.
Source: https://www.precedenceresearch.com/liquid-biopsy-market
 Get a Sample
 Table Of Content


What is the Liquid Biospy Market Size?
The global liquid biopsy market size is predicted to increase from USD 8.07 billion in 2026 to approximately USD 24.87 billion by 2035, representing a CAGR of 13.44% from 2026 to 2035. The liquid biopsy market is driven by the increasing incidence of cancer and the increasing demand for non-invasive diagnostic testing.
Key Takeaways
- Leading analyte ctDNA/cfDNA forms the core revenue pool because it supports genotyping, therapy selection, MRD detection and longitudinal monitoring.
- Leading technology NGS leads on analytical breadth, while PCR/dPCR remains important for targeted, lower-complexity testing.
- Fastest-growing applications MRD detection, treatment-response monitoring and recurrence surveillance generate multiple tests per patient, giving them higher lifetime value than one-time profiling.
- Early detection Early cancer detection and multi-cancer screening are the largest long-term population opportunity. Their trajectory depends on clinical utility, positive predictive value, follow-up pathways and payer acceptance.
- Technology shift Competition is moving from detection capability to clinical performance, including sensitivity at low tumor fractions, specificity, turnaround time and clinical validation.
- Regional outlook North America is the most mature market on regulation, reimbursement and laboratory infrastructure. Asia Pacific is the key expansion region.
- Earlier growth benchmark: The previous version of this report cited a CAGR of approximately 11-12% for 2026-2035, which indicates faster growth than many mature diagnostic categories.
- Competitive shift: Differentiation is moving from test availability to clinical evidence, platform breadth, reimbursement access, laboratory scale and recurring testing volumes.
Overview -Liquid Biopsy is Expanding from Advanced Oncology Testing Toward Routine Treatment Selection, MRD Monitoring and Early Cancer Detection
The market is moving beyond tissue-substitute testing toward serial molecular monitoring, where patients can be tested repeatedly to identify molecular residual disease, assess treatment response, detect resistance and monitor recurrence. The commercial opportunity therefore depends not only on the number of tests performed, but also on testing frequency, clinical actionability, reimbursement, and the ability of assays to generate results from low tumor fractions.
The full report evaluates the market across analyte, technology, application, cancer type, sample type, testing setting, customer group and geography, while quantifying market size, growth rates, testing volumes, pricing dynamics, clinical adoption, reimbursement and competitive positioning.
Key Coverage
- ctDNA/cfDNA, CTC and other analyte markets
- NGS, PCR/dPCR and emerging technologies
- Oncology testing applications
- Clinical versus research use
- Geographic market development
- Pricing, reimbursement and recurring-testing economics
Segmentation – ctDNA and cfDNA Form the Core Revenue Pool While MRD and Early Detection Expand the Addressable Market.
Liquid biopsy is segmented primarily by analyte, technology, application, cancer type, sample type, and end user. ctDNA/cfDNA-based testing represents the central technology pool because it can support genotyping, treatment selection, MRD detection, and longitudinal monitoring. CTC analysis remains relevant for specific applications, while methylation, fragmentomics and multi-analyte approaches are expanding the technological boundary.
By application, the market spans companion diagnostics and therapy selection, MRD detection, treatment monitoring, prognosis, recurrence surveillance and early cancer detection. Early detection and multi-cancer screening represent potentially large future markets, but their commercial trajectory depends on clinical utility, positive predictive value, follow-up pathways and payer acceptance.
The report quantifies each segment by market value, growth rate, and geographic opportunity, including the transition from single-purpose assays toward integrated molecular platforms.
Key Coverage
- ctDNA/cfDNA
- CTCs
- Methylation and other biomarkers
- NGS
- PCR/dPCR
- Companion diagnostics
- MRD
- Treatment monitoring
- Recurrence surveillance
- Early detection and multi-cancer screening
Which Market Dynamics are Shifting Liquid Biopsy from Molecular Detection Toward Clinically Actionable, Repeat Testing?
Liquid biopsy adoption is being shaped by the clinical consequence of a test result rather than detection capability alone. Demand is strongest where testing can influence therapy selection, identify molecular resistance, guide treatment continuation or discontinuation, detect minimal residual disease (MRD), or establish recurrence. The underlying drivers, including less invasive sampling, tissue insufficiency, tumor heterogeneity, faster molecular characterization, and longitudinal monitoring, therefore support a shift from one-time diagnostic testing toward repeat testing across the patient treatment journey.
Our analysis indicates that the principal technology challenge is moving from detecting tumor-derived signals to reliably detecting very low levels of circulating tumor DNA, particularly in early-stage disease and MRD applications. Low tumor shedding, low variant allele fractions, and biological heterogeneity increase the risk of false-negative results and place greater importance on analytical sensitivity, error suppression, specificity, and reproducibility. In our view, this makes clinical validation and demonstrated utility increasingly important competitive differentiators: assays that consistently translate molecular signals into actionable treatment decisions are likely to have greater commercial relevance than platforms differentiated only by detection capability.
The strategic implication is that clinical utility and reimbursement-supported adoption can become stronger growth multipliers than assay availability alone. We believe repeat-use applications such as MRD, treatment-response monitoring, and recurrence surveillance can create structurally different economics from one-time molecular profiling because they increase testing frequency and lifetime value per patient. The full report evaluates these dynamics across clinical utility, tissue insufficiency, tumor shedding, analytical sensitivity and specificity, false-positive and false-negative risk, reimbursement barriers, testing frequency, and application-level growth.
The analysis can also be structured as a granular clinical-use and technology dataset, tracking application, cancer type, testing purpose, sensitivity requirements, clinical evidence, regulatory status, reimbursement status, testing frequency, and technology approach. This enables filtering and benchmarking of liquid-biopsy applications to identify where clinical actionability, repeat-testing potential, and evidence maturity are strongest.
What Factors are Reshaping Liquid Biopsy Economics Beyond Test Price?
Liquid biopsy economics vary significantly by application and technology. Broad NGS profiling generally involves greater analytical complexity than targeted PCR testing, while high-sensitivity MRD assays require advanced molecular workflows and stringent analytical validation. Screening tests follow a different economic model, where population scale, follow-up procedures and payer coverage can materially influence commercial value.
Our analysis indicates that the economic opportunity is increasingly determined by revenue generated across the patient testing journey rather than a single-test ASP. Baseline profiling, treatment monitoring, MRD assessment and recurrence surveillance can create multiple testing occasions, increasing cumulative testing value per patient. In our view, applications with recurring clinical use and established utility can therefore support more durable revenue opportunities than one-time testing.
The strategic implication is that reimbursement, testing frequency and laboratory economics are becoming important determinants of market attractiveness. Differences in sample processing, sequencing requirements, bioinformatics, laboratory workflows and reimbursement coverage can influence scalability and margin potential even when headline test prices are similar. The full report assesses these factors to compare the economics and recurring revenue potential of major liquid biopsy applications.
Which Technologies are Expanding the Clinical Potential of Liquid Biopsy?
Innovation in liquid biopsy is focused on detecting smaller quantities of tumor-derived material while improving specificity and analytical reliability. Key technology directions include ultra-sensitive ctDNA detection, methylation profiling, fragmentomics, whole-genome approaches, multi-analyte assays, and AI-assisted molecular interpretation. These developments are broadening the potential applications of liquid biopsy beyond established molecular profiling.
Our analysis indicates that technology advancement is particularly important for MRD and early detection, where tumor-derived signals can be substantially weaker than in advanced disease. Improvements in error correction, molecular barcoding, sequencing depth, and computational classification can increase the ability to distinguish clinically relevant signals from background biological noise. In our view, the combination of molecular sensitivity and computational interpretation will be an important determinant of whether emerging technologies can achieve broader clinical adoption.
The strategic implication is that technology differentiation is increasingly measured by clinical performance rather than technology complexity alone. Analytical sensitivity, specificity, detection limit, turnaround time, sequencing requirements, tissue concordance, clinical validation, and commercialization maturity provide a more meaningful basis for comparing platforms across applications. The full report assesses these dimensions across ctDNA detection, methylation, fragmentomics, multi-analyte testing, NGS, digital PCR, and AI-enabled bioinformatics.
The analysis can also be structured as a technology benchmarking dataset, tracking technology type, analytical sensitivity, limit of detection, specificity, turnaround time, sequencing requirements, clinical validation, and commercialization stage. This enables application-level comparison of technology maturity and performance across emerging liquid biopsy platforms.
Why Do Regulatory Requirements, Clinical Evidence and Reimbursement Matter for the Adoption of Liquid Biopsy?
The regulatory environment varies across screening, companion diagnostics, MRD, and laboratory-developed testing. As liquid biopsy moves from research applications toward treatment decisions, requirements for analytical validation, clinical performance, patient outcomes, quality systems and post-market evidence are becoming increasingly important. Regulatory authorization can therefore influence not only market access but also the level of clinical confidence required for broader adoption.
Our analysis indicates that reimbursement remains a critical determinant of commercial adoption. Tests that demonstrate measurable value in treatment selection, recurrence detection, or patient outcomes have a stronger basis for integration into routine clinical practice than tests that generate molecular information without a clearly defined clinical consequence. In our view, the combination of regulatory evidence and demonstrated clinical utility will increasingly determine whether liquid biopsy applications progress from specialized use toward broader adoption.
The strategic implication is that regulatory approval alone may not be sufficient to establish sustained market demand. Payer coverage, reimbursement frameworks, clinical guidelines, and evidence requirements can materially influence physician adoption and testing frequency. The full report evaluates regulatory pathways, approval milestones, companion-diagnostic requirements, the LDT environment, clinical evidence, payer coverage and adoption barriers across major markets.
Who is Shaping Demand Across Liquid Biopsy Applications: Hospitals, Diagnostic Laboratories or Pharmaceutical Developers?
The liquid biopsy customer base spans hospitals, oncology centers, molecular diagnostic laboratories, pharmaceutical companies, academic institutions, and research organizations, with purchasing requirements varying by application and clinical use. Pharmaceutical demand is particularly significant because liquid biopsy can support patient selection, biomarker identification, clinical trials, and treatment monitoring, while healthcare providers increasingly use testing for molecular profiling and longitudinal disease assessment.
Our analysis indicates that clinical demand is expanding from initial molecular profiling toward MRD, treatment-response monitoring and recurrence surveillance, creating greater potential for repeat testing across the patient journey. Screening represents a distinct high-volume opportunity, but its commercial expansion depends on broader patient engagement, follow-up capacity and supporting clinical infrastructure. In our view, application-specific clinical utility and testing frequency will increasingly influence customer demand and purchasing decisions.
The strategic implication is that customer concentration, reimbursement exposure and channel structure can materially influence commercial scalability. Hospitals and oncology centers may prioritize clinical utility, turnaround time and reimbursement, while pharmaceutical developers place greater emphasis on biomarker performance, trial integration and patient stratification. Diagnostic laboratories and research institutions have different requirements around workflow integration, analytical performance, and laboratory capabilities. The full report evaluates these customer segments and applications based on purchasing criteria, test volumes, channel structures, reimbursement exposure, and growth potential.
Competition Shifting from Test Availability Toward Clinical Evidence, Platform Breadth and Commercial Scale?
The liquid biopsy competitive landscape involves established molecular-diagnostics companies, specialized liquid-biopsy providers, oncology-testing companies, sequencing businesses and diagnostic technology suppliers. Competitive differentiation is increasingly shaped by clinical evidence, regulatory status, assay sensitivity, turnaround time, reimbursement access, laboratory infrastructure, and recurring testing volumes, rather than test availability alone.
Our analysis indicates that competitive positioning depends on the ability to combine technology performance with clinical validation and commercial execution. Companies with differentiated assay platforms may compete across molecular profiling, MRD, screening and treatment monitoring, while others focus on specific applications or customer segments. In our view, platform breadth, evidence maturity and the ability to translate testing capabilities into recurring clinical use are becoming increasingly important dimensions of competitive differentiation.
The report evaluates a relevant universe of leading global and regional participants, including Guardant Health, Natera, Exact Sciences, GRAIL, Roche/Foundation Medicine, Illumina, QIAGEN, Thermo Fisher Scientific, Bio-Rad Laboratories, Myriad Genetics, Burning Rock Biotech, Personalis, Freenome, Singlera Genomics, NeoGenomics, Adaptive Biotechnologies, Fulgent Genetics, Caris Life Sciences, Lucence, DiaCarta, Biodesix, Circulogene and other relevant specialists. These companies are assessed across liquid-biopsy revenue exposure, portfolio breadth, regulatory milestones, clinical evidence, technology platform, application exposure, geographic presence, and commercialization strategy.
The analysis can also be structured as a competitive benchmarking dataset, tracking company, liquid-biopsy exposure, technology platform, application focus, regulatory status, clinical evidence, geographic presence, commercial scale, and portfolio breadth. This enables structured comparison of competitive positioning across established platforms, specialized providers, and emerging regional participants.
Which Applications and Geographies Offer the Strongest Competitive Opportunities?
Competitive positioning varies across therapy selection, MRD, treatment-response monitoring, recurrence surveillance and screening, with each application presenting different requirements for clinical evidence, testing frequency, reimbursement and commercial adoption. Screening can create high-volume opportunities, while MRD and treatment monitoring are more closely linked to longitudinal oncology care and precision-medicine workflows.
Our analysis indicates that geographic opportunity is shaped by differences in regulatory maturity, reimbursement frameworks, laboratory infrastructure, and cancer burden across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Asia Pacific represents an important expansion market, with the supplied market estimates indicating that India could grow from approximately USD 80.8 million in 2025 to USD 176 million by 2036, representing roughly 16.9% annual growth. These differences create distinct conditions for companies depending on their application focus, regulatory position, and ability to establish local commercial and laboratory infrastructure.
The full report benchmarks regional competition across North America, Europe, Asia Pacific, Latin America, the Middle East & Africa and India, assessing application exposure alongside regulatory environment, reimbursement conditions, laboratory capabilities and market development. This enables comparison of how screening, MRD, precision oncology and other liquid biopsy applications translate into different competitive opportunities across geographic markets.
Do Laboratory Scale, Sequencing Infrastructure and Processing Capacity Create Competitive Advantage in Liquid Biopsy?
Unlike conventional medical-device markets, liquid biopsy capacity is determined primarily by laboratory throughput, sequencing infrastructure, sample logistics, automation, and computational systems. As testing volumes increase, the ability to process samples efficiently while maintaining analytical consistency becomes an important component of commercial scalability.
Our analysis indicates that scalable laboratory networks can create operating leverage while enabling companies to support geographically distributed clinical networks. Capacity is therefore influenced not only by the number of tests that can be processed, but also by automation, sequencing capabilities, sample-processing workflows, and computational infrastructure. In our view, companies with scalable and integrated laboratory operations can be better positioned to support increasing testing volumes and broader geographic expansion.
The full report benchmarks laboratory capacity, test-processing volumes, automation, sequencing infrastructure, sample-processing capabilities, sample logistics and geographic laboratory footprints, where disclosed. Capacity expansion is also assessed to understand how laboratory infrastructure can support future commercial growth and application-level adoption.
Regulatory Milestones, Clinical Progress and Platform Expansion Reshaping Competitive Differentiation in Liquid Biopsy?
Recent strategic activity across liquid biopsy is increasingly focused on regulatory submissions, clinical trials, new cancer indications, MRD applications, screening commercialization, pharmaceutical partnerships, sequencing integration, and geographic expansion. These developments reflect a market moving from technology development toward broader clinical validation and commercial deployment.
Our analysis indicates that strategic differentiation is increasingly influenced by the ability to convert clinical and technology advances into commercially relevant applications. Product launches and regulatory milestones can expand addressable indications, while clinical results and partnerships can strengthen evidence and market access. Technology investments, laboratory expansion, and geographic development can further support the transition from specialized testing toward scalable commercial operations.
The full report tracks major developments over the latest 2–3 years, including product launches, FDA milestones, clinical trials, partnerships, technology investments, laboratory expansion, and geographic expansion. This provides a structured view of how companies are strengthening their technology platforms, clinical positioning, operational capacity, and market reach.
M&A and Strategic Investments Reshaping Capabilities Across Molecular Detection, MRD, Early Detection and Data-Driven Diagnostics?
M&A and strategic investment activity in liquid biopsy is increasingly focused on proprietary molecular assays, sequencing capabilities, AI-enabled interpretation, early cancer detection and clinical diagnostics platforms. These transactions can provide access to differentiated technologies, clinical data, laboratory infrastructure, and established commercial channels, allowing companies to expand capabilities or accelerate entry into adjacent applications.
Our analysis indicates that consolidation is increasingly driven by the need to combine complementary capabilities across the liquid biopsy value chain. Acquiring or investing in specialized technology can strengthen molecular detection, MRD, or early-detection capabilities, while access to clinical data, laboratory networks, and commercial relationships can support broader adoption. In our view, the strategic rationale extends beyond technology ownership to include platform integration, application expansion and access to new markets.
The full report evaluates acquisitions and strategic investments across acquirer, target, year, transaction value, technology, application, geography and strategic rationale, with emphasis on transactions that strengthen cancer-detection technologies and complementary molecular-testing capabilities. This provides a structured view of how consolidation is influencing technology portfolios, application breadth, geographic reach, and platform synergies.
What Determines Strategic Positioning Across Liquid Biopsy Companies?
Detailed company profiles assess business overview, liquid-biopsy exposure, product portfolio, financial performance, clinical pipeline, regulatory milestones, partnerships, geographic presence, technology capabilities, and strategic priorities. This provides a consistent basis for understanding how individual companies participate in the market and where their capabilities are concentrated.
Our analysis indicates that strategic positioning is shaped by the combination of commercial scale, technology specialization, clinical evidence, regulatory maturity and future-growth exposure, rather than corporate size alone. Companies with established commercial operations may have broader market reach, while specialized participants may differentiate through focused technology platforms, clinical applications or emerging indications. Reimbursement access and partnerships can further influence the ability to convert these capabilities into sustained commercial adoption.
The full report evaluates each profiled company across revenue, liquid-biopsy exposure, product portfolio, clinical pipeline, regulatory milestones, partnerships, geographic strategy, and strategic priorities, providing a structured view of current market positioning and areas of potential expansion.
Where Do the Largest Market Opportunities and White Spaces Exist Across Liquid Biopsy Applications and Geographies?
The largest white-space opportunities are concentrated in applications where existing diagnostic pathways remain invasive, time-consuming, costly, or insufficiently sensitive. MRD, treatment-response monitoring and recurrence surveillance offer opportunities for recurring testing across the patient journey, while early detection and multi-cancer screening provide access to substantially larger populations but require stronger clinical evidence, scalable workflows and broader reimbursement support.
Our analysis indicates that additional opportunities exist in underserved cancer types and emerging markets where molecular-testing penetration remains limited. As laboratory infrastructure, reimbursement, and clinical adoption improve, these markets can create new demand for liquid biopsy applications that address gaps in conventional diagnostics. Companion diagnostics can provide another expansion pathway by linking molecular testing more directly with targeted treatment selection.
The strategic implication is that future market expansion will depend on closing clinical, geographic, and reimbursement gaps rather than simply increasing test availability. The full report evaluates opportunities across MRD, early detection, recurrence monitoring, multi-cancer screening, companion diagnostics, emerging markets, underserved cancer types, and reimbursement white spaces to identify areas where unmet need and commercial scalability intersect.
What Role Do Clinical Validation, Regulatory Requirements and Technology Barriers Play in Shaping Competitive Forces in Liquid Biopsy?
Supplier power is influenced by the availability of specialized sequencing technologies, reagents, laboratory infrastructure, and other technical inputs, while buyer power varies across hospitals, pharmaceutical customers, payers, and direct testing channels. New entrants face substantial barriers because successful commercialization requires clinical validation, regulatory compliance, reimbursement support and access to relevant clinical and molecular data.
Our analysis indicates that competitive rivalry is shaped by continued differentiation in assay performance, clinical evidence and application expansion. At the same time, tissue biopsy and conventional molecular diagnostics remain important substitutes in applications where liquid biopsy has not yet demonstrated sufficient sensitivity, clinical utility or adoption. Technology requirements and regulatory barriers can therefore influence both the pace of new entry and the ability of existing participants to expand into adjacent applications.
The full report evaluates the five competitive forces across supplier power, buyer power, threat of new entrants, threat of substitutes and competitive rivalry, while assessing the influence of regulatory and technology barriers on market structure. This framework provides a structured view of the factors affecting competitive intensity, market entry and long-term positioning across liquid biopsy applications.
Which Liquid Biopsy Segments and Geographies Offer the Most Attractive Commercial Opportunities?
Market attractiveness is assessed across growth potential, patient opportunity, testing frequency, reimbursement potential, clinical utility, regulatory maturity, competitive intensity, and technology differentiation. This framework recognizes that commercial potential varies significantly across applications and geographies rather than treating liquid biopsy as a single homogeneous market.
Our analysis indicates that MRD and treatment monitoring can generate recurring testing demand because they are linked to longitudinal patient management, while early detection offers substantially larger population potential but requires stronger clinical evidence, broader healthcare-system integration, and greater reimbursement support. These differences create distinct economic and adoption profiles across applications.
The full report evaluates market attractiveness at the segment and geographic level, comparing the combination of demand potential, clinical utility, testing frequency, regulatory maturity, reimbursement conditions, competitive intensity, and technology differentiation. This enables identification of markets where commercial opportunity is supported by both unmet clinical need and the conditions required for sustainable adoption.
Will Liquid Biopsy Evolve from Molecular Detection Toward Longitudinal Cancer Management?
Through 2025–2036, liquid biopsy is expected to expand from primarily molecular profiling toward broader use in MRD-guided treatment, recurrence surveillance, therapy-response monitoring, and early cancer detection. This transition will depend on continued improvements in analytical sensitivity, regulatory expansion, clinical validation, and reimbursement, with adoption varying by application according to evidence maturity and healthcare-system readiness.
Our analysis indicates that the market trajectory will depend heavily on the extent to which liquid biopsy demonstrates measurable clinical utility beyond molecular information alone. Stronger clinical-outcome evidence and broader screening adoption could accelerate market expansion, while reimbursement restrictions, insufficient evidence of clinical utility, or slower regulatory adoption could constrain commercialization. In our view, the ability to integrate liquid biopsy into longitudinal treatment pathways will be a key determinant of future testing frequency and market value.
Future profit pools are expected to increasingly focus on recurring testing, high-sensitivity MRD, early detection, integrated pharmaceutical diagnostics and data-rich molecular platforms. The full report evaluates these opportunities through 2025–2036, including application-level adoption, technology development, regulatory progression, reimbursement conditions and the evolution of commercial value across the liquid biopsy ecosystem.
Strategic Questions Covered in the Report
- Which Applications Will Drive Liquid Biopsy Market Growth?
- What Factors Will Shape Liquid Biopsy Market Economics?
- Which Clinical and Regulatory Factors Will Determine Market Expansion?
- How Will Technology Innovation Expand Liquid Biopsy Applications?
- Where Will Competitive Differentiation Be Concentrated?
- Where are the Major Market Opportunities and White Spaces?
- How Will Liquid Biopsy Evolve Through 2035?
Liquid Biopsy Market Segments
By Product / Analyte
- Circulating Tumor DNA / Circulating Cell-Free DNA
- Circulating Tumor Cells
- Methylation-Based Biomarkers
- Fragmentomics-Based Biomarkers
- Other Liquid Biopsy Biomarkers
By Technology
- Next-Generation Sequencing
- PCR / Digital PCR
- Microarray and Other Molecular Technologies
- Multi-Omics
- AI-Enabled Molecular Analysis
By Application
- Companion Diagnostics / Therapy Selection
- Minimal Residual Disease Detection
- Treatment Response Monitoring
- Recurrence Monitoring
- Prognosis
- Early Cancer Detection
- Multi-Cancer Early Detection
- Screening
- Research Applications
By Cancer Type
- Lung Cancer
- Colorectal Cancer
- Breast Cancer
- Prostate Cancer
- Pancreatic Cancer
- Liver Cancer
- Ovarian Cancer
- Bladder Cancer
- Other Cancer Types
By Sample Type
- Blood / Plasma
- Serum
- Urine
- Cerebrospinal Fluid
- Other Biological Fluids
By End User
- Hospitals and Oncology Centers
- Diagnostic Laboratories
- Pharmaceutical and Biotechnology Companies
- Academic and Research Institutions
- Specialty Cancer Centers
- Other Healthcare Providers
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
By Country
- United States
- Canada
- Germany
- United Kingdom
- France
- Italy
- Spain
- China
- Japan
- India
- South Korea
- Australia
- Brazil
- Mexico
- GCC Countries
- South Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
.webp)
 sales@precedenceresearch.com
 Schedule a Meeting