
Next-Generation Cancer Therapeutics Market Size, Trends, Companies, and Forecast 2026 to 2035
Next-Generation Cancer Therapeutics Market (By Therapy Type: Targeted Therapy, Immunotherapy, Gene Therapy, Cell Therapy, Antibody-Drug Conjugates, RNA-based Therapy; By Cancer Type: Lung Cancer, Breast Cancer, Colorectal Cancer, Blood Cancers, Prostate Cancer, Brain Cancer, Pan-Tumor; By Modality: Monotherapy, Combination Therapy; By Route of Administration: Intravenous (IV), Oral, Intratumoral/Localized, Subcutaneous; By Mechanism of Action; By End-User) - Global Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2035
Source: https://www.precedenceresearch.com/next-generation-cancer-therapeutics-market
 Get a Sample
 Table Of Content


Next-Generation Cancer Therapeutics Market Size and Forecast 2026 to 2035
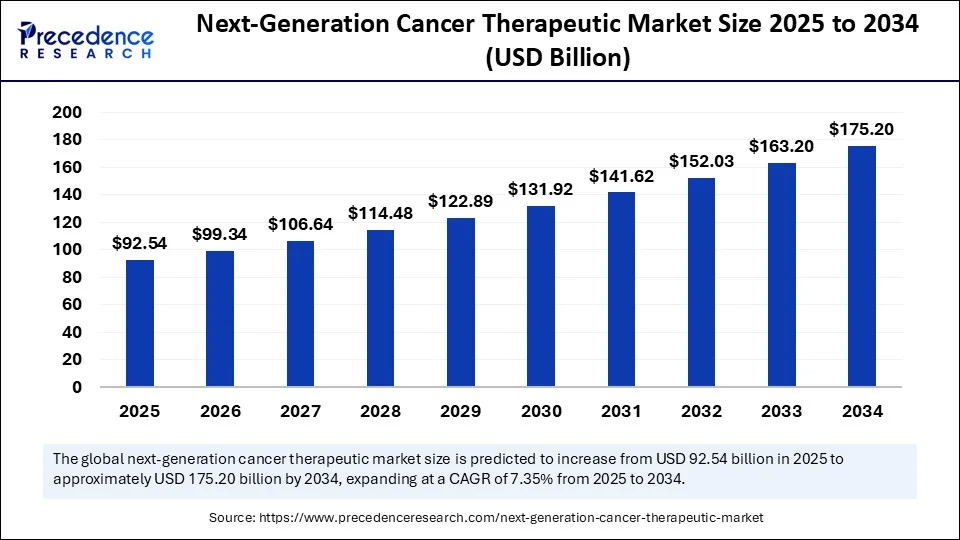
The global next-generation cancer therapeutics market was valued at USD 99.34 billion in 2026 and is projected to reach approximately USD 186.65 billion by 2035, growing at a CAGR of approximately 7.26% from 2026 to 2035. The growth of the next-generation cancer therapeutics market is driven by the rising development of novel immunotherapy, increasing prevalence of cancer, and substantial government funding. The rising demand for personalized treatments and advances in mRNA technology are expected to drive market growth in the coming years.
Next-Generation Cancer Therapeutics Market Key Takeaways
- In terms of revenue, the global next-generation cancer therapeutics market was valued at USD 99.34 billion in 2026.
- It is projected to reach USD 186.65 billion by 2035.
- The market is expected to grow at a CAGR of approximately 7.27% from 2026 to 2035.
- North America dominated the next-generation cancer therapeutics market with the largest market share of 41% in 2026.
- Asia Pacific is expected to expand at the fastest CAGR between 2026 and 2035.
- By therapy type, the targeted therapy segment held the biggest market share in 2026.
- By therapy type, the antibody-drug conjugates (ADCs) segment is expected to grow at a significant CAGR between 2026 and 2035.
- By cancer type, the lung cancer segment captured the highest market share in 2026.
- By cancer type, the blood cancers segment is expected to expand at the fastest CAGR over the projected period.
- By modality, the monotherapy segment contributed the largest market share in 2026.
- By modality, the combination therapy segment is expected to expand at a notable CAGR over the projected period.
- By route of administration, the intravenous (IV) segment held the major market share in 2026.
- By route of administration, the subcutaneous segment is expected to expand at a notable CAGR over the projected period.
- By mechanism of action, the immune activation (Checkpoint Inhibition) segment generated the highest market share in 2026.
- By mechanism of action, the tumor microenvironment modulation segment is expected to expand at a notable CAGR over the forecast period.
- By end user, the specialized cancer hospitals segment led the market in 2026.
- By end user, the homecare (for oral or SC delivery) segment is expected to expand at a significant CAGR over the projected period.
Market Overview
The next-generation cancer therapeutics market encompasses a broad spectrum of innovative, highly targeted, and personalized treatment modalities that go beyond conventional chemotherapy and radiotherapy. These therapies leverage genomic, immunologic, and molecular insights to improve efficacy, minimize toxicity, and often target the cancer's root cause or specific mutations. These include immunotherapies, gene and cell therapies, targeted inhibitors; antibody-drug conjugates (ADCs), RNA-based therapies, and tumor-agnostic treatments. These modalities are transforming oncology by offering precision medicine approaches, especially for hard-to-treat or metastatic cancers.
Impact of AI on the Next-Generation Cancer Therapeutics Market
Artificial intelligence is revolutionizing the market for next-generation cancer therapeutics by accelerating drug discovery, streamlining clinical trials, and enabling personalized treatment strategies. AI can analyze vast genomic and proteomic datasets to identify potential drug targets. In drug discovery, AI algorithms can help predict the efficacy and safety of drug candidates, although these predictions require experimental and clinical validation. In clinical trials, AI predicts the patient response to a specific drug, allowing for more personalized treatment strategies.
AI-based analysis of imaging, pathology and biomarker data is being investigated to help predict treatment response in prostate cancer. The clinical impact on mortality requires supporting evidence. In breast cancer therapeutics, Rakovina and Variational AI have developed first ATR-inhibitor compounds from generative AI. Such innovative move through AI, ranging from image review to drug discovery, indicates AI's potential to transform cancer therapeutics.
Next-Generation Cancer Therapeutics Market Growth Factors
- Increasing Cancer Burden: The rising incidence of cancer worldwide is increasing demand for innovative therapies that offer improved efficacy, lower toxicity, and personalized treatment options.
- Advances in Genomics: Advancements in genomic sequencing technology are fostering the identification of novel tumor-specific mutations that could lead to unprecedented precision therapies such as gene editing and targeted drugs to directly combat cancer-specific functional alterations.
- Immunotherapy Innovation: Innovations such as CAR-T cell therapies and immune checkpoint inhibitors are expanding treatment options for certain cancers, including some relapsed or refractory malignancies.
- Favorable Regulatory Climate: Regulatory agencies are fast-tracking approvals for breakthrough and orphan drugs while also offering incentives to expedite the clinical adoption and commercialization of next-generation cancer therapies, supporting market growth.
Market Dynamics
Drivers
Could regulatory relief improve access to next-gen CAR-T cancer therapies?
Yes, regulatory relief could definitely boost access to next-generation CAR-T cancer therapies. Regulatory changes are speeding up the development of new cancer treatments, especially cell-based immunotherapies like CAR-T therapies. In June 2026, the FDA removed a major safety requirement (REMS) for approved CAR-T therapies such as Breyanzi, Abecma, Carvykti, Kymriah, Tecartus, and Yescarta, stating that updated labeling was enough to ensure safety. The change may reduce certain administrative requirements for eligible CAR-T therapies while leaving applicable safety warnings, monitoring and clinical responsibilities in place. Supportive regulatory frameworks and expedited approval processes for breakthrough therapies support market growth.
Restraint
Is high pricing and taxation stifling next-generation cancer therapies?
High treatment costs and heavy taxation significantly limit access to next-generation cancer therapeutics. The World Health Organization (WHO) reported 20 million new cancer cases in 2022, with 9.7 million deaths, underscoring the need for advanced treatments. The price of innovative therapies, such as CAR-T and bispecific antibodies, often runs into the thousands per dose, leading to higher patient costs and burdening health systems. In India, cancer drugs are typically taxed at 12%, impacting patient affordability.
- In January 2025, Biocon advocated for the Indian government to exempt all cancer and rare-disease drug products from the excise taxes to help reduce out-of-pocket costs for patients.
For countries that do not have enough healthcare budgets or insurance coverage, healthcare policymakers need to be much more cognizant of drug product pricing and taxation policies that negatively affect access to disruptive and potentially highly beneficial therapies, such as CAR-T. If public policy doesn't address pricing and tax burdens, access to these groundbreaking cancer treatments will suffer, especially in low- and middle-income countries.
Opportunity
Is mRNA technology transforming the landscape of cancer treatment?
The key opportunity in the next-generation cancer therapeutics market lies in the quick adoption of mRNA technology and its accelerating innovation cycle. In April 2024, the UK approved the world's first mRNA-based cancer vaccine, BNT122/RO7198457, developed by BioNTech and Genentech. This highlights the regulatory pathways available for personalized mRNA treatments for advanced cancers like melanoma. mRNA vaccines enable rapid development of targeted approaches that use immune function, offering a faster path to regulatory approval compared to traditional methods. This presents an opportunity to lead in personalized, minimally invasive cancer treatments, potentially improving patient outcomes through accelerated timelines. Moreover, the rising development of targeted therapies that specifically attack cancer cells while sparing healthy cells opens new growth avenues. (Source: https://www.europeanpharmaceuticalreview.com)
Segments Insights
Therapy Type Insights
Why did the Targeted Therapy (Small Molecule Inhibitors) Segment Dominate the Next-Generation Cancer Therapeutics Market in 2026?
The targeted therapy segment dominated the market with the largest share in 2026. Small molecular inhibitors are still by far the most prevalent next-generation cancer therapies. They offer advantages of selective targeting cancer-specific proteins and cancer-specific signaling pathways. Small molecule inhibitors find applications in a variety of cancers, such as breast, lung, and colorectal cancer. They are orally delivered, easily integrated into existing treatment paradigms, and can manage acquired resistance all while addressing the growing shift towards precision oncology.
The antibody drug conjugates (ADCs) segment is expected to grow at the fastest rate in the coming years. They have developed quickly as next-generation cancer therapies using monoclonal-based targeting strategies with the addition of very cytotoxic agents to targeted tumor cells instead of systemic cancer treatment. There have been a number of high-profile drugs such as Enhertu for breast and gastric cancers and companies such as Seagen and AstraZeneca are increasing their ADC pipelines. The clinical activity of approved ADCs across selected cancer indications and continued pipeline development support interest in this segment; efficacy and safety vary by product and indication.
Cancer Type Insights
Which Cancer Type Dominate the Market in 2026?
Lung cancer is a major application area for next-generation cancer therapeutics. Add segment-revenue data and its source to substantiate its ranking as the largest market segment. According to the WHO, lung cancer is the leading cause of cancer-related deaths worldwide. Cite the relevant WHO or IARC dataset for any specific incidence, mortality or percentage figure. This prompted the need for next-generation targeted therapies. The combination of EGFR, ALK, and KRAS inhibitors and checkpoint inhibitors has changed the treatment approaches.
The blood cancer segment is expected to grow at the fastest rate in the coming years. With the growing prevalence of leukemia, lymphoma, and myeloma, the demand for new therapies, CAR-T cell therapy, bispecific antibodies, and new immunotherapies is rising. Rising regulatory approvals for new agents applicable to relapsed or refractory leukemia and lymphoma have made momentum in the market.
Modality Insights
Why Did the Monotherapy Segment Dominate the Market in 2026?
The monotherapy segment is reported to lead the market in 2026. Add the underlying segment-share data and methodology supporting this ranking for malignancies such as melanoma and lung cancer. Monotherapy continues to dominate the market due to the relatively straightforward processes involved in manufacturing and the clinical success that is expected to persist in the future.
Meanwhile, the combination therapy segment is expected to grow at the fastest rate in the coming years. It produces the potential to improve standardized regimens for every modality, including pharmacodynamic drugs that span combinations like immune-oncology with targeted therapeutics or ADCs, and/or chemotherapy, mRNA, or with checkpoint inhibitors. These combinations will maximally demonstrate either additive or synergistic (hopefully), which may improve treatment response or progression-free survival in selected indications, depending on clinical evidence. Currently, the focus on oncology-based combinations, an ongoing clinical trial pipeline with investment around multi-modality treatments, is accelerating the rate of combination therapy quite rapidly in oncology.
The use of combination therapies, which involve multiple drugs or treatment modalities, can improve efficacy and overcome drug resistance. Combination therapies are increasingly used to treat all cancers, aiming to overcome tumor heterogeneity and resistance by targeting multiple pathways at once. Combining checkpoint inhibitors with chemotherapy or targeted agents has shown improved outcomes in cancers like NSCLC and melanoma.
Route of Administration Insights
How Does the Intravenous (IV) Segment Dominate the Market in 2026?
The intravenous (IV) segment dominated the next-generation cancer therapeutics market in 2026. The reported IV segment leadership should be supported by the market's route-of-administration revenue data and the inclusion criteria used for IV-administered therapies. IV administration allows for precise dosing and delivery control, which is crucial for drugs with narrow therapeutic windows. Healthcare professionals favor IV routes due to monitoring capabilities, especially for patients undergoing intensive cancer treatments.
The subcutaneous (SC) segment is expected to grow at the fastest CAGR during the forecast period. The rise in the preference for SC delivery is due to patient convenience, reduced administration time, and the potential for home-based delivery, ensuring patients have access to their treatment and are tracked throughout their cycle. SC delivery is becoming more popular in cancer treatments, and this trend is expected to continue with more approvals of SC cancer immunotherapies, like atezolizumab.
Mechanism of Action Insights
Why did the Immune Activation (Checkpoint Inhibition) Segment Dominate the Next-Generation Cancer Therapeutics Market?
The immune activation (checkpoint inhibition) segment is reported to hold the largest share in 2026. This is mainly due to the increased demand for immunotherapies. Checkpoint inhibitors, such as PD-1/PD-L1 and CTLA-4 inhibitors, activate the immune system and provide lasting responses in various cancers. Drugs like pembrolizumab and nivolumab are standard in melanoma, NSCLC, and bladder cancer.
The tumor microenvironment modulation segment is expected to grow at the fastest rate in the coming years. Modulating the tumor microenvironment (TME) is a promising method to fight immune resistance and improve efficacy. Therapies targeting myeloid cells, stromal barriers, and hypoxia are being actively developed. More biotechs are focusing on agents targeting the TME to use with existing immunotherapies.
End-User Insights
What Made Specialized Cancer Hospitals the Dominant Segment in the Market in 2026?
The specialized cancer hospitals segment is reported to lead the market in 2026. Add the underlying end-user revenue or market-share data and its source. Specialty hospitals lead in adopting next-generation cancer therapies due to their infrastructure, access to clinical trials, and skilled oncology teams. They are often the first to implement cutting-edge therapies and participate in international studies. With experience in complex therapies like CAR-T and high-dose immunotherapy, these hospitals will be central to innovative cancer care models.
The homecare segment is expected to grow at the highest CAGR in the upcoming period. This is mainly due to the shift to patient-driven care, which is rapidly expanding homecare settings for therapies that can be delivered parenterally or orally. The pandemic accelerated this trend, with patients seeking less hospital initiation. As patients become more familiar with home cancer care, along with digital monitoring tools, patient education, administration kits, and patient self-injections, home care for cancer has evolved and continues to grow.
Regional Insights
North America Leads the Next Generation Cancer Therapeutics Market
North America leads the market due to its research infrastructure, government support, and innovation-friendly environment. The U.S. FDA approved novel therapies, supporting product pipeline in targeted and next-generation immune-mediated therapies. The National Cancer Institute funds oncology programs through grants, covering all research phases. Biotech hubs in Boston, California, and Texas concentrate clinical trials and partnerships, creating a market for next-generation therapies. Regulatory advances and funding have made the U.S. the global R&D leader. In August 2024, the FDA approved "afami-cel," a T-cell therapy for solid tumors. North America also had over 5,000 active oncology clinical trials in late 2024. Investments from the NIH and strategic investments fuel the demand for novel cell and gene therapies. Moreover, the shift toward personalized medicine, where treatments are tailored to individual patients based on their genetic profiles, is driving market growth.
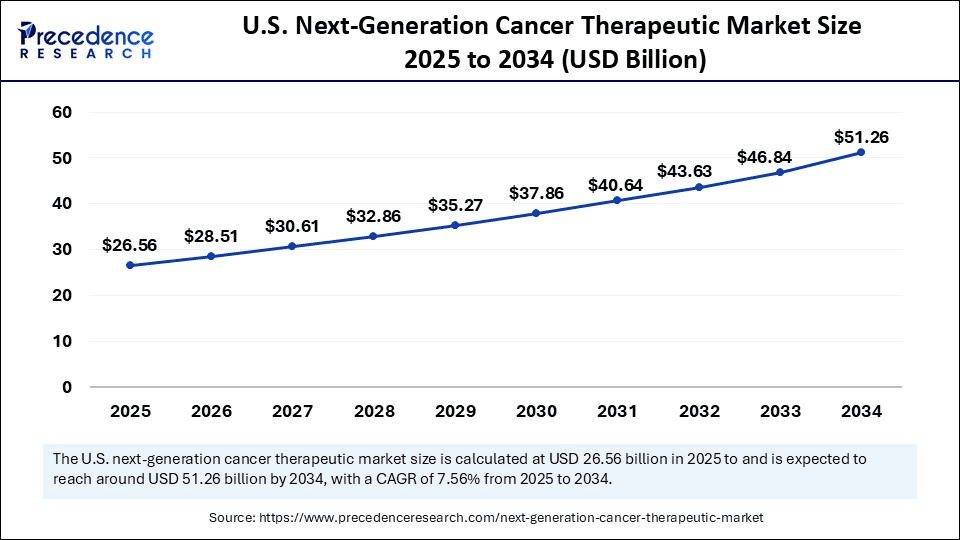
U.S. Next-Generation Cancer Therapeutics Market Size and Growth 2026 to 2035
The U.S. next-generation cancer therapeutics market size was evaluated at USD 28.51 billion in 2026 and is projected to be worth around USD 54.87 billion by 2035, growing at a CAGR of 7.53% from 2026 to 2035.
What Factors Contribute to the Growth of the Next-Generation Cancer Therapeutics Market in Asia Pacific?
Asia Pacific is expected to grow at the fastest rate during the forecast period due to healthcare modernization, policy changes, and rising clinical trials. The rising incidence of cancer fuels the demand for advanced treatments. Governments in China, India, Japan, and South Korea are simplifying approvals and boosting domestic biotech R&D. China leads the region with rapid growth from regulatory reform and R&D investment. China's NMPA has regulatory pathways for eligible products that may use overseas clinical-trial data and qualify for priority review. Cite the applicable NMPA guidance and clarify that eligibility and approval timelines depend on the product and application. Akeso's bispecific antibody drug "Ivonescimab" for lung cancer, approved in 2024, is gaining national attention for its performance.
Next-Generation Cancer Therapeutics Market Companies
- Roche Holding AG
- Bristol Myers Squibb
- Merck & Co., Inc.
- Pfizer Inc.
- Novartis AG
- AstraZeneca plc
- Eli Lilly and Company
- Gilead Sciences, Inc.
- Pfizer Inc.
- Amgen Inc.
- Genentech, Inc.
- Moderna, Inc.
- BioNTech SE
- Bluebird Bio, Inc.
- BeiGene, Ltd.
- Innovent Biologics
- Immatics Biotechnologies
- Adaptimmune Therapeutics
- Fate Therapeutics
- Legend Biotech Corporation
Recent Developments
- In April 2025, Nona Biosciences and Atossa Therapeutics formed a partnership to co-develop next-generation antibody therapies for breast cancer, leveraging Nona's Harbour Mice platform for therapeutic antibody discovery.
Next-Generation Cancer Therapeutics Market Segments
By Therapy Type
- Targeted Therapy (Small Molecule Inhibitors)
- Immunotherapy
- Checkpoint Inhibitors (PD-1, PD-L1, CTLA-4)
- CAR-T Cell Therapy
- Cancer Vaccines
- Gene Therapy
- Cell Therapy (e.g., TILs, NK cells)
- Antibody-Drug Conjugates (ADCs)
- RNA-based Therapy (mRNA, siRNA, ASO, LNA, etc.)
By Cancer Type
- Lung Cancer
- Breast Cancer
- Colorectal Cancer
- Blood Cancers (Leukemia, Lymphoma, Myeloma)
- Prostate Cancer
- Brain Cancer (e.g., GBM)
- Pan-Tumor (Tumor-agnostic therapies)
By Modality
- Monotherapy
- Combination Therapy
- Immunotherapy + Targeted Drugs
- Chemotherapy + ADC
- mRNA + Checkpoint Inhibitors
By Route of Administration
- Intravenous (IV)
- Oral
- Intratumoral / Localized
- Subcutaneous
By Mechanism of Action
- Immune Activation (Checkpoint Inhibition)
- Oncogene Targeting (e.g., BRAF, KRAS, EGFR)
- DNA Damage Response Modulators (e.g., PARP inhibitors)
- Tumor Microenvironment Modulatio
- Apoptosis Induction
By End-User
- Specialized Cancer Hospitals
- Academic & Research Institutes
- Ambulatory Infusion Centers
- Homecare (for oral or SC delivery)
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting