



Rigid Packaging Market Trends, Key Companies, Company Technology / Innovation, Cost per Unit, Sales Volume, Recycling Rate, Export & Import Metrics, Adoption Rates, Pricing Strategies, Production Volume, and Logistics Efficiency
Videsh Swar, a Packaging Industry Expert, estimates the rigid packaging market at USD 256.63 billion in 2026, with the market projected to reach USD 395.31 billion by 2035 at a CAGR of 4.92%. Major rigid packaging market companies such as Bemis Company, Inc. Amcor Limited, Coveris Holdings S.A, Reynolds Group Holding are competing across key material and application segments, including By Material, By Application By Regional,
Source: https://www.precedenceresearch.com/rigid-packaging-market
 Get a Sample
 Table Of Content


What is the Rigid Packaging Market Size?
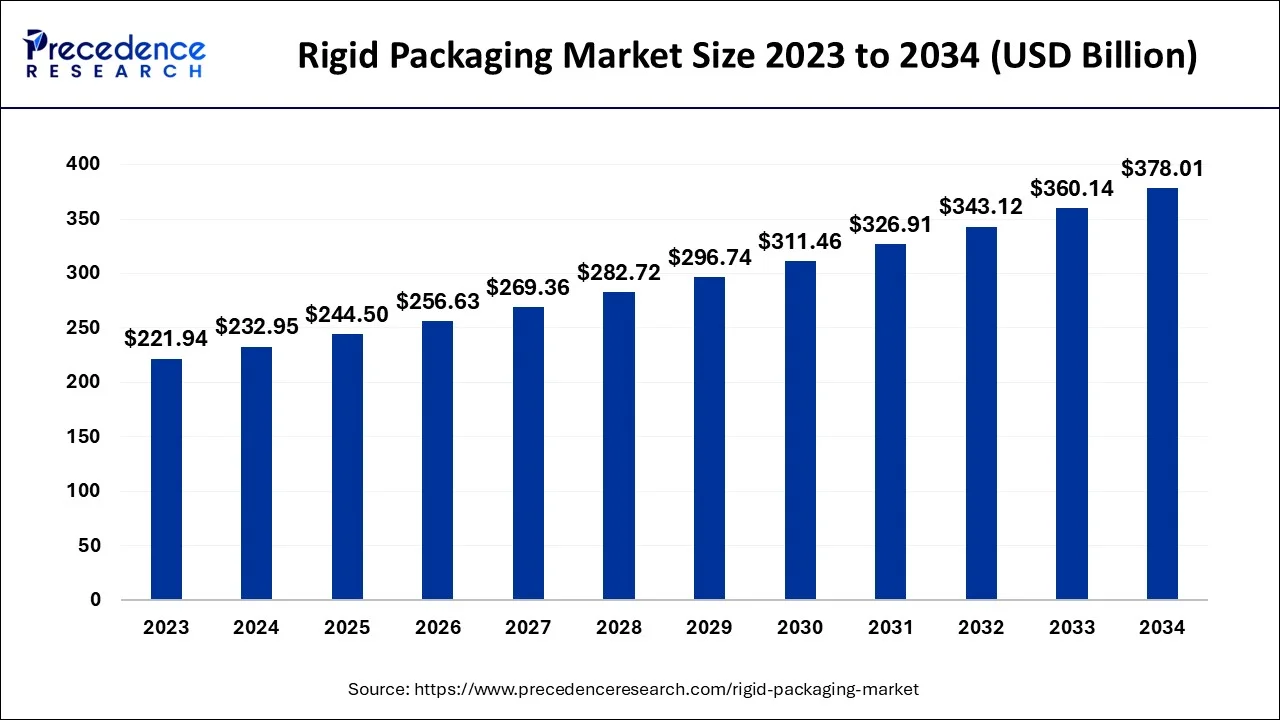
The global rigid packaging market size is calculated at USD 244.50 billion in 2025 and is predicted to increase from USD 256.63 billion in 2026 to approximately USD 395.31 billion by 2035, expanding at a CAGR of 4.92% from 2026 to 2035.
Rigid Packaging Market Key Takeaways
- In terms of revenue, the rigid packaging market is valued at $244.50 billion in 2025.
- It is projected to reach $395.31 billion by 2035.
- The rigid packaging market is expected to grow at a CAGR of 4.92% from 2026 to 2035.
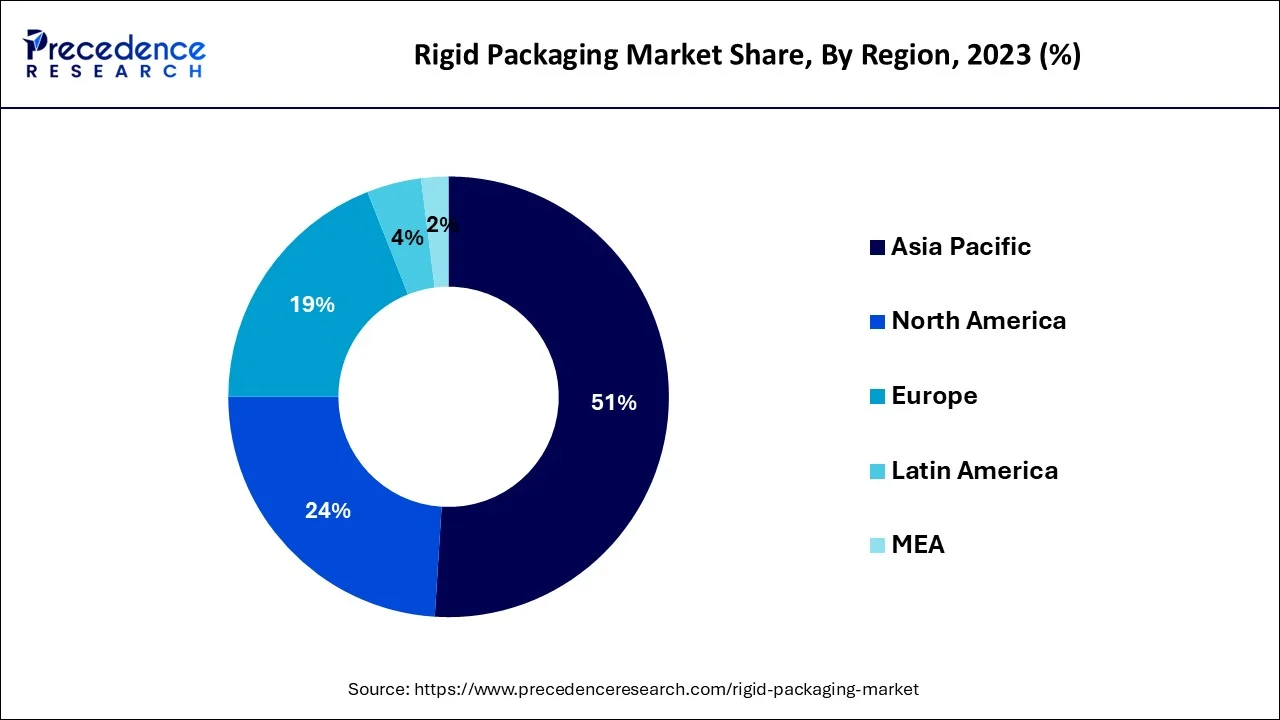
- Asia Pacific generated more than 51% of the revenue share in 2025.
- North America is expected to expand at the fastest CAGR between 2026 and 2035.
- By Material, the plastics segment is expected to register the highest market share from 2026 to 2035.
- By Material, the paper & paperboard segment is predicted to grow at the highest CAGR from 2026 to 2035.
- By Application, the food & beverages segment contributed more than 59% of the market share in 2025.
Market Overview
Packaging is referred to as rigid if it cannot be bent or forced out of shape. It is known for its strength and lack of flexibility while also providing things with support and structure. Plastic bottles and boxes, aluminum cans, glass jars, and corrugated and paperboard boxes are a few examples of rigid packaging materials. Cereal boxes, glass liquor bottles, soup cans, and detergent bottles are only a few examples of recognized uses. Flexible packaging protects products from severe heat, corrosion, moisture, and other environmental harmful forces. Rigid packaging is a suitable substitute. With regard to the increased attention of stakeholders, there are quite a few innovations occurring in that field as well as several product advancements.
In rigid packaging solutions, new plastic grades and versions are used to enhance the quality of the packaging that safeguards against external risks. The market is being driven by various factors including the growing food & beverages industry, increasing personal care and cosmetic sector, rising R&D investments, growing product launches, and increasing e-commerce industry.
According to the Australian Institute of Health and Welfare, Australia spent a predicted $220.9 billion on health-related products and services in 2020–21, or $8,617 per person on average. Total health spending (recurrent and capital) increased by 7.1% in real terms over 2019–20 (inflation-adjusted). Even while this growth was higher than the 3.4% average annual growth rate for the ten years leading up to 2020–21, it primarily reflected a return to pre–pandemic health spending trends, especially for non–government spending. Australia's health expenditures made up 10.7% of the country's GDP in 2020–21, an increase of 0.5 percentage points from 2019–20. The overall health spending in 2020–21 was $156 billion, or 70%, supported by the government, and the remaining 29%, or $64.9 billion, was funded by non–government sources.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 244.50 Billion |
| Market Size in 2026 | USD 256.63 Billion |
| Market Size by 2035 | USD 395.31 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 4.92% |
| Largest Market | Asia Pacific |
| Fastest Growing Market | North America |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | By Material and By Application |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Market Dynamics
Driver
Growing demand from the healthcare industry
The governments of developing nations in many regions are investing in modernizing the healthcare systems, particularly in the era of a pandemic. As rigid plastic packaging is durable, hygienic, transparent, and lightweight, it protects medicines from contamination and is ideal for keeping medical products including tablets, syringes, surgical supplies, syrups and other products. Rigid packaging is expected to become more popular on a global scale as a result of the expanding healthcare industry. For instance, as per the China National Health Commission, the total size of China's healthcare industry will reach $2.39 trillion by 2030. Thus, the increasing healthcare industry in developing nations is expected to propel the market growth over the forecast period.
Restraints
Environmental impact of plastics
High-density polyethylene (HDPE), expanded polystyrene (EPS), polyethylene terephthalate (PET), and polyvinyl chloride (PVC) are the polymers that are most frequently utilized in the packaging industry. Different industries use rigid plastic packaging to protect and sustainably store packed goods like industrial equipment, food, and medical supplies. Recycling, reusing, and segregating plastic garbage is the main issue posed by these plastics. Plastic packaging materials can take up to a thousand years to breakdown in landfills, causing pollution of the land and water. Furthermore, plastics lose mechanical strength when exposed to direct sunshine, while thermoplastics creep and soften at room temperature. Thus, the environmental impact of plastics on environment is one of the major restraints that hamper the market growth during the forecast period.
Opportunities
Increasing uses of rigid packaging in personal care and cosmetic industry
Rigid plastic packaging is used in the personal care and cosmetics sector to package goods for use in sun care, oral care, skin care, body care, perfume, decorative cosmetics, and hair care. This gives the goods frictionless storage and a longer shelf life. In emerging nations, the market for cosmetics and personal care products is expanding quickly, which is driving up demand for rigid plastic packaging. For instance, the Malaysian International Trade Administration estimates that the global market for cosmetics and personal care would expand at a compound annual growth rate of 4% by 2025. Thereby, this is expected to drive the market growth over the forecast period.
Technological Advancement
Technological advancement in the rigid packaging market features smart packaging, advanced materials, manufacturing processes, design innovations, automation and robotics, and AI and machine learning. Innovative technological methods used in material processing include lightweight composites, which use durable composite materials to reduce shipping costs and material usage. Another is biodegradable plastics, which promotes environmental concern and the practice of sustainable packaging.
Advancements in manufacturing processes include multi-material molding, injection molding, blow molding, and extrusion. Extrusion, blow molding, and injection molding a traditional methods that can be converted into advancements and automation to accelerate production efficiency and enhance quality. The multi-material molding process is used in creative packaging.
Smart packaging consists of QR codes and RFID, AI and IoT, and sensors and active packaging. AI and IoT help in monitoring, real-time tracking, and analyzing products by providing data on environmental conditions and the quality of the product. Sensors in the rigid packaging market monitor humidity, temperature inside the package to ensure product safety. QR codes and RFID trace products and authenticate the verification process.
Segment Insights
Material Insights
Based on the material, the global rigid packaging market is segmented into plastic, metal, paper & paperboard, glass and bioplastic. The plastics segment is expected to capture the largest market share over the forecast period. The widespread use of polyethylene terephthalate (PET) bottles in a variety of sectors, including the food, beverage, and pharmaceutical industries, is responsible for this increase. The rigid thermoform plastic packaging industry is supported by thermoforming due to its advantages. The U.S. Food And Drug Administration (FDA) has approved the widespread use of polystyrene in packaging, which can reduce the risk of foodborne disease in households and is fueling this market's expansion.
On the other hand, paper & paperboard segment is growing at the highest CAGR during the projection period. Paper containers, also referred to as paper packaging, are a high-efficient and affordable alternative that people can use to move, carry, and store a variety of things. Paper-based packaging is increasingly being used because it can be customized to match the needs of a particular product or consumer and is designed to be strong yet lightweight. Moreover, the use of paper-based packaging will contribute to a sustainable, safe, and healthy environment, among many other advantages because it is made from renewable resources. Thus, owing to these properties the segment will drive the market growth.
Application Insights
Based on the application, the global rigid packaging market is divided into food & beverages, pharmaceuticals, personal care, and others. The food & beverages segment is expected to grow at a significant rate over the forecast period.
The containers benefit from the rigid plastic packaging's flavor-absorbing, long-lasting, lightweight, and durable qualities. The food item is kept safe and contaminant-free in rigid plastic packaging containers including bottles, cans, and jars, among others. In developing nations including the United States, Canada, China, India, and other nations, there is a swiftly growing demand for rigid plastic packaging. Demand for rigid plastic packaging is being driven by the food and beverage industry's continued expansion. For instance, the China Chain Store & Franchise Association estimates that the country's food and beverage (F&B) market grew by 7.8% from 2018 to 2019, reaching over US$595 billion.
Additionally, the Food Export Midwest USA reported that the USDA's Office of Agricultural Affairs (OAA) in Rome stated that Italy's food retail sales in 2019 were US$145 billion, an increase of 1% from the previous year. Thus, this is expected to drive the market growth over the forecast period.
Regional Insights
What is the Asia Pacific Rigid Packaging Market Size?
The Asia pacific rigid packaging market size accounted at USD 124.70 billion in 2025 and is expected to be worth around USD 204.14 billion by 2035, growing at a CAGR of 5.05% between 2026 and 2035.

The Asia Pacific is expected to capture the largest market share over the forecast period. The growth in the region is attributed to the growing food & beverages and personal care & cosmetics industry particularly in India and China. The most recent analysis from Euromonitor International indicates that $88 billion worth of beauty and personal care products were sold in China in 2021, an increase of 10% from the previous year. The China Chain Store & Franchise Association also reports that the food and beverage market in China reached $595 billion in 2019, up 7.8% from 2018. Thus, the aforementioned facts support the market growth over the forecast period.
Asia Pacific is dominating the rigid packaging market. Factors influencing the region to grow are urbanization, industrialization, and an increase in the food and beverages sector. Mainly, China's contribution to the highest market share and the emerging economies expands the market globally.
North America is expected to grow at a significant rate over the forecast period. The robust advancements in the rigid thermoform plastic packaging industry are responsible for this region's expansion. Numerous benefits of thermoforming include its lower cost and adaptability. The rigid thermoform plastic packaging industry has seen enormous growth in product manufacture, creating a sizable client base that is fueling the expansion of the North American rigid packaging market.
Europe is expected to grow at a fast rate during the forecast period because the food and beverage industry has a rising requirement for rigid packaging solutions. Due to the presence of some of the biggest food and beverage companies in the region, there will certainly be an increase in the need for rigid packaging solutions. Additionally, the rising demand for personal care and cosmetic products from this region is anticipated to fuel market revenue growth. For instance, the manufacture of body care products and perfumes in Germany generated revenues of USD 4223 million and USD 3020 million respectively in 2022, according to the Federal Statistical Office. Therefore, the aforementioned stats drive the market expansion over the forecast period.
Latin America Packaging and Manufacturing Growth
Latin American market experiencing significant growth, due to the increasing number of food processing companies in the region, urbanisation, and a growing need for durable goods, both rigid packaging and the region's local manufacturing of rigid packaging are on the rise.
In Brazil, the food and beverage manufacturing industry is also contributing to an increase in rigid packaging consumption and will continue to do so due to investment in local manufacturing facilities and infrastructure for the recycling of rigid packaging materials. Brazil is also experiencing growth from the sustainable packaging initiatives of its government.
Middle East & Africa (MEA) Infrastructure Leading to Packaging Opportunities
The MEA region is a fast-growing area for packaging, as industrial processes change, retail companies build more stores, and the demand for packaged products continues to increase. The consumption of rigid packaging will continue to rise in the region, due to its ability to withstand extreme weather conditions.
Saudi Arabia Rigid Packaging Market Trends
Saudi Arabia is leading the way in the MEA region with the amount of growth currently taking place due to the increase in investments to help support food security, expanded production of pharmaceutical products, and the overall development of Vision. The increased need for rigid packaging materials will continue to support this substantial growth.
Rigid Packaging Market Value Chain Analysis
- Raw Material Sourcing & Polymer Processing: Manufacturers are increasingly using recycled polymers and lightweight materials to comply with sustainability goals for regulations or brands while also having an acceptable level of structural integrity.
Key Players: SABIC, BASF SE, Dow Inc. - Packaging Design, Molding & Container Manufacturing: This component is focused on advanced molding technologies such as injection molding, blow molding, and thermoforming. There is an increased level of innovation with regard to advancements in barrier protection, tamper-resistant, and shelf-life enhancements for pharmaceuticals and food.
Key Players: Amcor Plc, Berry Global Inc., Silgan Holdings. - Distribution, Branding & End-User Integration: Finished products are shipped to brand owners or manufacturers of FMCGs for use and modification according to the customer's requirements.
Key Players: Ball Corporation, Crown Holdings, DS Smith.
Competitive Landscape
The rigid packaging market is marked by innovation and sustainability. Leading companies such as Amcor plc, Ball Corporation, Crown Holdings Inc., Berry Global Inc., Silgan Holdings Inc., Mondi plc, Sonoco Products Company, Sealed Air Corporation, Huhtamaki Inc., and Alpla Werke Alwin Lehner GmbH & Co KG hold substantial market shares. They achieve this through diversified packaging portfolios, strong customer relationships, global manufacturing networks, and continuous advancements in recyclable materials, barrier technologies, and packaging functionality. As demand increases for durable packaging solutions, circular packaging models, product differentiation, and material efficiency, these leading companies are expected to enhance their competitive positioning through packaging innovation, strategic partnerships, and expanded manufacturing capacity.
Company Profiles
Amcor plc
Founded: 1986
HQ: Zurich, Switzerland
Business Overview: Amcor plc is a multinational packaging company that develops and produces flexible packaging, rigid containers, specialty cartons, closures and services for food, beverage, pharmaceutical, medical-device, home and personal-care, and other products
- Products: Amcor's rigid packaging solutions include rectangular containers, jerry cans and trigger spray bottles. The rectangular containers can be produced in up to 100% post-consumer recycled (PCR) plastic.
- Revenue: Revenue for the quarter ending June 30, 2026 was $6.398B, a 25.9% rise year-over-year. Revenue for the twelve months ending June 30, 2026 was $23.506B, a 56.61% growth year-over-year.
- Geographic Presence: The company spans Europe, North America, Latin America, the Middle East, Africa, and the Asia-Pacific regions.
- Recent developments: In June 2026, Amcor displayed its expanded portfolio of rigid and flexible packaging solutions at Packaging Innovations & Empack 2026 in Birmingham.
COVERIS
Founded: 2013
HQ: Vienna, Austria
Business Overview: COVERIS is the sixth-largest plastic packaging company globally. It was formed through the combination of Exopack, Britton Group, Kobusch, PACCOR, and Paragon Print & Packaging. The company is a well-established leader in the development, manufacture, and sourcing of both flexible and rigid plastic and paper packaging, as well as coating solutions.
Products: They offer fiber-based and hybrid alternatives, such as BarrierFresh MAP trays, which replace rigid plastic packaging.
- Geographic Expansion: Coveris is headquartered in Vienna and operates 29 facilities across Germany, France, the UK, Austria, Hungary, and Egypt.
- Revenue: In 2026, the Coveris Group reported annual revenue of $1 billion. In April 2026.
- Recent Development: Coveris announced targeted investments of €1.8 million to strengthen its production capabilities in Central and Eastern Europe, specifically in its two manufacturing plants in Poland.
Berry Global Group, Inc.
Founded: 1967
HQ: Evansville, Indiana
Business Overview: Berry Global Group, Inc. is another leading global manufacturer and marketer of innovative packaging and engineered products. Berry Global has experienced significant growth through strategic acquisitions and organic development. With a strong focus on customer satisfaction and operational excellence, the company has established itself as a key player in the packaging and engineered materials industry.
- Products: Berry Global offers a range of innovative flexible and rigid packaging solutions, specialty cartons, closures, and services, including best-in-industry polyethylene (PE) shrink. Geographic Presence: The company operates over 290 locations worldwide and employs more than 46,000 people.
- Revenue: For the twelve months ending March 29, 2025, Berry Global reported revenue of $10.124 billion. Between fiscal years 2020 and 2024, the company averaged $12.107 billion in revenue.
- Recent Development: In December 2024, Berry Global and VOID Technologies announced their successful collaboration to commercialize a new high-performance polyethylene film designed for pet food packaging.
Sonoco Products Company
HQ: Hartsville, South Carolina
Founded: 1889
Business Overview: Sonoco Products Company is an American provider of diversified consumer packaging, industrial products, protective packaging, and packaging supply chain services. Sonoco is the world's largest producer of composite cans, tubes, and cores, with annual net sales of approximately $7.3 billion.
- Products: The company operates through two reportable segments like Consumer Packaging and Industrial Paper Packaging. The Consumer Packaging segment provides rigid packaging solutions primarily for food, beverage, household, personal care, and pharmaceutical products. In contrast, the Industrial Paper Packaging segment produces paper-based packaging materials, such as tubes, cores, and protective packaging.
- Geographic Presence: Sonoco has approximately 19,900 employees across more than 335 operations in 33 countries, serving over 85 nations.
- Revenue: For the twelve months ending June 30, 2026, Sonoco reported revenue of $7.461 billion, reflecting a year-over-year increase of 17.73%.
- Recent development: In December 2024, it was announced that Sonoco had agreed to sell its Thermoformed Flexible Packaging business (TFP) to TOPPAN Holdings for approximately USD 1.8 billion.
Sealed Air Corporation (SEE)
HQ: Charlotte, North Carolina
Founded: 1960
- Business Overview: Sealed Air Corporation is known for its Cryovac food packaging and Bubble Wrap cushioning products. In November 2025, private equity firm Clayton, Dubilier & Rice agreed to acquire Sealed Air for a total enterprise value of $10.3 billion, a transaction completed on April 9, 2026.
- Products: The company offers films, trays, packaging equipment systems, and easy-open packaging solutions that help preserve food, protect goods, and automate packaging processes. The company markets its products under various brand names, including OptiDure, Cryovac, Bubble Wrap, Autobag, Liquibox, and Sealed Air.
- Revenue: For the quarter ending December 31, 2025, Sealed Air reported revenue of $1.401 billion, a year-over-year growth of 2.05%. For the twelve months ending December 31, 2025, the company's revenue was $5.360 billion, a slight decline of 0.61% year-over-year.
- Geographic Presence: Sealed Air operates in countries across the Americas, Europe, Africa, the Middle East, and Asia Pacific.
- Recent developments: In August 2026, Sealed Air expanded its paper cushioning portfolio with the introduction of the SEALED AIR brand ProPad Mini, a compact system formulated to improve the company's scalable protective packaging strategy for space-constrained fulfillment operations.
Rigid Packaging Market Companies
- Bemis Company, Inc.
- Amcor Limited
- Coveris Holdings S.A
- Reynolds Group Holding
- Berry Plastics Corporation
- Sonoco
- Sealed Air Corporation
- Silgan Holdings, Inc.
- Plastipak Holdings, Inc.
- Consolidated Container Company
- DS Smith PLC
- Ball Corporation
Recent Development
- In April 2025, SCG Packaging invested in rigid packaging businesses in America by focusing on building a production facility. The company's international expansion will benefit the business.
- In April 2025, IPL and Scholler Allibert merged to create a USD 1.4 billion reusable packaging powerhouse. The announcement of a landmark merger to build a formation in reusable plastic packaging is an eco-friendly contribution to the environment.
- In February 2025, Amcor explored the use of Avantium's Releaf product in rigid packaging. Avantium NV has signed a joint development agreement with Amcor Rigid Packaging USA LLC to gain insights into the use of Avantium's plant-based polyethylene furanoate.
- In May 2023, the first paperboard tube with a fiber-based closure has been created by Stora Enso, Blue Ocean Closures, and AISA. Brand owners can enhance the proportion of renewable material in their packaging by using this brand-new, cutting-edge wood fiber approach. The tube's components are all made to be recycled. The tube is made of Natura ShapeTM, a barrier-coated board from Stora Enso, and a screw cap created in partnership with Blue Ocean Closures, with assembly provided by AISA. The solution has the largest fiber content attainable in a tube design—more than 85%. It is anticipated to go on sale in 2024 and be used in cosmetic and personal care products.
- In September 2022, Sonoco officially agreed to buy privately held Danish paper firm Skjern for USD 88 million in cash. As a result of the acquisition, Sonoco will be able to modernize operations across Europe and neighboring regions and boost client production capacity. The purchase is in line with the packaging company's objective of developing the market for sustainable paper and packaging products in Europe while investing in its core business.
- In September 2022, to create DairySeal, a novel PET barrier technology for dairy beverage containers, Amcor Rigid Packaging (ARP) created ClearCor. The bottles are recyclable and their fabrication may use up to 80% recyclable materials. PET film has been used by ARP to produce a barrier that keeps dairy products taste good. The preform's core has a "concentrated capsulation" made by new technology developed by ClearCor, which allows the containers more flexibility and resin options.
Segments Covered in the Report:
By Material
- Plastic
- Metal
- Paper & Paperboard
- Glass
- Bioplastic
By Application
- Food & Beverages
- Pharmaceuticals
- Personal Care
- Others
By Regional
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample




 sales@precedenceresearch.com
 Schedule a Meeting
