
AI in Education Market Size, Key Companies, Company Product Portfolio, Digital Transformation, Technology Investment, Adoption Rates, Customer Acquisition, Company Market Share, and Market Outlook
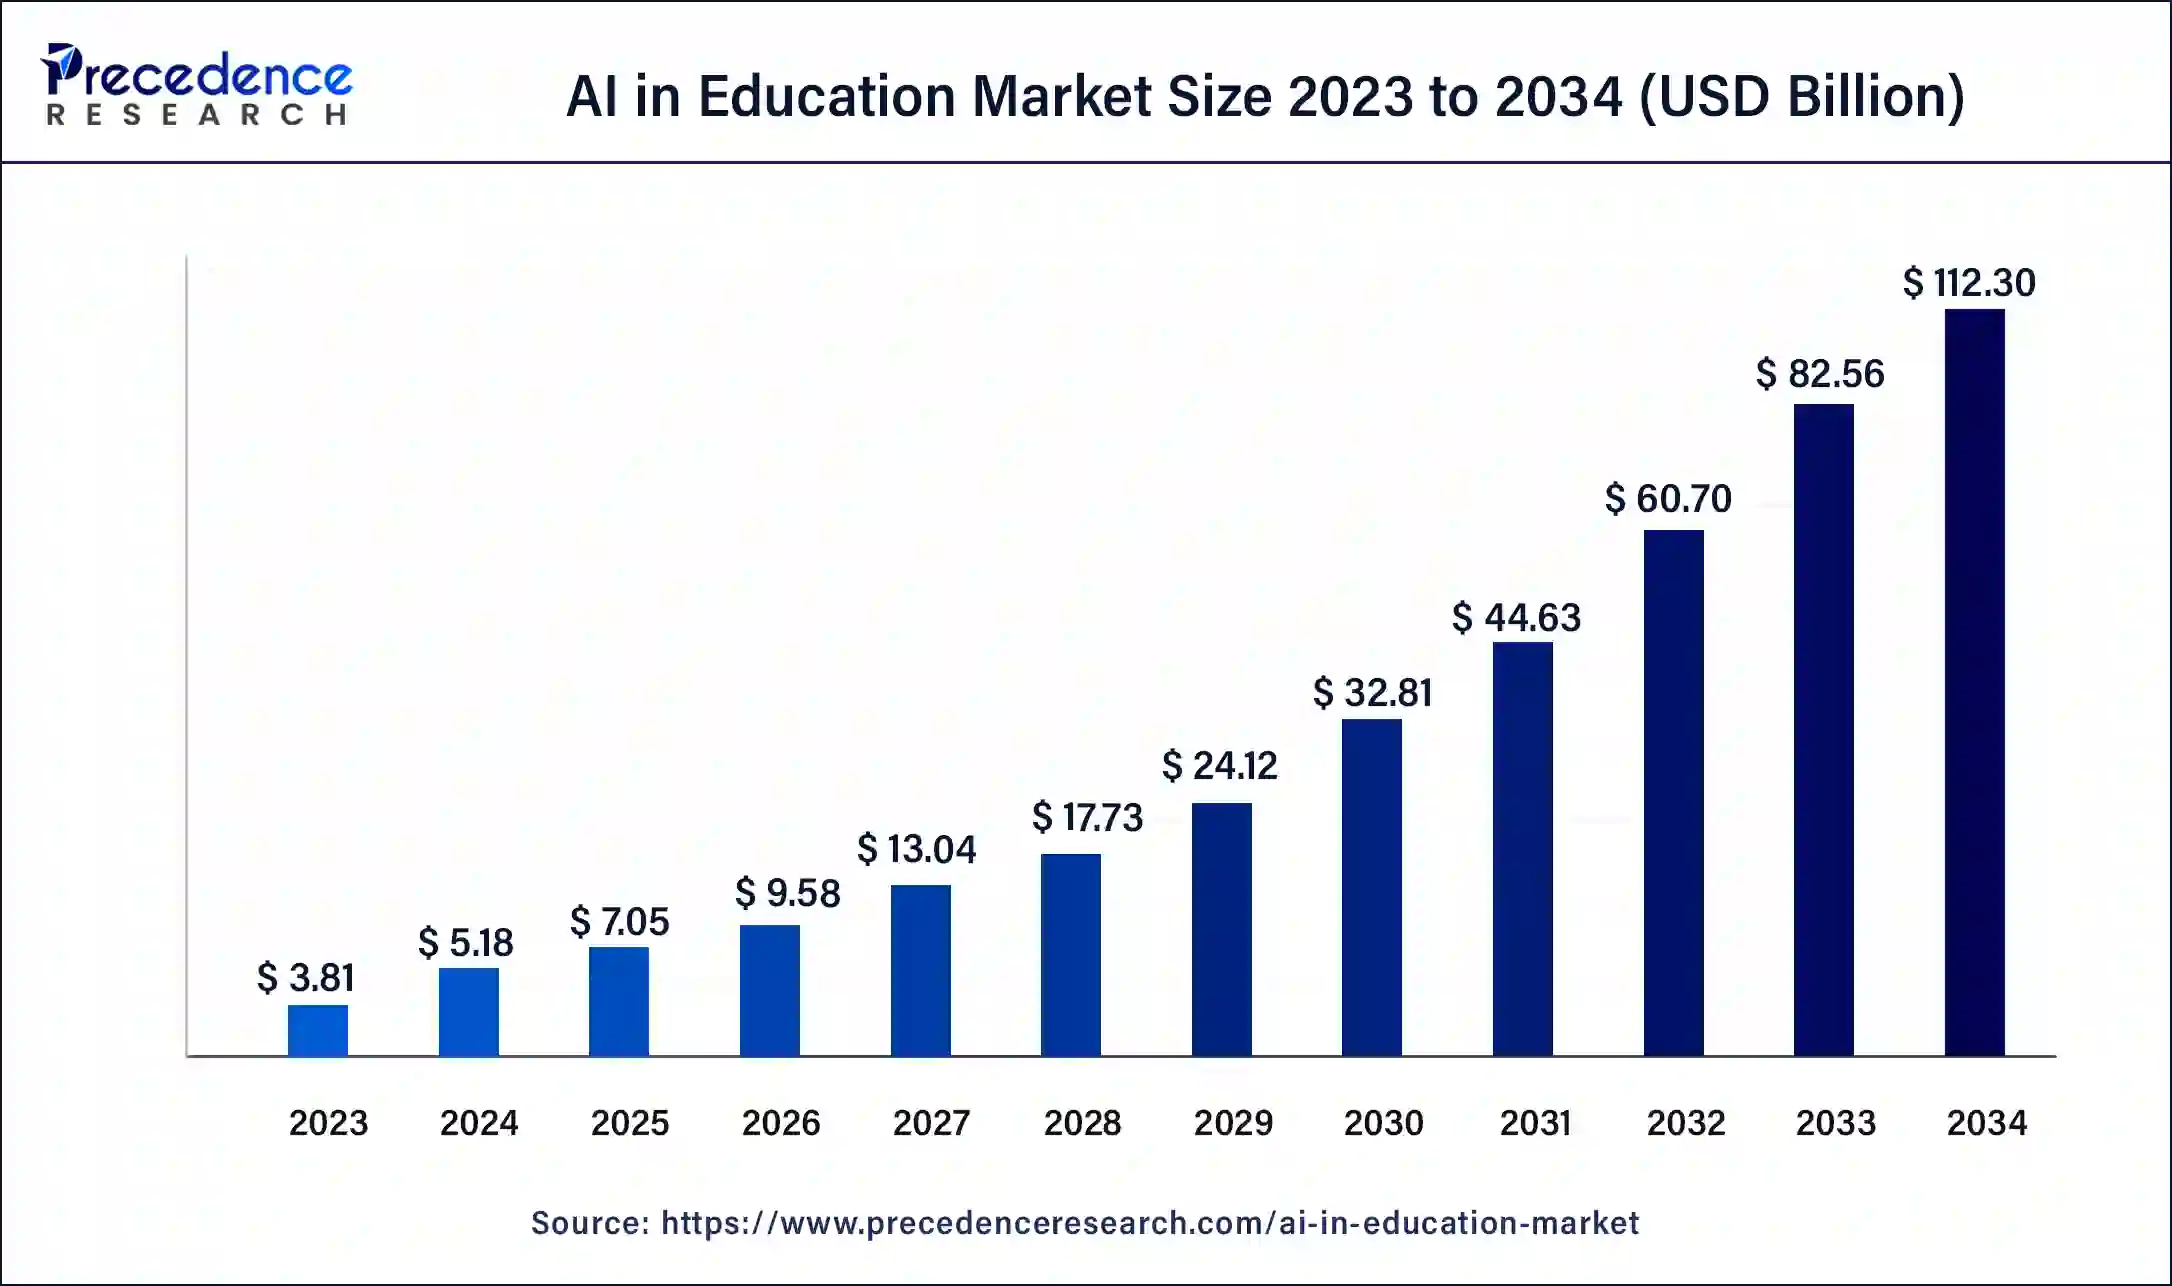
The global AI in education market is being driven by the adoption of generative AI, variety in personalized learning, intelligent and automated assessment, and AI-enabled platforms. It's estimated at USD 9.58 billion in 2026 and expected to hit USD 136.79 billion by 2035, growing at 34.52% CAGR. The growth is coming from rising AI use across K-12, higher education, and corporate learning, plus demand for personalized instruction, teacher productivity, and automated student support. The biggest opportunities lie in generative AI, adaptive learning, AI assessment, multilingual education, and workforce reskilling, while privacy, governance, integration, and proof of learning outcomes will shape the winners.
Source: https://www.precedenceresearch.com/ai-in-education-market
 Get a Sample
 Table Of Content


What is the AI in Education Market Size?
The global AI in education market size is calculated at USD 9.58 billion in 2026 and is predicted to increase from to approximately USD 136.79 billion by 2035, expanding at a CAGR of 34.52% from 2026 to 2035.
Overview - AI in Education is Moving From Experimental EdTech Feature to Core Learning Infrastructure
The global AI in education market is estimated at USD 9.58 billion in 2026 and is projected to reach USD 136.79 billion by 2035, representing a CAGR of 34.52%, depending on market boundaries and the treatment of embedded AI revenues. This wide range shows a market still being defined, since some estimates capture only dedicated AI education software, while broader frameworks include AI-enabled learning platforms, services, tutoring, assessment, and institutional deployments.
The shift in structure matters more than headline growth rate. K-12, higher education, and corporate learning all use AI on a large scale, with generative AI speeding up content creation, tutoring, assessment, translation, and learner support. PISA 2025 data shows AI chatbot use for schoolwork is now widespread, with 45.5% of OECD students using it at least weekly to help them learn. How that use affects academic performance still depends a lot on purpose, frequency, and quality of implementation. (OECD).
The market is entering a second phase, with competitive advantage shifting from simply having an AI feature to owning learner data, workflow integration, trusted content, assessment infrastructure, and measurable learning outcomes. The full study quantifies this transition across AI-native applications, embedded AI, institutional software, services, deployment models, end users, applications, and geographies.
Key Coverage
- Historical growth and AI adoption trajectory
- K-12, higher education, and corporate learning demand
- Generative AI penetration and application economics
- Regional growth and market-development differences
- AI tutoring, assessment, content, and administration opportunities
- Market maturity, fragmentation, and competitive concentration
Market Size - Generative AI is Expanding the Addressable Education Technology Revenue Pool
This spread is itself a major research issue. AI is now built into learning management systems, assessment platforms, language-learning products, and enterprise learning software, making revenue attribution difficult. So our analysis separates dedicated AI revenue, AI-enabled software revenue, and AI-related services instead of treating every education technology dollar as AI revenue.
The full report builds a bottom-up market model using institutional deployments, learner subscriptions, AI-enabled seats, enterprise contracts, services, and application-level adoption, with base, upside, and downside scenarios.
Key Coverage
- USD 30+ billion potential incremental opportunity
- AI-native versus embedded AI revenue
- Regional and end-user contribution
- Base/upside/downside scenarios
- Revenue attribution by application
Segmentation Analysis - Higher Education Leads Institutional Adoption While Adaptive Learning and AI Tutoring Capture High-Value Growth
The market is best segmented by offering, technology, application, end user, deployment model, and business model. Current estimates indicate that higher education holds roughly 45% of market demand, while solutions account for approximately 70% of revenue in some market frameworks. Cloud deployment generates about 60% of revenue, reflecting how dominant subscription-based and remotely delivered AI services have become.
Application economics are now shifting toward adaptive learning, intelligent tutoring, AI assessment, virtual learning assistants, content generation, and student-support automation. Generative AI and deep-learning applications are among the fastest-growing technology pools, with some estimates putting their growth above 45% CAGR. Corporate training is also turning into a high-growth segment as AI enables personalized skills pathways and scalable coaching.
Key Coverage
- K-12, higher education, and corporate learning
- Intelligent tutoring systems
- Adaptive learning
- AI assessment and grading
- Content generation
- Virtual assistants
- Student analytics
- Generative AI
- Cloud, hybrid, and on-premise deployment
- Consumer, institutional, and enterprise pricing models
Market Dynamics - Personalization is the Demand Engine, but Trust Determines Commercial Conversion
Three things are pushing adoption along faster. Schools and institutions want more personalized learning, teachers need their time back, and administrative work keeps piling up. AI can explain things on the fly, adjust difficulty as a student goes, give feedback, summarize content, translate materials, and answer student questions. It matters most where institutions are dealing with large numbers of learners and don't have the instructional resources to match.
But adopting AI isn't the same as using it well. PISA 2025 found that students who lean on AI for specific tasks like drafting or summarizing perform differently than those who don't, while more moderate, purposeful use for learning shows a different pattern with outcomes. So AI literacy, redesigning how assessments work, and putting real institutional governance in place are becoming just as important to commercial adoption as the technology itself. (OECD)
The report also weighs these demand drivers against the real barriers: privacy concerns, hallucination, academic integrity, pushback from teachers, integration costs, unequal digital access, and the simple fact that measurable learning outcomes are still hard to pin down.
Pricing Analysis - AI Education Economics Are Shifting From Software Licenses Toward Outcome-Based and Usage-Based Models
AI in education is developing several pricing models, including per-learner or per-seat subscriptions, institutional licenses, usage-based AI consumption, premium tutoring subscriptions, API-based pricing, enterprise contracts, and professional services.
Consumer AI learning products can monetize monthly subscriptions, while institutional platforms often combine annual licenses with implementation and support. The main economic variable is AI inference cost, since highly interactive tutoring and conversational applications can carry far higher variable costs than static AI-assisted content generation.
So our analysis evaluates ARPU, annual contract value, price per active learner, gross-margin sensitivity to AI usage, customer acquisition cost, retention, churn, and service revenue contribution. The deeper analysis models premium pricing for high-touch tutoring against cheaper AI-assisted content and assessment products.
Key Coverage
- Consumer subscription pricing
- Institutional license economics
- Enterprise contract values
- AI usage costs
- ARPU and ACV
- Gross-margin implications
- Premium versus mass-market positioning
- Pricing elasticity and retention
Demand-Supply Analysis - AI Demand Is Scaling Faster Than Institutional Readiness
AI usage is already well ahead of formal institutional integration. PISA 2025 shows that a majority of students in most participating countries use AI chatbots for schoolwork, but regular, almost daily use stays much lower. Around six in ten OECD students report being taught to assess the quality of AI-generated information, suggesting that formal AI literacy is developing alongside informal usage. (OECD)
So supply is not held back mainly by model availability. The limits are curriculum integration, data governance, teacher capability, procurement processes, and evidence of learning impact. The full report maps this demand-supply gap by region and education level, identifying markets where AI usage is high but institutional monetization stays underdeveloped.
Value Chain and Supply Chain - Value is Migrating Toward Data, Content, Workflow Integration and Learner Relationships
The AI-in-Education value chain spans foundation models and infrastructure → education data → AI applications → content and curriculum → learning platforms → institutions/teachers → learners.
The highest strategic value is now concentrated downstream, where AI is connected to proprietary educational content, learner histories, assessment data, and institutional workflows. Generic model capabilities are becoming more accessible, cutting differentiation at the model layer while raising the importance of domain-specific data, pedagogy, safety, and distribution.
The full study tracks value capture across software, infrastructure, implementation, content, and services while identifying integration bottlenecks and areas of supplier concentration.
Technology and Innovation - Which AI Technologies are Most Likely to Reshape Education Software and Learning Delivery Through?
Generative AI is now widening the technology stack of education software from primarily predictive and rules-based analytics to conversational tutoring, automated content generation, multimodal instruction, real-time feedback, voice-based learning, and adaptive assessment. Adoption is already moving beyond experimentation, with PISA 2025 data showing that 45.5% of students across OECD countries reported using AI chatbots at least weekly for learning help, confirming that generative AI is becoming part of mainstream learner behavior rather than a niche technology. The technology stack is also broadening across large language models, natural language processing, computer vision, speech AI, recommender systems, retrieval-augmented generation, and agentic AI.
The most commercially important shift is from standalone generative-AI features toward domain-specific AI embedded directly into learning workflows. This distinction matters because generic content generation can steadily become commoditized, whereas AI systems that combine curriculum-aligned content, learner profiles, assessment data, institutional knowledge, and real-time feedback can create much higher switching costs. AI tutoring, adaptive learning, automated assessment, and teacher copilots are likely to be the most strategically important application layers, since they directly influence instructional productivity and learner engagement. Multimodal and voice-based AI should also expand the addressable market by enabling more natural interaction across languages, age groups, and learning environments.
The bigger competitive question is whether a company can actually commercialize and integrate its AI, not just how capable the underlying model is. Providers have to get the balance right between accuracy, explainability, age-appropriateness, privacy, curriculum fit, and keeping a human in the loop, especially anywhere AI touches assessment or a student's progress. That favors platforms pairing foundation models with proprietary content, real learner data, and workflows schools already use, and it puts more weight on governance and the economics of actually deploying this stuff. The full report benchmarks technology maturity across the major AI architectures and application types, looking at product launches, R&D spend, patents, partnerships, model integration, deployment scale, and how far along commercialization actually is.
This intelligence can also be structured into a technology and innovation database, tracking company, AI technology, model architecture, application, product, launch year, deployment status, partnership, patent activity, R&D investment, target end user, geography, and commercialization stage. These records can be filtered by technology maturity, application, company, geography, and year, enabling granular benchmarking of emerging technologies and showing where innovation is moving from pilot deployments to scaled commercial adoption.
Regulatory & Sustainability Analysis - Privacy, Safety, and AI Literacy Are Becoming Commercial Requirements
Regulatory pressure is rising quickly. AI systems used for certain education and vocational-training functions in the European Union, including systems used to evaluate learning outcomes or steer learning processes, can fall into high-risk AI categories. (Digital Strategy)
Education-specific governance is also catching up, covering privacy, transparency, bias, human oversight, and what counts as age-appropriate deployment. Global guidance has pushed hard on privacy protection and age safeguards for generative AI, and teacher competency frameworks now spell out 15 competencies across five dimensions, from AI ethics to AI pedagogy to ongoing professional learning. (UNESCO)
The report walks through regulatory exposure, compliance costs, what this means for procurement, AI governance, and sustainability questions like compute intensity and deploying AI responsibly.
Customer and Application Analysis - Institutional Buyers are Prioritizing Measurable Learning Outcomes Over AI Novelty
The customer base divides into students/parents, schools and districts, universities, vocational institutions, corporate learning organizations, and government education systems.
High-value applications include intelligent tutoring, personalized learning, assessment, language learning, student advising, content creation, administrative automation, and learning analytics. The purchasing decision now depends on integration with existing LMS infrastructure, privacy controls, teacher usability, evidence of outcomes, and total cost of ownership.
The full report gauges application penetration, learner engagement, retention, willingness to pay, institutional procurement criteria, switching costs, and customer concentration.
Competitive Landscape - The Market is Fragmenting Between Education Platforms, AI-Native Specialists and Technology Ecosystems
Competition is growing more multidimensional. Traditional education technology providers are embedding AI into established platforms, while AI-native specialists are attacking specific workflows such as tutoring, language learning, assessment, and content generation. Large technology platforms compete at the infrastructure and productivity layer, creating a third competitive group.
The result is a medium-to-highly fragmented competitive structure, with no single company controlling the full AI-in-Education stack. Competitive advantage now depends on distribution, proprietary content, learner data, institutional relationships, AI capability, and measurable learning outcomes.
Tentative Leading Company Universe
| Company | Headquarters | Market Position | Core Strength | Major Applications/Segments |
| Pearson | UK | Global education platform leader | Content + AI learning | K–12, higher education |
| Duolingo | US | AI-native learning platform | Adaptive language learning | Language learning |
| Coursera | US | Global digital learning platform | AI-enabled skills learning | Higher education, enterprise |
| Instructure | US | LMS leader | Institutional learning infrastructure | Higher education, K–12 |
| McGraw Hill | US | Education content leader | Digital curriculum | K–12, higher education |
| Cengage Group | US | Learning-content provider | Digital learning | Higher education |
| Anthology | US | Education software platform | Student lifecycle/LMS | Higher education |
| D2L | Canada | Learning platform specialist | LMS + adaptive learning | Education, corporate |
| PowerSchool | US | K–12 platform provider | Student information + analytics | K–12 |
| Stride | US | Digital education provider | Online schooling | K–12 |
| Kahoot! | Norway | Interactive learning platform | Engagement + assessment | K–12, enterprise |
| Quizlet | US | AI learning platform | Study tools | Students |
| Quizizz | India/US | Learning engagement platform | Assessment + classroom | K–12 |
| Carnegie Learning | US | AI learning specialist | Mathematics | K–12 |
| DreamBox Learning | US | Adaptive-learning specialist | Mathematics | K–12 |
| Age of Learning | US | Digital learning provider | Early learning | K–12 |
| Riiid | South Korea | AI tutoring specialist | Test preparation | Education |
| Squirrel AI | China | Adaptive learning specialist | Personalized tutoring | K–12 |
| Sana | Sweden | AI learning/workflow platform | Enterprise learning | Corporate |
| Alef Education | UAE | Regional education technology leader | AI-enabled learning | K–12 |
| OpenAI | US | Foundation-model ecosystem | Generative AI | Cross-education |
| Microsoft | US | Technology ecosystem | AI productivity + education | Institutional/enterprise |
| US | AI + education ecosystem | AI tools + classroom infrastructure | K–12/higher education | |
| Amazon Web Services | US | AI/cloud infrastructure provider | Cloud AI infrastructure | Institutional/enterprise |
| IBM | US | Enterprise AI provider | Analytics + AI services | Higher education/enterprise |
This is a tentative market-relevant universe rather than a definitive market-share ranking.
Market Share and Competitive Ranking - Revenue Pools are Distributed Across Multiple Strategic Layers
The market's fragmentation means that market share must be assessed separately for AI-native education software, AI-enabled education platforms, AI tutoring, language learning, institutional AI infrastructure, and education AI services. A single consolidated ranking can mask these structural differences.
The full analysis estimates company-specific market exposure, AI-attributable revenue, application share, geographic exposure, and growth. It also separates direct AI revenue from broader corporate revenue, avoiding the common distortion created when the entire revenue of diversified technology or education companies is attributed to AI in Education.
Competitive Benchmarking - Distribution and Proprietary Learning Assets Are Becoming as Important as Model Capability
Competitive benchmarking evaluates companies across AI functionality, revenue growth, education exposure, user scale, product breadth, content ownership, institutional relationships, cloud deployment, personalization, assessment capability, geographic reach, and strategic investment.
The analysis shows a major shift, because AI capability alone is becoming less differentiated as foundation models commoditize. Companies with large installed learner bases can potentially monetize AI faster because they already control distribution and behavioral data, while AI-native specialists can differentiate through superior domain-specific workflows.
Product Portfolio Benchmarking - Broad Platforms Compete With High-Depth AI Specialists
Portfolio analysis compares intelligent tutoring, adaptive learning, AI assessment, content generation, virtual assistants, language learning, student analytics, and administrative AI.
Bigger education platforms have an edge here, since they can cross-sell AI into contracts they already have, while smaller specialists tend to pour everything into one high-value workflow instead. The report points to gaps worth watching in multilingual tutoring, AI-native assessment, teacher copilots, special-needs education, vocational learning, and AI agents built for specific institutions.
Technology and Innovation Benchmarking - The Race is Moving Toward Domain-Specific AI and Agentic Learning
Benchmarking covers model integration, multimodal capabilities, voice AI, RAG, agentic workflows, AI tutors, adaptive engines, patents, R&D, partnerships, and commercialization.
The strategic differentiator is now the ability to combine foundation models with curriculum alignment, verified content, learner profiles, and institutional controls. The report maps technology maturity and flags which technology approaches are moving from experimentation to commercial deployment.
Application Competitive Benchmarking - Tutoring, Assessment, and Teacher Copilots Create Distinct Competitive Arenas
Application-level benchmarking maps companies across tutoring, adaptive learning, content creation, grading, language learning, student advising, academic integrity, and administrative automation.
AI tutoring is an especially important battleground because it directly monetizes learner interaction. Assessment is strategically important because it builds institutional switching costs, while teacher copilots can reach broader adoption by augmenting instead of replacing existing instructional workflows.
Geographic Competitive Landscape - North America Leads Commercial Maturity While Asia Pacific Represents the Fastest Expansion Pool
North America currently holds the largest commercial market in several industry estimates, while Asia Pacific is consistently identified as the fastest-growing major region, with some estimates placing regional growth above 44% CAGR.
Competitive differentiation varies widely by geography. North America is marked by mature institutional software and higher willingness to pay; Europe places greater emphasis on privacy and regulatory compliance; Asia Pacific combines large learner populations with rapidly expanding digital education ecosystems; and the Middle East is developing through government-backed education modernization.
Manufacturing and Capacity Benchmarking - Software Capacity is Defined by Compute, AI Talent and Institutional Deployment
Unlike physical EdTech markets, AI in Education has limited traditional manufacturing capacity. Capacity is instead determined by cloud infrastructure, model availability, data pipelines, AI engineering talent, content production, and implementation capacity.
The report therefore benchmarks compute dependency, cloud architecture, deployment scale, implementation resources, product development intensity, and localization capabilities rather than conventional factory capacity.
Customer and Channel Benchmarking - Installed Education Relationships Create Significant Switching Barriers
Institutional sales depend on procurement cycles, curriculum alignment, privacy requirements, LMS integration, and teacher adoption. Consumer products rely more heavily on app distribution, freemium conversion, engagement, and subscription retention.
The strongest channel positions are built where AI products become embedded in existing learning workflows. The report compares direct institutional sales, distributors, channel partnerships, LMS integration, consumer acquisition, and enterprise learning channels.
Strategic Developments - Product Embedding is Replacing Standalone AI Experimentation
The competitive landscape is moving from standalone AI demonstrations to embedded copilots, AI tutors, automated content generation, AI assessment, and personalized learning engines.
The strategic activity review covers product launches, institutional partnerships, AI integrations, curriculum agreements, cloud relationships, geographic expansion, and investment during the latest 2-3 years, showing where vendors are committing resources to recurring revenue instead of one-time experimentation.
M&A Landscape - Consolidation is Likely to Target Content, Data, Assessment and AI Capabilities
M&A activity is turning more strategic around four assets: proprietary educational content, learner data, institutional distribution, and AI capabilities.
The report evaluates acquisitions and investments by technology category, geography, customer base, and strategic rationale, identifying potential consolidation themes around adaptive learning, assessment, language learning, corporate reskilling, and AI governance.
Company Profiles - Detailed Intelligence on the Leading Market Participants
The full study provides standardized profiles of the 25-company universe covering:
- Headquarters, ownership, and organizational structure
- Education-related revenue exposure
- AI product portfolio
- User and institutional footprint
- Revenue growth and profitability
- R&D and AI investment
- Product launches and partnerships
- Geographic presence
- Customer segments
- AI capabilities and technology platforms
- Strategic developments and M&A
- Competitive strengths, vulnerabilities, and growth opportunities
Company Strategic Positioning - Competitive Advantage Is Shifting Toward Integrated AI-Education Ecosystems
The strategic positioning analysis classifies participants by market leadership, technology leadership, scale, growth orientation, regional strength, application specialization, and emerging-challenger status.
The analysis stresses that future positioning will depend less on generic access to AI models and more on the ability to combine trusted educational content + proprietary learner data + institutional distribution + measurable outcomes + responsible AI governance.
Opportunity and White-Space Analysis: The Largest Untapped Pools Sit Beyond Generic Chatbots
Here's where the biggest opportunities actually sit:
- AI-native tutoring with measurable learning outcomes
- Teacher copilots that reduce administrative workload
- AI assessment and formative feedback
- Multilingual and low-resource-language education
- Special-needs and accessibility applications
- Workforce reskilling and AI-enabled corporate learning
- AI governance and institutional compliance
- Personalized career navigation
- AI-powered student retention and intervention
- Emerging-market education localization
The report puts numbers behind each of these, looking at market size, how much of the opportunity is still untapped, adoption rates, pricing, and where CAGR is headed.
Industry Structure - Competitive Rivalry is High, but Entry Barriers Remain Uneven
Supplier power: Medium-High. Relying so heavily on foundation models, cloud infrastructure, and scarce AI talent gives a handful of suppliers real leverage.
Buyer power: Medium-High. Large education systems can dictate terms, pushing their own procurement rules, privacy standards, and integration demands onto vendors.
Threat of new entrants: Medium. It's gotten easier to build an application, but earning trusted content, distribution, and institutional sign-off is still a different challenge entirely.
Threat of substitutes: Medium. Traditional EdTech, human tutors, and plain old classroom instruction aren't going anywhere and still compete for the same budget.
Competitive rivalry: High. Tech companies, education platforms, and AI specialists are now bumping into each other across tutoring, content, assessment, and learning infrastructure all at once.
PESTLE Analysis - Regulation, Demographics and AI Capability Will Shape Market Development
Political and regulatory conditions influence procurement and AI governance; economic conditions determine education technology budgets and enterprise reskilling expenditure; social factors include teacher acceptance, student behavior, and digital inequality; technology is driven by model capabilities and declining AI costs; legal considerations center on privacy, intellectual property, transparency, and high-risk educational applications; and environmental considerations now include AI compute efficiency.
Market Attractiveness - Growth Potential Is Highest Where AI Solves Measurable Education Bottlenecks
Market attractiveness varies by application. High-growth opportunities generally combine large learner populations, recurring software revenue, measurable outcomes, high-frequency interaction, and limited existing personalization.
The full assessment evaluates each segment against market size, growth, monetization, competition, entry barriers, customer willingness to pay, regulatory complexity, technology intensity, and implementation requirements.
Future Outlook - AI Will Evolve From Learning Assistant to Intelligent Education Operating Layer
By 2030 to 2035, the market is likely to move beyond isolated AI features into persistent AI tutors, teacher agents, adaptive curricula, automated assessment, multilingual instructional systems, and AI-supported student advising. Generative AI already marks a major structural shift, while corporate learning is adding a second growth engine as demand for AI and digital skills climbs. For example, global enrollment in generative-AI courses on one major learning platform exceeded 10 million by mid-2025. (Coursera Blog)
The base case expects adoption to keep moving fast, just with better governance and integration behind it. Things could move even quicker if institutions warm up to AI sooner than expected, costs keep falling, and there's real evidence it's improving learning outcomes. On the other hand, slower procurement cycles, tighter regulation, privacy concerns, thin evidence on outcomes, or a backlash against badly governed AI could all drag adoption down instead.
Where the real money ends up is likely to center on AI tutoring, adaptive learning, assessment, workforce reskilling, teacher productivity, multilingual education, and platforms that tie all of this together.
Key Strategic Questions Addressed
- What is the global AI in Education market size in 2026 and 2035?
- How much incremental revenue will AI create across education software and services?
- Which end-user segments will generate the largest AI revenue pools?
- Which applications are growing fastest, including tutoring, assessment, content, analytics, or administration?
- How rapidly is generative AI replacing conventional education software functionality?
- What pricing models generate sustainable AI-in-Education economics?
- Where are institutional adoption and student usage diverging?
- Which regulatory requirements will materially affect product design and procurement?
- How important are proprietary learner data and educational content to competitive advantage?
- Which companies have the strongest combination of distribution, AI capability, and education assets?
- How fragmented is the competitive landscape across AI-native and established education platforms?
- Which technology architectures are likely to dominate through 2030?
- Where are the largest geographic and application-level white spaces?
- What M&A themes are likely to reshape the market?
- Which AI-in-Education business models are positioned to capture the next generation of education technology profit pools?
AI in Education Market Segments
By Offering
- AI-Powered Learning Platforms
- AI-Powered Tutoring Solutions
- AI-Powered Assessment Solutions
- AI Content Creation Tools
- AI Learning Assistants & Chatbots
- AI-Enabled Learning Management Systems
- AI Student Analytics & Predictive Analytics
- AI Administration & Automation Solutions
- AI Education Services
By Technology
- Machine Learning
- Generative AI
- Natural Language Processing (NLP)
- Large Language Models (LLMs)
- Computer Vision
- Speech Recognition & Conversational AI
- Recommender Systems
- Predictive Analytics
- Adaptive Learning Algorithms
- AI Agents & Agentic AI
By Application
- Personalized & Adaptive Learning
- Intelligent Tutoring
- Content Generation
- Assessment & Automated Grading
- Language Learning
- Student Engagement
- Learning Analytics
- Student Advising & Support
- Teacher Assistance
- Administrative Automation
- Academic Integrity & Plagiarism Detection
- Career Guidance & Skills Development
By End User
- K-12 Schools
- Higher Education Institutions
- Corporate & Enterprise Learning
- Vocational & Professional Training Institutions
- Government & Public Education Systems
- Individual Learners
By Deployment Model
- Cloud-Based
- On-Premise
- Hybrid
By Business Model
- Subscription-Based
- Freemium
- Usage-Based
- Institutional Licensing
- Enterprise Licensing
- Pay-Per-Use
- API-Based
- Professional Services
By Region
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- France
- Asia Pacific
- China
- Japan
- India
- South Korea
- Latin America
- Brazil
- Mexico
- Middle East & Africa
- Australia
- GCC Countries
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting