



Europe & Italy IVD Market Size, Key Companies, Company Production Capacity, Healthcare Infrastructure Growth, Product Utilization, Regulatory Compliance, Company Expansion Strategies, Company Investment Strategies, and Market Outlook
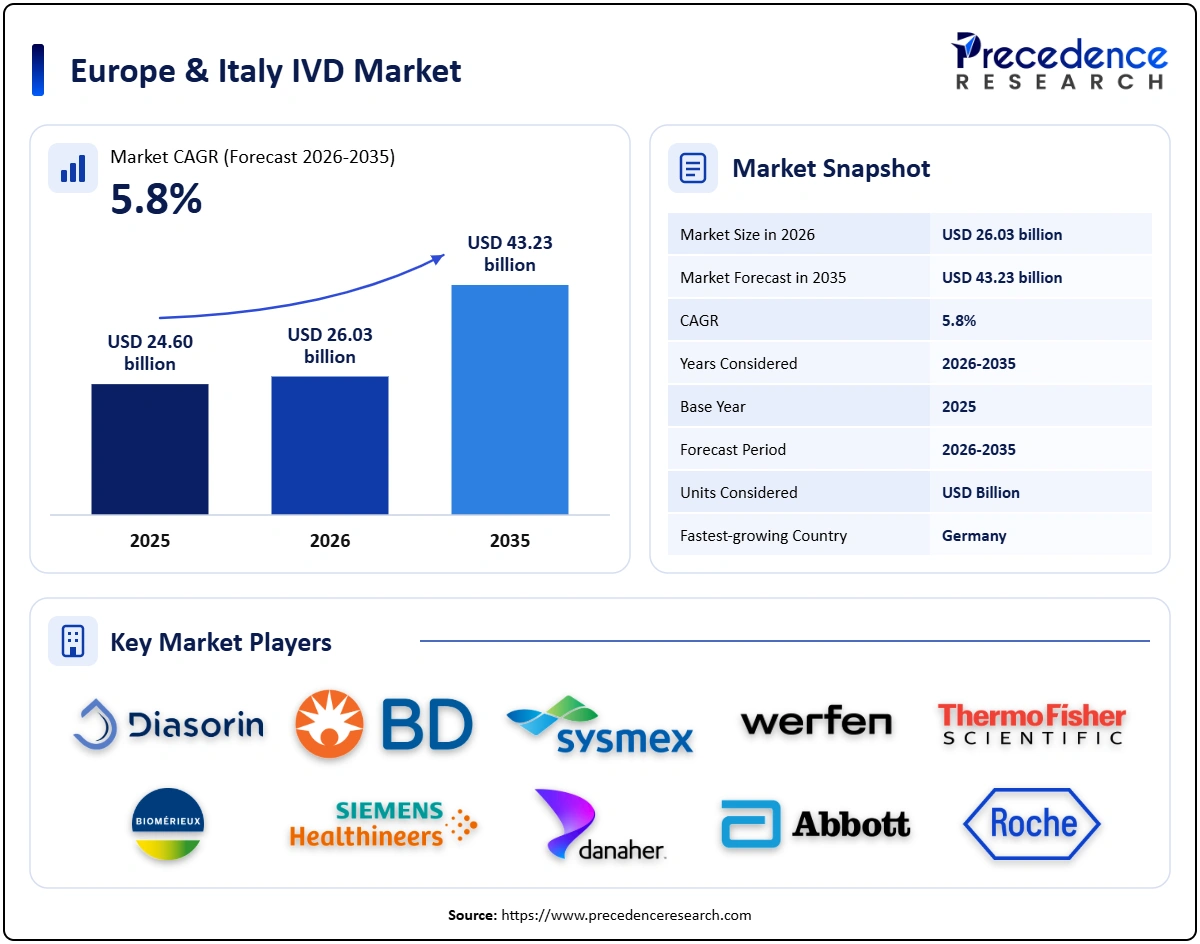
Payal Rabde, a Healthcare Industry Expert, highlights that the Europe and Italy IVD market has reached USD 26.03 billion in 2026 and is on track to reach USD 43.23 billion by 2035, advancing at a CAGR of 5.8%. Key Europe and Italy IVD market companies shaping the market include Thermo Fisher Scientific, Roche Diagnostics, Siemens Healthineers while major growth segments span product and service, technology, application, end user, and region.
Source: https://www.precedenceresearch.com/europe-italy-ivd-market
 Get a Sample
 Report Description
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 24.60 billion
- Estimated market size in 2026: USD 26.03 billion
- Projected market size by 2035: USD 43.23 billion
- CAGR (2026-2035): 5.8%
Regional Market Spotlight
- Rest of Europe: Accounted for 29.1% of the market in 2025, with a value of USD 7.16 billion.
- Germany: Held a 23.4% share of the European IVD market in 2025, valued at USD 5.76 billion.
- France: Accounted for 15.2% of the market in 2025, with a value of USD 3.74 billion.
- Italy: Represented 12.1% of the market in 2025, valued at USD 2.98 billion. The country is projected to record a CAGR of 6.61% from 2025 to 2035, the highest among European countries.
Segmental Spotlight
- By product and service, reagents and kits held the largest share in 2025, at 68.4% (USD 16.83 billion).
- By technology, immunoassays accounted for 30.6% (USD 7.53 billion) of the market in 2025.
- By application, autoimmune and other applications collectively accounted for 29.0% (USD 7.13 billion) of the market in 2025.
- By end user, hospitals held the largest share in 2025, at 48.6% (USD 11.96 billion).
Europe & Italy IVD Market Size and Forecast, 2025-2035 (USD Billion)
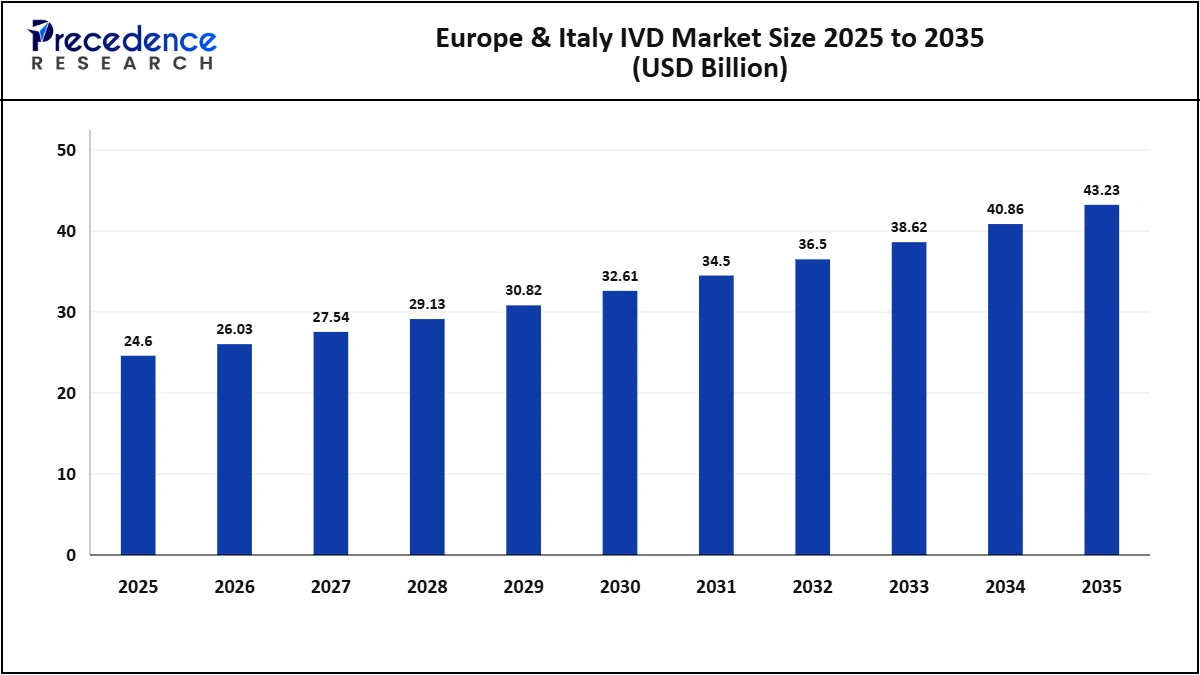
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The Europe and Italy IVD market is expected to increase from USD 24.60 billion in 2025 to USD 43.23 billion by 2035, driven by the essential role of diagnostic testing in clinical decisions and rising test volumes due to ageing populations, chronic diseases, cancer screening, and innovations in molecular testing. Laboratory automation and diagnostics, including point-of-care testing, are projected to grow steadily, reaching USD 32.61 billion by 2030, with a CAGR of 5.8% from 2026 to 2035. The growth is supported by healthcare investments and steady reagent demand, although it faces some reimbursement pressures.
Analyst View: We built the estimate from European consumption of in-vitro diagnostic tests and related reagents, instruments, software and services by technology, application, end user and country, using laboratory statistics, procurement data and average prices. Consumption reflects testing volumes driven by population, disease prevalence, screening programmes and clinical guidelines. Published estimates vary widely in scope, so the total was set on an evidence basis between industry association data and broader market estimates, cross-checking against leading diagnostics companies' European revenues. The growth rate reflects steady diagnostic demand and molecular testing expansion, moderated by price pressure in public tenders and IVDR compliance costs.
Market Trends
- IVDR regulations are reshaping European and Italian diagnostics, forcing companies to streamline portfolios and discontinue low-margin, complex legacy products.
- Laboratory automation improves Italian IVD workflows, reducing manual intervention, increasing productivity, and enhancing operational efficiency through advanced integrated systems.
- Syndromic molecular panels enable rapid pathogen detection, supporting targeted antimicrobial treatment, reducing isolation costs, and improving outbreak management.
- Companion diagnostics advance personalized cancer treatment, encouraging Italian laboratories to prioritize high-value molecular and genetic testing over routine assays.
- Point-of-care testing (POCT) and patient self-testing (PST) support decentralized diagnosis and monitoring, bringing selected tests closer to patients.
- Digital pathology can support workflow efficiency, remote consultation and image-based analysis, subject to validation and clinical implementation, laboratory efficiency, and remote collaboration through high-resolution digital imaging of traditional glass slides.
Europe & Italy IVD Market Drivers, Restraints, and Opportunities
Driver
The IVD market in Europe and Italy is driven by ageing populations and the increasing prevalence of chronic diseases, cancer, and other long-term health conditions, which are contributing to growing demand for diagnostic testing and early disease detection. The rising adoption of molecular diagnostics is further supporting market growth in areas such as infectious disease detection, oncology, and genetic testing. Additionally, increasing laboratory automation is improving testing efficiency, workflow productivity, and diagnostic accuracy. National healthcare investment plans and government initiatives across European countries, including Italy, are supporting the modernization of diagnostic infrastructure, laboratory equipment, and healthcare systems, thereby creating favourable conditions for the adoption of advanced IVD technologies.
Restraint
The IVD market in Europe and Italy encounters pricing pressures from competitive public procurement and government tendering, affecting diagnostic manufacturers' profit margins. Compliance with the EU IVDR heightens regulatory costs due to requirements for clinical evidence, performance validation, and certification. Variations in reimbursement and funding across countries lead to differing market access and adoption. Additionally, a shortage of skilled laboratory professionals limits operational capacity, while decreased post-pandemic COVID-19 testing volumes negatively impact demand for certain diagnostic products.
Opportunity
The rise of precision medicine and personalized healthcare offers significant growth prospects for the IVD market in Europe, particularly in Italy, through precision oncology diagnostics and advanced molecular testing. Concerns over antimicrobial resistance are increasing the demand for rapid diagnostics. Furthermore, the growth of decentralized testing enhances accessibility in primary care and remote areas. The incorporation of digital technologies and AI into diagnostics improves accuracy and efficiency. Additionally, Central and Eastern Europe presents growth potential, bolstered by healthcare investments and modernization of laboratory technologies.
Europe & Italy IVD Market Segmentation: 2025 Share and Size
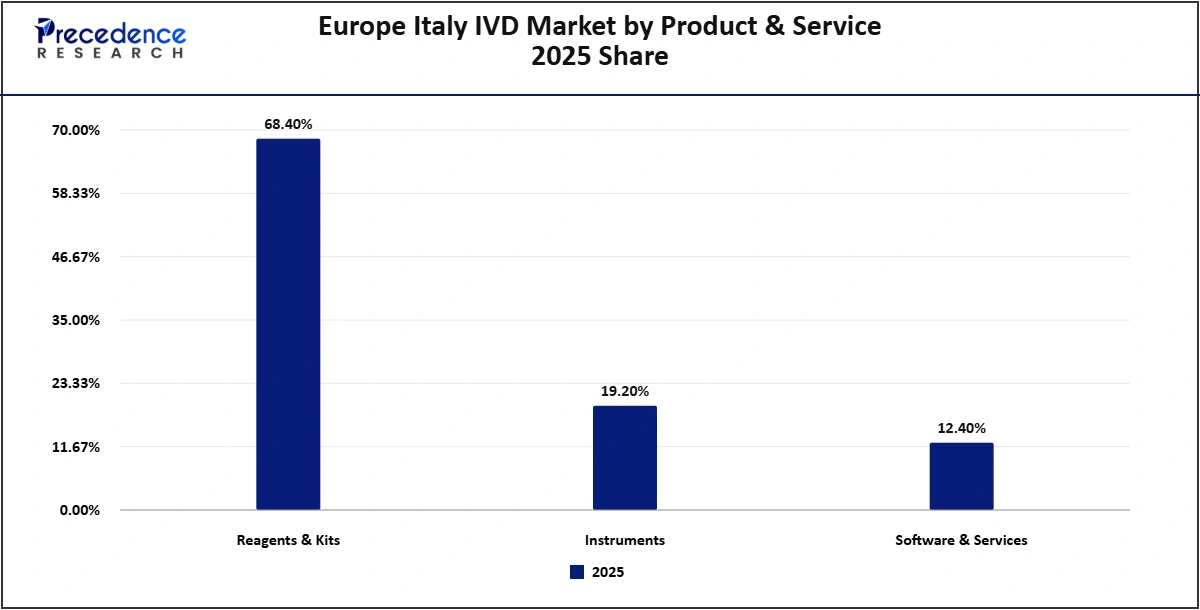
Europe Italy IVD Market by Product & Service 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
In 2025, reagents and kits led the market, accounting for 68.4%, valued at USD 16.83 billion. Instruments followed with 19.2%, worth USD 4.72 billion, while software and services captured 12.4% of the market, equivalent to USD 3.05 billion.
Reagents and Kits segment, valued at USD 16.83 billion in 2025, constitutes 68.4% of the market, focusing on reagents and kits such as assay reagents, calibrators, controls, and test kits for diagnostic technologies. Their dominance stems from being consumables for each test, typically supplied under long-term contracts.
In 2025, the Instruments segment constituted 19.2% of the market, valued at USD 4.72 billion. This category includes analysers, automation lines, molecular platforms, and point-of-care devices, typically utilized in laboratories via reagent rental or leasing arrangements.
Software and Services captured 12.4% of the market, valued at USD 3.05 billion in 2025, and is expected to grow to USD 6.21 billion by 2035, with a CAGR of 7.37% from 2026 to 2035. This segment includes middleware, laboratory information systems, digital pathology, remote monitoring, and maintenance, making it the fastest-growing due to laboratory consolidation and digitization.
Europe Italy IVD Market By Technology 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Immunoassays | 30.60% | 7.53 | 12.46 | 5.16% |
| Clinical Chemistry | 18.40% | 4.53 | 7.77 | 5.56% |
| Molecular Diagnostics | 16.80% | 4.13 | 8.56 | 7.56% |
| Point-of-Care & Self-Testing | 12.60% | 3.10 | 5.32 | 5.56% |
| Hematology & Coagulation | 11.20% | 2.76 | 4.73 | 5.56% |
| Microbiology & Others | 10.40% | 2.56 | 4.39 | 5.56% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
In 2025, immunoassays led the market, with a 30.6% share, valued at USD 7.53 billion. Clinical chemistry followed with 18.4% of the market, equivalent to USD 4.53 billion, while molecular diagnostics accounted for 16.8%, worth USD 4.13 billion. Point-of-care and self-testing captured 12.6% of the market, valued at USD 3.10 billion. Haematology and coagulation accounted for a further 11.2% of the market, equating to USD 2.76 billion. Microbiology and others accounted for 10.4% of the market, valued at USD 2.56 billion.
Immunoassays: This segment accounted for 30.6% of the market in 2025, valued at USD 7.53 billion. Immunoassays, including chemiluminescence and ELISA, are the largest technology, used for hormones, cardiac markers, tumour markers, infectious disease serology, and vitamin D. Roche, Abbott, Siemens Healthineers, and DiaSorin are major suppliers.
Clinical Chemistry: This segment held 18.4% of the market, worth USD 4.53 billion in 2025. Clinical chemistry covers routine tests such as glucose, lipids, liver and kidney function, run on high-throughput automated analysers.
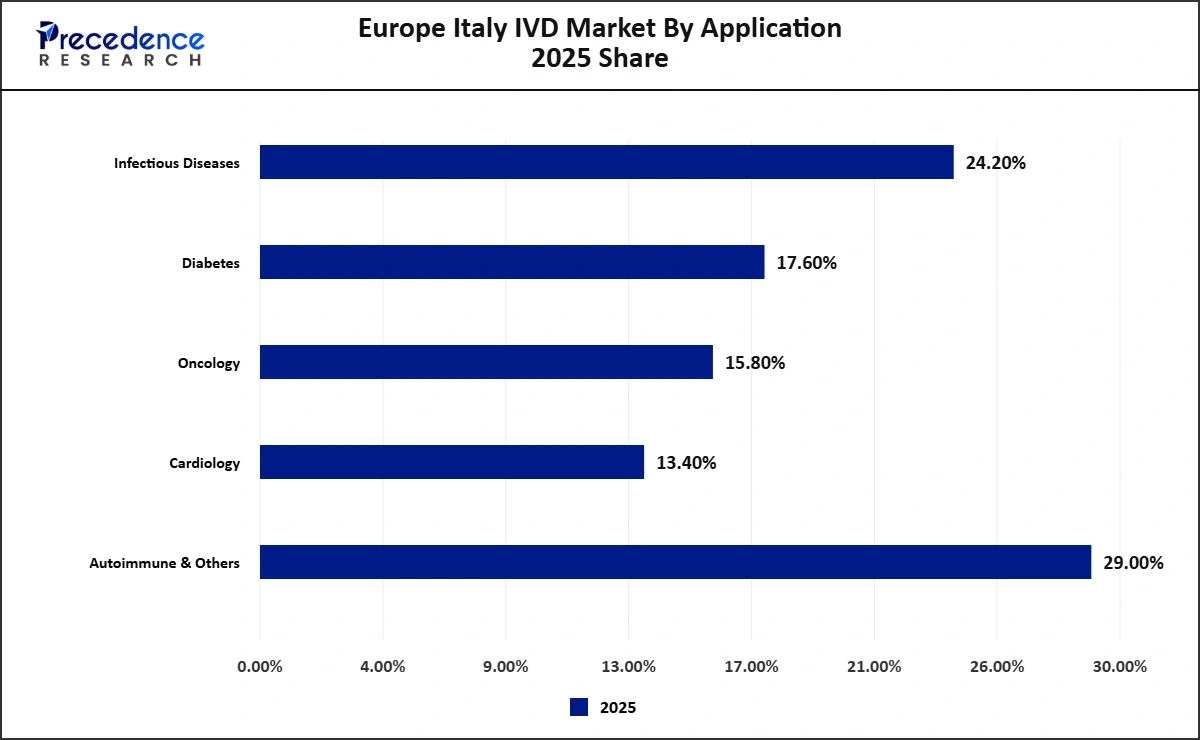
Europe Italy IVD Market By Application 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Based on application, infectious diseases accounted for the largest market share in 2025, representing 24.2% of the market and valued at USD 5.95 billion. Diabetes was the second-largest segment, capturing 17.6% of the market, with a valuation of USD 4.33 billion. Oncology accounted for 15.8%, valued at USD 3.89 billion, followed by cardiology, which held a 13.4% share, worth USD 3.30 billion. Meanwhile, autoimmune and other applications collectively represented the remaining 29% of the market, with a combined valuation of USD 7.13 billion.
Infectious diseases represented 24.2%, worth USD 5.95 billion, of the Europe and Italy IVD market in 2025, encompassing respiratory, sexually transmitted, hepatitis, HIV, and hospital-acquired infections, bolstered by antimicrobial stewardship programmes.
In 2025, diabetes testing, including HbA1c, glucose, and self-monitoring, held 17.6% of the market, valued at USD 4.33 billion, influenced by the increasing prevalence of diabetes.
Europe Italy IVD Market By End User 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Hospitals | 48.60% | 11.96 | 20.14 | 5.35% |
| Independent Laboratories | 36.40% | 8.95 | 15.66 | 5.75% |
| Home Care & Others | 15.00% | 3.69 | 7.43 | 7.25% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
In 2025, hospitals accounted for 48.6% of the Europe and Italy IVD market, valued at USD 11.96 billion. Independent laboratories followed, accounting for 36.4% of the market, equivalent to USD 8.95 billion, while home care and others held a 15% market share, valued at USD 3.69 billion.
In 2025, hospitals dominated the market, accounting for 48.6% of the market, worth USD 11.96 billion. They represent the largest end-user segment, driven by the significant volume of diagnostic testing conducted through public hospital laboratories across Italy, Spain, and other European countries. The segment is projected to reach USD 20.14 billion by 2035, expanding at a CAGR of 5.35% from 2026 to 2035.
Independent laboratories accounted for 36.4% of the market in 2025, valued at USD 8.95 billion. Demand from this segment is supported by the growing volume of outpatient diagnostic testing and the expansion of large laboratory networks, including Synlab, Unilabs, Cerba, and Eurofins, particularly across Germany and France. The segment is projected to reach USD 15.66 billion by 2035, growing at a CAGR of 5.75% from 2026 to 2035.
Home care and others accounted for 15% of the market in 2025, equivalent to USD 3.69 billion. This segment includes self-testing, pharmacies, and physician offices, with growth supported by the increasing shift toward decentralized diagnostics and patient-centric testing solutions. As diagnostic services move closer to patients, this segment is expected to witness the fastest growth, reaching USD 7.43 billion by 2035 at a CAGR of 7.25% from 2026 to 2035.
Analyst View: We estimated that reagents lead the market due to their recurring demand across diagnostic procedures, while immunoassays dominate among technologies, supported by their widespread clinical applications. Infectious disease testing represents a leading application segment, driven by sustained diagnostic requirements across healthcare settings. Hospitals lead among end users because of the high volume of testing conducted through public healthcare laboratories. We expect software and services, molecular diagnostics, oncology testing, and home-based testing to gain market share as diagnostic technologies advance and testing increasingly shifts toward decentralized care.
Country Analysis of Europe & Italy IVD Market
Europe Italy IVD Market By Country 2025 Share & Size
| Country | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Germany | 23.40% | 5.76 | 10.13 | 5.81% |
| France | 15.20% | 3.74 | 6.58 | 5.81% |
| Italy | 12.10% | 2.98 | 5.65 | 6.61% |
| U.K. | 11.60% | 2.85 | 5.02 | 5.81% |
| Spain | 8.60% | 2.12 | 3.72 | 5.81% |
| Rest of Europe | 29.10% | 7.16 | 12.13 | 5.41% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
In 2025, Germany dominated the European in vitro diagnostics (IVD) market, accounting for 23.40% of the market share, valued at USD 5.76 billion. France followed with a 15.20% share, equivalent to USD 3.74 billion. Italy accounted for 12.10% of the market, valued at USD 2.98 billion, while the U.K. represented 11.60%, worth USD 2.85 billion. Spain held an 8.60% share, valued at USD 2.12 billion. Meanwhile, the rest of Europe accounted for the largest collective share of 29.10%, valued at USD 7.16 billion. Among the major European countries, Italy is projected to be the fastest-growing market through 2035.
Germany: This country accounted for 23.40% of the European IVD market in 2025, valued at USD 5.76 billion, and is projected to reach USD 10.13 billion by 2035, growing at a CAGR of 5.81% from 2026 to 2035. Germany represents Europe's largest IVD market, supported by an extensive hospital and laboratory network, statutory health insurance reimbursement, strong research funding, and the presence of major diagnostic manufacturers and reference laboratories.
France: Accounted for 15.20% of the European IVD market in 2025, valued at USD 3.74 billion. The market is projected to reach USD 6.58 billion by 2035, registering a CAGR of 5.81%. France's well-reimbursed laboratory sector, consolidated private laboratory groups, and strong public research infrastructure sustain demand for IVD products and services.
Italy: This country accounted for 12.10% of the European IVD market in 2025, valued at USD 2.98 billion, and is projected to reach USD 5.65 billion by 2035, registering a CAGR of 6.61%. Italy is the fastest-growing major country in the regional market, supported by its extensive regional healthcare network, numerous hospital and private laboratories, ageing population, and high chronic disease burden. The presence of leading domestic diagnostics companies such as DiaSorin, alongside investments in laboratory modernisation, precision medicine, healthcare digitalisation, and medical equipment under the National Recovery and Resilience Plan, further accelerates market growth.
U.K.: The UK represented 11.60% of the European IVD market in 2025, valued at USD 2.85 billion. The market is projected to reach USD 5.02 billion by 2035, registering a CAGR of 5.81%. The country's established genomics and research programmes, extensive NHS pathology network, and strong life sciences sector drive sustained demand for IVD technologies.
Spain: Spain held an 8.60% share of the European IVD market in 2025, valued at USD 2.12 billion. The market is projected to reach USD 3.72 billion by 2035, registering a CAGR of 5.81%. Spain's expanding laboratory sector, regional healthcare investments in advanced diagnostic equipment, and growing precision medicine programmes support market growth.
Rest of Europe: This region accounted for 29.10% of the European IVD market in 2025, valued at USD 7.16 billion, and is projected to reach USD 12.13 billion by 2035, expanding at a CAGR of 5.41%. The region includes the Netherlands, Switzerland, Nordic countries, Belgium, Austria, Poland, and other European markets. High healthcare and diagnostic spending across Western Europe, combined with faster market development in Central and Eastern European countries, supports regional growth.
Analyst View: Based on our analysis, Germany leads the European IVD market due to its extensive laboratory infrastructure, well-established healthcare reimbursement system, strong research ecosystem, and presence of major diagnostic manufacturers. In contrast, Italy represents the fastest-growing major national market, driven by laboratory modernisation, increasing investments in precision medicine, and healthcare infrastructure development supported by National Recovery and Resilience Plan funding.
Competitive Landscape
Top 10 Companies in the Europe & Italy IVD Market, 2025
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | Roche Diagnostics | 5.20 | 21.14% | cobas immunoassay, chemistry and molecular systems | Switzerland |
| 2 | Abbott | 2.40 | 9.76% | Alinity diagnostics and FreeStyle Libre | United States |
| 3 | Danaher (Beckman Coulter, Cepheid, Radiometer, Leica) | 2.40 | 9.76% | Diagnostics platforms | United States |
| 4 | Siemens Healthineers | 2.00 | 8.13% | Atellica laboratory diagnostics | Germany |
| 5 | bioMérieux | 1.20 | 4.88% | Microbiology and BioFire molecular | France |
| 6 | Thermo Fisher Scientific | 1.00 | 4.07% | Specialty diagnostics | United States |
| 7 | Werfen | 0.90 | 3.66% | Haemostasis, critical care and autoimmunity | Spain |
| 8 | Sysmex | 0.80 | 3.25% | Haematology and urinalysis | Japan |
| 9 | BD | 0.60 | 2.44% | Microbiology and molecular diagnostics | United States |
| 10 | DiaSorin | 0.45 | 1.83% | LIAISON immunoassay and molecular | Italy |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
The top 10 companies accounted for an estimated 68.9% of the European IVD market in 2025, with the remaining share distributed among regional diagnostics manufacturers, specialist molecular testing providers, point-of-care companies and other suppliers. Roche Diagnostics led the competitive landscape with an estimated market-specific revenue of USD 5.20 billion, equivalent to 21.14% of the market, followed by Abbott and Danaher, each with an estimated share of 9.76%. Competition is shaped by diagnostic menu breadth, analytical performance, laboratory automation, installed instrument base, reagent availability, IVDR compliance, tender pricing and technical service capabilities. In Italy, supplier competitiveness is also influenced by regional procurement arrangements, laboratory consolidation and the ability to provide integrated diagnostic solutions.
Companies Ecosystem
The Europe & Italy IVD ecosystem links raw material and component suppliers with diagnostics manufacturers, notified bodies, distributors, laboratories, payers, and patients.
| Ecosystem Stage | Role in the Market | Key Companies |
| Raw Materials | Supply antibodies, enzymes and components | Biological and component suppliers |
| Manufacturers | Develop and produce IVD systems | Roche, Abbott, Siemens Healthineers, bioMérieux, DiaSorin |
| Regulators | Certify devices under IVDR | Notified bodies, national competent authorities, EU Commission |
| Laboratories | Perform tests | Hospital labs, Synlab, Unilabs, Cerba, Eurofins |
| Payers & Procurement | Fund and buy tests | National and regional health services, insurers, tender bodies |
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Precedence Research Companies Quadrant
The Precedence Research Companies Quadrant positions key participants in the Europe & Italy IVD market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 European IVD revenue and our assessment of its menus, platforms and innovation.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Leaders: Roche Diagnostics, Abbott, Danaher (Beckman Coulter, Cepheid, Radiometer, Leica), Siemens Healthineers, bioMérieux, Thermo Fisher Scientific and Werfen combine large European IVD revenue with broad menus, automation and molecular innovation.
Innovators: DiaSorin brings specialized immunoassay and molecular diagnostic capabilities.
Niche Players: Sysmex and BD serve narrower technology segments.
Recent Developments
- June 2026: Industry guidance highlighted the staged IVDR transition deadlines under Regulation (EU) 2024/1860, with legacy Class D devices allowed on the market until 31 December 2027, Class C until 2028 and Class B and sterile Class A devices until 2029, subject to applicable transitional conditions.
- September 2025: QIAGEN received CE-IVDR certification for its full portfolio of QIAstat-Dx syndromic testing systems and respiratory, gastrointestinal, and CNS panels.
Europe Italy IVD Market Segments
By Product & Service
- Reagents & Kits
- Instruments
- Software & Services
By Technology
- Immunoassays
- Clinical Chemistry
- Molecular Diagnostics
- Point-of-Care & Self-Testing
- Hematology & Coagulation
- Microbiology & Others
By Application
- Infectious Diseases
- Diabetes
- Oncology
- Cardiology
- Autoimmune & Others
By End User
- Hospitals
- Independent Laboratories
- Home Care & Others
By Country
- Germany
- France
- Italy
- U.K.
- Spain
- Rest of Europe
Research Methodology
The Europe IVD market is defined as the sales of in vitro diagnostic reagents, kits, instruments, software and associated support services across immunoassay, clinical chemistry, molecular diagnostics, point-of-care testing, haematology, coagulation and microbiology. The 2025 base-year estimate was developed using a bottom-up assessment of diagnostic testing volumes, product consumption, average selling prices and instrument sales across major European countries, with a dedicated assessment of Italy.
Market estimates were segmented by product, technology, application, end user and country. Recurring revenues from reagents, assay kits, controls and calibrators were assessed separately from instrument sales and software-related revenues to avoid double counting. The estimates were cross-checked against relevant European business revenues of major diagnostics manufacturers, industry data and healthcare expenditure indicators. Company-level market shares reflect estimated revenue attributable to the defined European IVD product scope rather than total corporate revenue.
The 2026-2035 forecast incorporates anticipated changes in diagnostic testing volumes, population ageing, disease prevalence, screening programmes, molecular diagnostics adoption, laboratory automation, reimbursement and IVDR compliance. Italy's outlook additionally considers laboratory modernization, healthcare infrastructure investment and regional procurement dynamics.
Analyst View
The Europe and Italy IVD market is a large, mature and reagent-driven market, with growth now led by molecular, oncology and digital solutions. Our estimate links demand to test volumes and spending by country, so the forecast follows demographics, screening policies, technology adoption, and reimbursement. The main upside comes from molecular diagnostics and Italian modernisation, while the main risks are tender pricing and IVDR costs.
Sources and References
- SGS. "Extension of IVDR transition period". June 2026. Regulatory update. https://www.sgs.com/en-dk/news/2026/06/extension-of-ivdr-transition-period
- QIAGEN. "QIAGEN receives CE-IVDR certification for full QIAstat-Dx syndromic testing portfolio". September 2025. Press release. https://www.businesswire.com/news/home/20250910286236/en
- MedTech Europe. "The European Medical Technology Industry in Figures". 2025. Industry data. https://www.medtecheurope.org/?p=4574
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
