
Genotyping Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Competitive Positioning, and Demand Forecast
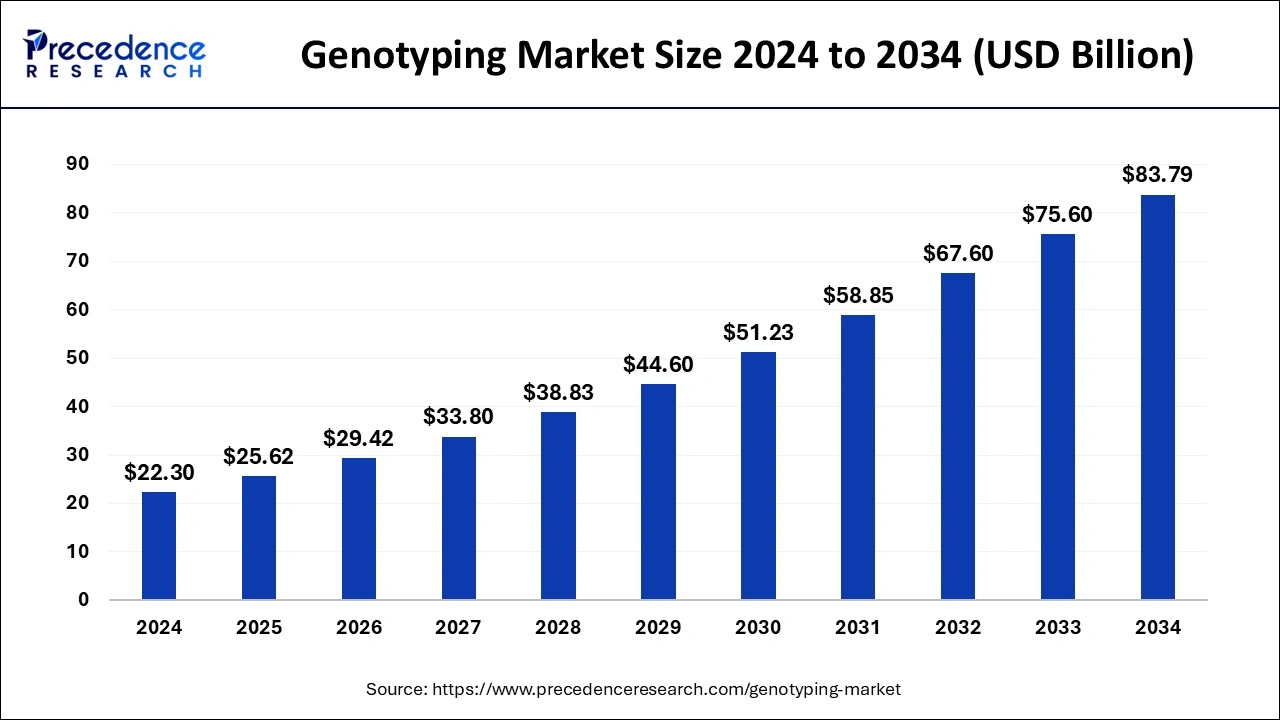
The global genotyping market is valued at approximately USD 29.42 billion in 2026 and is projected to reach USD 91.85 billion by 2035, growing at a CAGR of 13.62% during the 2026-2035 forecast period. Growth is driven by falling cost per genotype, population-scale studies, pharmacogenomics, precision medicine, agricultural genomics and sequencing-enabled workflows. The report analyzes the market by technology, product, application, end user and region, covering PCR, microarrays and NGS, pricing economics, competitive structure, company benchmarking and strategic scenarios through 2036, helping stakeholders identify high-value clinical, research and agricultural opportunities as genotyping increasingly shifts toward actionable genomic information and decision-making.
Source: https://www.precedenceresearch.com/genotyping-market
 Get a Sample
 Table Of Content


What is the Genotyping Market Size?
The global genotyping market size is predicted to increase from USD 29.42 billion in 2026 to approximately USD 91.85 billion by 2035, expanding at a CAGR of 13.62% from 2026 to 2035. The genotyping market has grown because genotyping at birth can verify paternity and correct errors. Acknowledging parental errors before registration can prevent future problems and screenings.
Overview - Genotyping is Moving from Standalone SNP Detection Toward Scalable, Application-Specific Genomic Decision-Making
The market is being reshaped by the convergence of SNP genotyping, microarrays, PCR-based assays, targeted sequencing, next-generation sequencing (NGS), pharmacogenomics, population-scale studies, agricultural genomics, and precision medicine. Microarrays remain economically important for high-volume studies because they can interrogate hundreds of thousands to millions of markers at low per-sample cost, while PCR-based genotyping remains relevant for targeted variants where rapid turnaround and low workflow complexity matter. NGS is expanding the addressable market where broader variant discovery, rare-variant detection, or multiplexed genomic characterization is required.
North America remains a major revenue center because of high research expenditure, clinical genomics adoption, biopharma activity, and established genomic infrastructure, while Asia Pacific represents a major expansion opportunity as sequencing capacity, agricultural biotechnology, population-genomics programs, and molecular-testing infrastructure scale.
Key Coverage
- Global market size, historical growth, 2030/2035 forecast, and CAGR
- Genotyping assays, kits, arrays, instruments, reagents, software, and services
- PCR, microarray, NGS, SNP, STR, and targeted genotyping technologies
- Human, clinical, pharmaceutical, agricultural, animal, and research applications
- Regional demand, pricing, sample economics, and laboratory capacity
- Competitive market share and company-level revenue exposure
- Emerging opportunities in pharmacogenomics, precision medicine, agrigenomics, and population genomics
Market Size & Forecast - High-Throughput Genotyping and Precision Applications Expand the Revenue Pool
Growth is not expected to be uniform across technologies. High-throughput array workflows benefit from falling per-sample economics and population-scale studies, while targeted PCR-based workflows retain an advantage where laboratories require rapid and highly specific variant calls. Sequencing-enabled genotyping is capturing additional value where customers require greater variant breadth rather than fixed-marker interrogation.
The full analysis quantifies the market by technology, product, sample type, application, end user, workflow, geography, and business model, including base, upside, and downside scenarios reflecting changes in sequencing economics, clinical adoption, reimbursement, research funding, and agricultural-genomics investment.
Key Coverage
- Incremental revenue opportunity
- Regional growth contribution
- Technology-specific CAGR
- Revenue split between products and services
Segmentation Analysis - Microarrays Retain Scale Economics While Targeted PCR and Sequencing Capture Specialized Demand
The market is segmented across technology, product, application, end user, sample type, and geography.
By technology, microarray-based genotyping remains structurally important for large cohorts because of its ability to process high sample volumes while interrogating hundreds of thousands of predefined variants. Modern array platforms can achieve call rates above 99% in established workflows, while some high-density arrays contain more than 1.9 million markers, demonstrating the scale at which array-based genotyping continues to compete.
PCR-based genotyping, particularly allele-specific and probe-based assays, remains important for targeted SNP analysis. Some streamlined workflows can generate genotyping results in less than one hour, making targeted PCR particularly relevant for applications where speed and assay simplicity outweigh genome-wide coverage.
NGS-based genotyping represents the fastest-expanding technology pool because it increases multiplexing, enables broader variant discovery, and can integrate genotyping with sequencing-based molecular characterization.
By application, the market spans pharmacogenomics, precision medicine, population genetics, disease research, agricultural genomics, animal genetics, ancestry and consumer genomics, and biopharmaceutical research.
Key Coverage
- Technology share and growth by PCR, arrays, NGS, and related methods
- SNP versus broader variant analysis
- Research versus clinical applications
- Human versus agricultural and animal genotyping
- High-throughput versus targeted workflows
- Custom versus catalog assays
- Fastest-growing application and technology segments
Which Structural Forces are Expanding Genotyping Volumes, and Where Could Workflow Complexity Constrain Growth?
The declining cost per genotype is enabling laboratories to process larger cohorts without proportional increases in personnel, laboratory infrastructure, or operating budgets. Automation, multiplexing, improved assay chemistry, standardized arrays, and lower sequencing costs are collectively improving the economics of high-throughput genotyping. Our analysis indicates that this cost-driven productivity improvement is likely to expand sample volumes and genotype throughput faster than traditional laboratory budgets, making workflow efficiency an increasingly important competitive and purchasing criterion.
Precision medicine and pharmacogenomics add a structural demand layer because genetic information is increasingly used to support drug selection, dosing, treatment-response assessment, and clinical-trial stratification. Agricultural genomics provides a parallel growth engine, with breeding programs using genotyping to accelerate trait selection, disease-resistance screening, yield improvement, and population characterization. In our view, the significance of these applications is that genotyping demand is shifting beyond basic research toward workflows where faster and larger-scale genetic characterization can directly influence clinical, pharmaceutical, or breeding decisions.
The principal constraint remains workflow complexity. Sample quality, assay design, variant selection, bioinformatics, laboratory execution, and interpretation can limit the value of higher-throughput platforms if downstream processes cannot scale at the same rate. Our assessment is that fixed-marker platforms may also face pressure when research requirements shift toward rare, novel, or previously uncharacterized variants, where broader sequencing-based approaches can provide greater flexibility. The strategic implication is that future market growth will depend not only on lowering the cost of genotype generation but also on improving end-to-end workflow scalability and matching platform design to increasingly diverse research questions.
The full report further quantifies the impact of cost per sample, throughput, assay configuration, technology adoption, application mix, and workflow requirements across major genotyping technologies and end-use segments. The analysis also evaluates how precision medicine, pharmacogenomics, agricultural genomics, automation, and sequencing integration are reshaping demand, while assessing the technology and workflow constraints that could influence adoption and market growth through the forecast period.
How are Genotyping Economics Shifting from Assay Price Toward Throughput, Content Density, and Data Value?
Genotyping economics vary materially across targeted PCR, array-based platforms, sequencing, and outsourced service models, with the optimal economics determined largely by cohort size, variant breadth, and workflow requirements. Targeted assays can remain cost-efficient when only a limited number of variants are required, while arrays become increasingly attractive as sample volumes increase because the cost of interrogating hundreds of thousands of markers can be distributed across large cohorts. Sequencing generally involves higher data-generation and computational requirements, but its ability to detect a broader range of variant types increases its value when predefined marker content is insufficient.
Our analysis indicates that cost per sample alone is no longer an adequate measure of genotyping competitiveness. The more meaningful economic variables include cost per marker, assay pricing, instrument utilization, reagent consumption, labor requirements, service margins, data-analysis costs, and turnaround time. Custom-content requirements can further alter the economics by increasing development and production costs relative to standardized catalog assays. In our view, this creates a shift from simple assay-price comparisons toward evaluation of cost per usable dataset and throughput-adjusted workflow efficiency.
The strategic implication is that suppliers increasingly compete on total workflow economics rather than reagent price alone. High instrument utilization, automation, multiplexing, scalable data analysis, and efficient interpretation can materially improve the economics of large-volume projects, while specialized or customized assays can command value where predefined content does not adequately address the research requirement. Our assessment is that suppliers able to combine high throughput with flexible content and efficient downstream analysis will be better positioned as customer requirements become more complex.
The full report benchmarks pricing structures, cost per sample and marker, throughput, utilization, reagent and labor requirements, data-analysis costs, turnaround times, service economics, and custom-versus-catalog content premiums across major genotyping approaches. Where sufficiently granular information is available, the same intelligence can be structured into a dataset tracking technology, assay type, marker density, sample volume, pricing, workflow model, turnaround time, utilization, application, and geography, enabling users to filter and benchmark genotyping economics across technologies and use cases alongside the strategic findings of the report.
How is the Competitive Landscape Shaping the Genotyping Market?
The genotyping market includes global platform suppliers, assay and PCR specialists, agricultural and animal-genetics providers, and outsourced genomic service companies, each competing through different capabilities. The table below summarizes the leading participants by headquarters, market position, and core strength.
| Company | Headquarters | Market Position | Core Strength |
| Illumina | U.S. | Global platform leader | Arrays, sequencing, population-scale genotyping |
| Thermo Fisher Scientific | U.S. | Global platform leader | Arrays, PCR assays, instruments, reagents |
| Roche | Switzerland | Global diversified | PCR, sequencing and clinical genomics |
| Bio-Rad Laboratories | U.S. | PCR specialist | Digital PCR and qPCR platforms |
| QIAGEN | Netherlands | Global sample-to-insight | Sample preparation, PCR, bioinformatics |
| Revvity | U.S. | Diversified life sciences | Genomic screening, PCR, automation |
| Standard BioTools | U.S. | Targeted specialist | Microfluidics-based SNP genotyping |
| Agena Bioscience | U.S. | Mass-spectrometry specialist | MassARRAY targeted genotyping |
| LGC Biosearch Technologies | U.K. | Assay specialist | Allele-specific assays, agrigenomics |
| Takara Bio | Japan | Reagent specialist | PCR reagents and genomic tools |
| Neogen | U.S. | Agri and animal specialist | Plant and animal genomic testing |
| Eurofins Genomics | Luxembourg | Global service provider | Outsourced genotyping and sequencing |
| Azenta Life Sciences | U.S. | Service provider | Genomic services and sample management |
| BGI Genomics / MGI Tech | China | Asian platform challenger | Sequencing platforms and genomic services |
| Macrogen | South Korea | Asian service provider | Genomic and genotyping services |
Which Genotyping Technologies are Best Positioned as the Market Shifts Toward Higher Density, Throughput, and Workflow Automation?
Genotyping technology is increasingly being shaped by the trade-off between marker density, sample throughput, turnaround time, cost, and breadth of variant detection. Microarrays remain highly competitive for predefined variants and population-scale studies, with scaled environments capable of processing hundreds of thousands of samples per week and platforms incorporating hundreds of thousands to millions of markers. Targeted PCR remains relevant where rapid, low-complexity testing is required, while NGS is expanding into applications where broader genomic characterization provides greater value.
Our analysis indicates that the market is not converging on a single technology. Instead, adoption is becoming increasingly application specific. Arrays offer scale and cost efficiency for predefined marker sets; targeted assays offer speed and simplicity for focused testing, and sequencing provides greater variant breadth when research questions extend beyond established markers. In our view, the most commercially significant technologies will be those that optimize this trade-off for specific workflows rather than simply maximizing technical capability.
Automation is becoming an increasingly important differentiator as throughput requirements rise. Robotic liquid handling, automated array loading, laboratory information management systems, cloud-based analysis, and automated genotype calling can reduce manual intervention, improve reproducibility, and support larger-scale workflows. Our assessment is that automation will increasingly influence technology selection because its value extends beyond labor reduction to include higher instrument utilization, fewer processing errors, and more consistent data generation.
The full report evaluates marker density, throughput, turnaround time, cost, variant breadth, automation, workflow integration, and analytical capabilities across major genotyping technologies. Where sufficiently granular information is available, the same intelligence can be structured into a dataset tracking technology, platform, marker density, sample throughput, automation level, application, workflow stage, and geographic deployment, enabling technology benchmarking and identification of adoption gaps and innovation opportunities.
How are Clinical Evidence, Data Governance, and Sustainability Requirements Reshaping Genotyping Adoption?
Clinical genotyping faces substantially higher evidentiary and regulatory requirements than research-use workflows, particularly around analytical validity, clinical validity, laboratory quality, patient consent, genomic-data privacy, data storage, and interpretation. Our analysis indicates that technical assay performance alone is becoming insufficient to determine clinical adoption. As genotyping moves closer to treatment selection and other healthcare decisions, the ability to demonstrate reliable results, maintain appropriate data governance, and translate genetic findings into clinically meaningful information becomes increasingly important.
Pharmacogenomics illustrates this shift particularly clearly because adoption depends on the strength of evidence linking specific genetic variants to drug response. Our assessment is that the commercial value of pharmacogenomic genotyping will increasingly depend on the quality and clinical relevance of the evidence supporting variant interpretation, rather than on the ability to generate genotype data alone. Agricultural applications operate under a different regulatory framework, with considerations spanning breeding technologies, genetically modified organisms, seed commercialization, and traceability, creating distinct market-access requirements across use cases.
Sustainability is emerging as an additional operational consideration through reagent consumption, laboratory plastics, instrument energy use, automation efficiency, and waste generated per sample. In our view, the most relevant sustainability gains are likely to come from higher-throughput workflows that reduce resource consumption per genotype while improving laboratory utilization. This could strengthen the business case for automation and workflow optimization where environmental efficiency also translates into lower operating costs.
The full report evaluates the regulatory and clinical factors affecting adoption, including evidence requirements, laboratory quality, genomic data governance, consent, interpretation, pharmacogenomic utility, and agricultural regulatory considerations. It also assesses sustainability through resource consumption, automation, energy use, plastics, and waste per sample. Where sufficient granular information is available, these parameters can be structured into a dataset tracking application, regulatory status, evidence requirements, data-governance parameters, workflow characteristics, resource consumption, and sustainability indicators, enabling cross-market benchmarking alongside the strategic analysis.
Which Customer Segments are Driving Genotyping Demand, and How Do Their Purchasing Priorities Differ?
Genotyping demand is increasingly fragmented across academic and research institutions, biopharmaceutical companies, clinical laboratories, agricultural breeding programs, and animal-genetics customers, with each segment applying different criteria to technology selection. Academic and research institutions generally prioritize marker density, flexibility, reproducibility, and cohort scale, while biopharmaceutical customers place greater value on biomarkers discovery, patient stratification, clinical-trial enrichment, and pharmacogenomic analysis. Our analysis indicates that these differences are creating distinct demand pools rather than a single homogeneous genotyping market.
Clinical laboratories operate under a different economic and operational model, with validation, turnaround time, regulatory compliance, and interpretability carrying greater weight than maximum marker density alone. Our assessment is that clinical demand will increasingly favor workflows that combine reliable analytical performance with efficient interpretation and regulatory readiness. This creates a higher barrier to adoption than in research-use applications, where flexibility and experimental breadth can be more important purchasing considerations.
Agricultural and animal-genetics applications represent distinct volume-oriented opportunities. Agricultural customers prioritize trait-linked markers, breeding-cycle acceleration, population diversity, and cost per sample, while animal-genetics customers emphasize parentage, breeding value, disease resistance, and herd-level throughput. In our view, the commercial opportunity across these segments depends on matching technology economics to the specific decision being supported: clinical interpretation, drug-development efficiency, breeding-cycle improvement, or population-level genetic characterization.
The full report segments demand by customer type, application, workflow requirements, purchasing priorities, sample volumes, technology preferences, and economic drivers, while comparing the role of genotyping across research, biopharma, clinical, agricultural, and animal-genetics workflows. Where sufficient granular information is available, the same intelligence can be structured into a dataset tracking customer segment, application, technology, marker requirements, sample volume, turnaround expectations, purchasing criteria, geography, and workflow economics, enabling cross-segment benchmarking and identification of high-value demand pockets.
Which Capabilities are Creating Sustainable Competitive Advantage in the Genotyping Market?
The genotyping market remains structurally fragmented across assay chemistry, microarrays, sequencing, instruments, reagents, bioinformatics, and outsourced genomic services, bringing diversified life-science companies into competition with specialized genomics and application-focused providers. Our analysis indicates that competitive strength increasingly depends on the ability to combine multiple capabilities rather than leadership in a single product category. Installed instrument base, proprietary assay content, manufacturing scale, sample-processing capacity, software ecosystems, genomic databases, and distribution reach can reinforce one another by increasing customer retention and lowering the friction of adopting adjacent products and services.
The strongest competitive advantages are therefore increasingly linked to ecosystem depth and customer integration. Providers with broad installed bases can benefit from recurring consumable and service demand, while proprietary assay content and genomic databases can strengthen differentiation where customers require validated, application-specific information. Our assessment is that relationships with pharmaceutical, academic, clinical, agricultural, and animal-genetics customers further reinforce competitive positioning because workflow qualification, data continuity, and application expertise can increase switching costs.
The market also exhibits a two-speed competitive structure. Large-scale platforms compete primarily around throughput, standardized workflows, population-scale processing, and research infrastructure, while specialized providers can differentiate through custom assays, niche organisms, application-specific panels, rapid turnaround, and outsourced genomic services. In our view, this creates distinct competitive pathways rather than a single hierarchy. Scale is particularly valuable in high-volume standardized workflows, whereas specialization can create defensible positions where customers prioritize customization, speed, or domain-specific expertise.
The full report benchmarks competitive positioning across platform scale, assay content, installed base, manufacturing capacity, service throughput, technology breadth, application coverage, software capabilities, customer relationships, and geographic reach. Where sufficiently granular information is available, the competitive intelligence can also be structured into a dataset tracking company, platform, assay type, technology, installed base, capacity, applications, customer segment, geography, service model, and strategic capability, enabling users to filter competitors by market segment, benchmark capabilities, and identify areas of competitive overlap or whitespace.
How Concentrated is the Genotyping Market, and Where Does Competitive Fragmentation Remain Highest?
The competitive structure varies materially by technology and business model. Microarray and sequencing platforms tend to exhibit higher concentration because substantial R&D requirements, manufacturing complexity, installed-base effects, and ecosystem dependencies create meaningful barriers to entry.
By contrast, genotyping services remain more fragmented across regional laboratories and specialist providers. Our analysis indicates that market concentration is therefore driven less by genotyping demand itself than by the capital intensity, technology requirements, and customer integration associated with each layer of the value chain.
Our assessment is that a single market-share ranking would obscure these structural differences. Platform suppliers compete primarily through installed base, technology breadth, assay content, throughput, and ecosystem depth, while assay and reagent providers compete through content, workflow compatibility, and application specificity. Service providers are differentiated more heavily by capacity, turnaround time, geographic reach, specialized expertise, and customer relationships. This creates distinct competitive structures within the broader genotyping market.
In our view, share movement is most meaningful when evaluated within comparable technology and business-model segments rather than across incompatible categories. The report therefore assesses company-level share, Top-5 and Top-10 concentration, segment-specific share, regional share, and changes in competitive position, while separating platform suppliers, assay/reagent providers, and service providers. This approach helps identify where scale advantages are strengthening, where specialist providers are gaining relevance, and where fragmentation continues to create opportunities for differentiation.
The full report provides a granular competitive-structure analysis covering market share, concentration ratios, segment-level positioning, regional share, and share movement across the major genotyping categories. Where sufficiently granular information is available, these metrics can also be structured into a dataset tracking company, business model, technology, segment, geography, estimated market share, Top-5/Top-10 concentration, and share change by year, enabling flexible competitive benchmarking and trend analysis.
Which Technology Capabilities are Defining the Next Competitive Frontier in Genotyping?
Technology differentiation is increasingly moving beyond standalone assay performance toward the ability to connect genotyping, data generation, analysis, and interpretation within a more integrated workflow. The benchmarking framework evaluates patent activity, R&D intensity, assay-design capabilities, array density, sequencing integration, automation, software, genotype-calling performance, and commercialization, providing a broader view of technological competitiveness. Our analysis indicates that technical leadership is increasingly determined by how effectively these capabilities translate into scalable, commercially deployable workflows.
The convergence of arrays and sequencing is particularly important because customers increasingly require both high-throughput predefined-marker analysis and broader variant characterization. At the workflow level, automated sample handling, cloud-based analysis, and AI-assisted interpretation can reduce manual intervention and improve scalability. Our assessment is that these capabilities become strategically significant when they improve reproducibility, turnaround time, analytical consistency, or the amount of usable genomic information generated per sample.
In our view, the competitive frontier is therefore shifting toward integrated genotyping-to-interpretation workflows rather than isolated laboratory technologies. Providers that can connect wet-lab performance with downstream genotype calling, bioinformatics, and interpretation may be better positioned to capture value across more stages of the workflow. Multiomic integration could further expand this opportunity where customers seek to combine genotype information with other molecular datasets, although commercial significance will depend on demonstrated workflow utility and adoption.
The full report benchmarks companies across R&D intensity, patent activity, assay design, marker density, sequencing integration, automation, software, genotype-calling capabilities, AI-assisted analysis, commercialization, and workflow integration. Where sufficiently granular information is available, these indicators can also be structured into a dataset tracking company, technology, patents, R&D activity, platform capability, array density, sequencing integration, automation level, software functionality, analytical performance, and commercialization status, enabling technology-gap analysis and benchmarking of emerging competitive capabilities.
Which Applications and Regions Offer the Most Distinct Competitive Opportunities in Genotyping?
Competitive positioning varies by application because each use case requires a different combination of assay content, throughput, interpretation, workflow economics, and domain expertise. Application benchmarking spans pharmacogenomics, precision medicine, population genetics, disease research, agricultural genomics, animal genetics, consumer genomics, and biopharma research. Our analysis indicates that competitive relevance is increasingly application-specific: capabilities that create differentiation in population-scale studies may not provide the same advantage in clinical pharmacogenomics or specialized agricultural applications.
Geographic dynamics reinforce these differences. North America remains a major center for platform-led genotyping activity, while Europe combines established research capabilities with pharmaceutical and clinical demand. Asia Pacific is expanding its competitive significance through growing sequencing infrastructure and agricultural-genomics activity. Our assessment is that regional opportunity is increasingly determined by the interaction between genomic infrastructure, research and biopharma activity, agricultural requirements, laboratory capacity, and cost economics rather than market size alone.
Local laboratories and specialized service providers retain relevance where customers prioritize rapid turnaround, regulatory familiarity, language support, local relationships, or lower-cost outsourcing. In our view, this creates a two-level geographic opportunity structure: global platforms can benefit from scale and technology ecosystems, while regional providers can compete through proximity, customization, and market-specific expertise. The resulting competitive landscape is therefore likely to remain differentiated across both applications and geographies.
The full report benchmarks companies by application, region, technology, customer segment, service model, and competitive capability, identifying areas of concentration and potential whitespace across major markets. Where sufficiently granular information is available, this intelligence can also be structured into a dataset tracking company, application, technology, geography, customer type, service model, capacity, turnaround, and competitive capability, enabling users to compare application-specific positioning and regional expansion opportunities.
Which Combination of Platform Scale and Application Relevance Defines Strategic Positioning in Genotyping?
Leading company profiles assess headquarters, ownership, revenue, genomics exposure, product portfolio, technology platforms, geographic footprint, manufacturing capabilities, R&D, patents, strategic partnerships, acquisitions, customer relationships, and application exposure. Our analysis indicates that competitive strength is not determined by scale alone. The ability to convert platform capabilities into relevant applications, maintain differentiated content, and establish durable customer relationships increasingly determines the strategic value of a company within the genotyping ecosystem.
Our assessment is that the market contains several distinct competitive archetypes. Platform leaders benefit from broad technology ecosystems and installed bases, while scale-driven participants leverage manufacturing, distribution, and service capacity. Technology specialists compete through differentiated platforms or assay capabilities, whereas application specialists focus on areas such as pharmacogenomics, agricultural genomics, or animal genetics. Regional challengers and service-focused providers can differentiate through proximity, customization, turnaround time, and market-specific expertise.
In our view, this positioning framework provides a more meaningful assessment than a single composite score because companies with fundamentally different business models create value through different mechanisms. A technology specialist may possess limited overall genomics revenue but hold strong relevance in a specific application, while a diversified platform company may have greater scale but less exposure to a specialized niche. The strategic implication is that competitive positioning should be evaluated against documented business exposure, capability depth, and application relevance within each market segment.
The full report provides detailed company profiles and positioning analysis covering business scale, genomics exposure, technologies, products, geographic presence, manufacturing, R&D, patents, partnerships, M&A, customers, and application exposure. Where sufficiently granular information is available, these attributes can also be structured into a dataset tracking company, ownership, headquarters, revenue exposure, technology, products, applications, geography, facilities, R&D, patents, partnerships, acquisitions, and strategic positioning, enabling flexible peer-group comparisons and capability benchmarking without relying on a proprietary scoring index.
How Will Genotyping Evolve as the Market Shifts from Data Generation Toward Actionable Genomic Information?
The base case anticipates continued high-teens growth through 2030, with the market approaching approximately USD 60 billion under a broad market definition. Our analysis indicates that growth will increasingly be supported by pharmacogenomics, population-scale studies, agricultural breeding, biopharma biomarker programs, automation, and sequencing-enabled workflows. The market is therefore expected to expand not only through higher testing volumes but also through broader integration of genotyping into clinical, research, and agricultural decision-making.
The upside case assumes faster clinical adoption, stronger pharmacogenomic reimbursement, accelerating agricultural genomics, and continued reductions in sequencing and genotyping costs. Under these conditions, lower testing economics and stronger evidence of clinical utility could accelerate the conversion of genomic data into routine applications. Conversely, the downside case reflects slower clinical translation, research-budget pressure, substitution by broader sequencing workflows, and regulatory constraints on genomic-data use, which could limit adoption in cost-sensitive or highly regulated applications.
Our assessment is that the competitive basis of the market will change materially through 2035. The central question will increasingly move from “Who can generate genotype data?” to “Who can generate actionable genomic information at the lowest total cost and highest throughput?” This shift places greater importance on workflow integration, automation, analytical capabilities, and application-specific relevance rather than assay performance in isolation.
The resulting profit pools are likely to become increasingly concentrated around integrated solutions combining assay content, instruments, consumables, automation, bioinformatics, interpretation, and application-specific services. The full report evaluates these scenarios through technology adoption, application expansion, cost trends, clinical translation, reimbursement, regulatory conditions, sequencing substitution, and workflow integration to identify the factors most likely to shape market growth and competitive positioning through 2035.
Key Strategic Questions Addressed
- How large is the Genotyping Market, and how fast will it grow between 2026 and 2035?
- Which technologies will capture the next phase of market growth?
- Which applications represent the largest growth opportunities?
- How are pricing and workflow economics changing?
- Which companies hold the strongest competitive positions?
- Where are the most attractive geographic and application white spaces?
- How will sequencing, automation, and AI reshape the Genotyping Market through 2035?
Genotyping Market Segments
By Technology
- Microarray-Based Genotyping
- PCR-Based Genotyping
- Allele-Specific Assays
- Probe-Based Assays
- NGS-Based Genotyping
By Application
- Pharmacogenomics
- Precision Medicine
- Population Genetics
- Disease Research
- Agricultural Genomics
- Animal Genetics
- Ancestry and Consumer Genomics
- Biopharmaceutical Research
By Region
- North America
- Europe
- Asia Pacific
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting