
Hydrogen Market Size, Key Companies, Trends, Segments, and Forecast 2026-2035
Hydrogen Market (By Value Chain Stage: Hydrogen Production, Hydrogen Storage, Hydrogen Transportation & Distribution, Hydrogen Refueling Infrastructure, By Capacity, Components, Hydrogen Applications; By Technology:Â Production Technologies, Fuel Cell Technologies; By End-Use Industry:Â Transportation, Industrial Manufacturing, Utilities & Energy Storage, Residential & Commercial) - Global Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2035
Source: https://www.precedenceresearch.com/hydrogen-market
 Get a Sample
 Table Of Content


What is the Hydrogen Market Size?
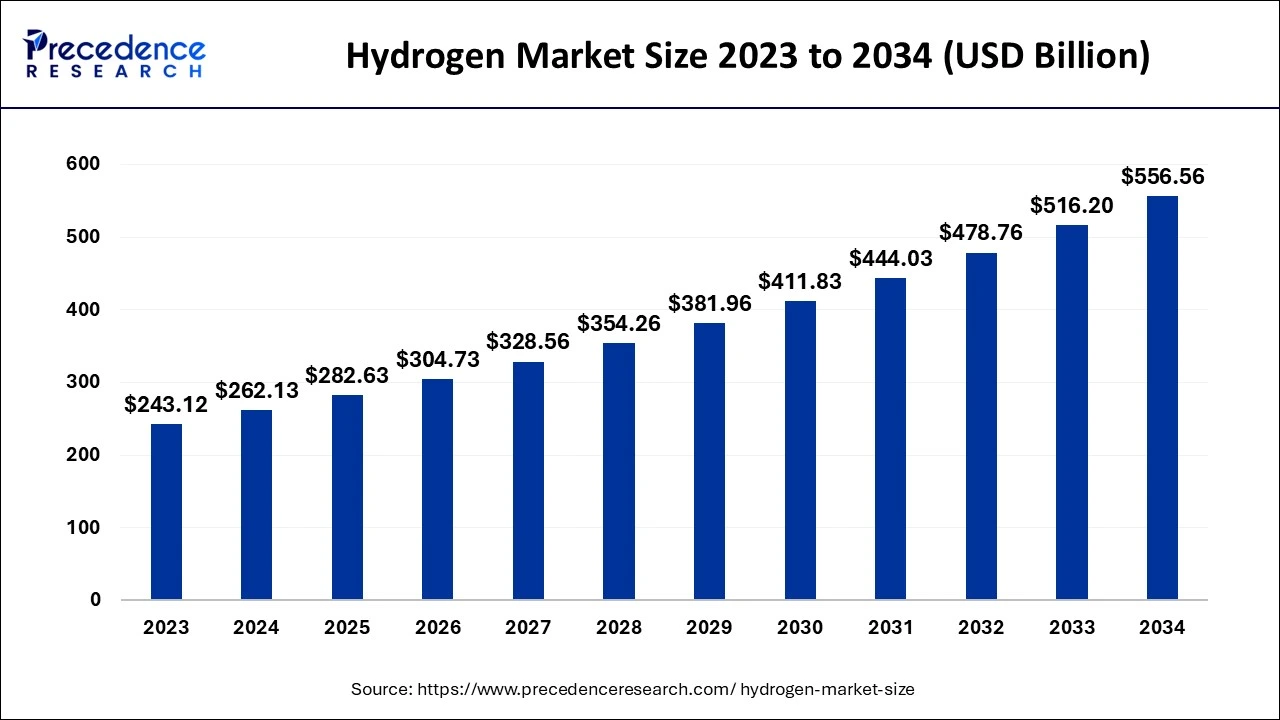
The global hydrogen market size was estimated at USD 304.73 billion in 2026 and is projected to reach approximately USD 594.97 billion by 2035, representing a CAGR of 7.73% from 2026 to 2035. The hydrogen market is driven by the growing demand for clean energy sources.
Hydrogen Market Key Takeaways
- In terms of revenue, the hydrogen market is valued at $304.73 billion in 2026.
- It is projected to reach $594.97 billion by 2035.
- The hydrogen market is expected to grow at a CAGR of 7.73% from 2026 to 2035.
- Asia Pacific dominated the hydrogen market and recorded the highest market share of 36% in 2026.
- North America is observed to be the fastest growing in the market during the forecast period.
- By sector, the gray hydrogen sub-segment dominated the hydrogen market in 2026.
- By application, the chemical & refinery segment dominated the hydrogen market in 2026.
Market Overview
Green hydrogen, or hydrogen derived from renewable resources, is a clean fuel that only releases water in fuel cells. It plays a crucial role in assisting nations and businesses in achieving their decarbonization goals and cutting greenhouse gas emissions, which is essential for addressing climate change. Hydrogen can be produced through several pathways, including renewable-powered electrolysis, nuclear-powered electrolysis, and natural-gas reforming. The production pathway and associated emissions determine its environmental profile. This variety of production techniques improves countries' energy security, lessening reliance on imported fossil fuels.
Global investments in hydrogen projects are surging, with countries like Germany, Japan, and Australia committing billions to develop hydrogen infrastructure. For example, the European Union has announced plans to invest over €400 billion in hydrogen technologies by 2030.
Many governments are implementing hydrogen strategies. The U.S. Department of Energy launched the Hydrogen Shot initiative, targeting a significant reduction in the cost of clean hydrogen production. Countries like Japan are enhancing their hydrogen roadmaps, focusing on domestic production and international partnerships.
How is AI Being Implemented in Hydrogen Industry?
By optimizing operational conditions (such as temperature, pressure, and input energy), cutting expenses, and raising yields, artificial intelligence (AI) helps increase the efficiency of electrolyzers used in the manufacture of hydrogen. By detecting inefficiencies in the hydrogen supply chain, from production to consumption, AI-driven analysis can assist in lowering overall production and operating costs. To make the process cleaner and more sustainable, it helps integrate carbon capture technology with hydrogen production, primarily blue hydrogen (hydrogen produced from natural gas with carbon capture).
Hydrogen Market Growth Factors
- The need for hydrogen, a clean and adaptable fuel, is driven by the global transition to renewable energy sources and the mounting push to lower carbon emissions.
- Electric vehicles that use hydrogen fuel cells are a viable substitute for battery-powered vehicles, particularly heavy-duty and long-distance driving.
- Hydrogen is used in ammonia production and petroleum refining and is being explored as a lower-emissions input for steelmaking. Hydrogen will become increasingly in demand as industry works to reduce carbon footprints.
- To encourage the development and uptake of hydrogen technology, governments everywhere are putting laws into place and offering incentives. Tax credits, infrastructure, and R&D expenditures are all included in this.
Market Dynamics
Driver
Focus on Decarbonization from Industries
Many industries, especially those reliant on fossil fuels, face pressure to reduce their carbon footprint. Hydrogen, particularly green hydrogen produced from renewable energy sources, is viewed as a viable solution for decarbonizing various sectors, including transportation, manufacturing, and energy. The transportation sector is also a major contributor to greenhouse gas emissions. Hydrogen fuel-cell vehicles produce water at the point of use, while their overall emissions depend on how the hydrogen is produced and delivered. Companies like Toyota and Hyundai have developed hydrogen FCVs, and infrastructure projects are underway to expand hydrogen refueling stations, facilitating broader adoption.
Restraints
Lack of infrastructure
Green hydrogen production depends on electrolysis, necessitating large capital expenditures in production facilities. Because there are now so few electrolysis facilities, green hydrogen is more expensive than hydrogen from fossil sources. Hydrogen refueling stations are essential for fuel-cell road vehicles, while other hydrogen applications require infrastructure suited to their specific production, storage, and distribution needs. The widespread use of hydrogen-powered cars is now hampered by the scarcity of these stations, particularly when contrasted with the extensive networks of charging stations for gasoline or electric vehicles.
Storage and transportation challenges
The volumetric energy density of hydrogen is lower than that of traditional fuels. This creates problems for compact storage since a lot of hydrogen is needed to store the same quantity of energy. Another approach is to transport compressed hydrogen in tubes or cylinders; however, this method is less effective for considerable amounts because the cylinders need to be heavy and take up space. There are additional difficulties in handling and delivering these high-pressure containers logistically.
Opportunity
Adoption hydrogen technologies
Advances in alkaline and proton exchange membrane (PEM) electrolysis may improve the efficiency and economics of renewable hydrogen production, although costs remain dependent on electricity prices, equipment costs, and operating conditions. With longer ranges and faster refueling than battery electric vehicles (BEVs), hydrogen is becoming a competitive fuel for heavy-duty vehicles (buses, lorries, trains) and maritime applications. Subsidies, grants, and tax breaks for research and development are just a few of the policies and incentives numerous governments are implementing to support hydrogen technologies.
Segment Insights
Value Chain Stage Insights
The hydrogen production segment dominated the market with 45.20% market share in 2026. The dominance of the segment can be attributed to the innovations in hydrogen production technologies and the increasing role of hydrogen in decarbonization efforts. Also, Hydrogen is considered a promising solution for energy storage, especially for maintaining the intermittency of renewable energy sources.
The hydrogen refueling infrastructure segment is projected to register a CAGR of 12.80% during 2026-2035, The dominance of the segment can be credited to the increasing demand for zero-emission vehicles along with the ongoing development of cost-effective hydrogen production and storage technologies. Moreover, incentive programs such as tax credits and tax breaks are being provided to optimise the purchase and use of FCEVs, impacting positive segment growth.
Technology Insights
The production technologies segment dominated the market with a 63.50% market share in 2026. The dominance of the segment can be credited to the advancements in electrolysis and renewable energy technologies, and the rising need for cleaner energy sources. Ongoing investments in hydrogen infrastructure, such as transportation and storage facilities, are important for facilitating the widespread use of hydrogen.
The fuel cell technologies segment is expected to grow at the highest CAGR of 13.60% over the forecast period. The growth of the segment can be linked to the growth in stationary power applications and the growing utilisation of fuel cell electric vehicles (FCEVs). Furthermore, governments across the globe are implementing policies to support hydrogen infrastructure and fuel cell adoption, such as subsidies, incentives, and investments in research and development.
End-Use Industry Insights
The industrial manufacturing segment held a 52.70% market share in 2026. The dominance of the segment is owed to the rising demand for cleaner fuels, coupled with innovations in hydrogen production technologies. Moreover, Hydrogen plays an essential role in various industrial processes, such as methanol synthesis, ammonia production, and metal refining.
The transportation segment is expected to grow at the highest CAGR of 14.30% in 2026. The dominance of the segment is due to the growing demand to minimize carbon emissions and ongoing developments in hydrogen fuel cell technology. The transportation sector, especially public transport and heavy-duty vehicles, is rapidly exploring hydrogen fuel cell technology as a clean energy substitute.
Regional Insights
What is the Asia Pacific Hydrogen Market Size?
The Asia Pacific hydrogen market size was exhibited at USD 109.70 billion in 2026 and is projected to be worth around USD 217.90 billion by 2035, growing at a CAGR of 7.91% from 2026 to 2035.
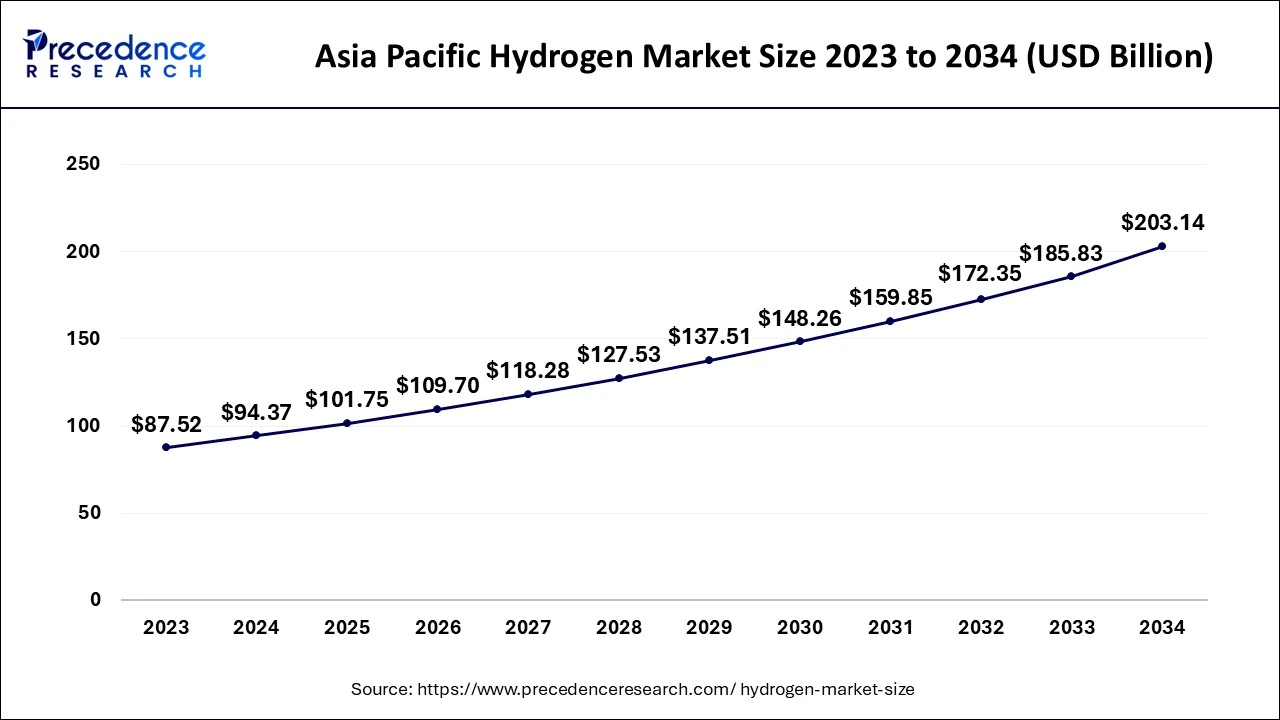
Asia Pacific dominated the global green hydrogen market with the largest share in 2026. Favourable policies and initiatives by governments in the region are promoting the adoption of clean energy solutions like green hydrogen. Abundance of renewable energy resources such as solar, hydro ad wind is contributing” with “The abundance of renewable energy resources, including solar, hydropower, and wind, is contributing. Additionally, growing focus on reducing carbon emissions, advancements in electrolyzer technology, rising investments in renewable energy infrastructure for energy security as well as increased collaborations between local and international companies for deploying large-scale green hydrogen projects is bolstering the region's market growth. Regional players, like Australia, Japan and South Korea are highly focused on adoption of green hydrogen.
North America's Hydrogen Growth Fueled by Clean Energy Policies and Heavy-Duty Transportation Demand
Governments in North America have viewed hydrogen as a vital part of their clean energy plans due to their aggressive decarbonization goals and pledges to cut greenhouse gas (GHG) emissions. Hydrogen is a flexible way to cut emissions, especially in areas like power generation, heavy industry, and long-distance transportation that are challenging to electrify. Transportation, especially heavy-duty vehicles like trucks, buses, and trains, uses more hydrogen fuel cells. For example, California has taken the lead in establishing hydrogen refueling stations and policies that support hydrogen fuel cell vehicles. Demand is further increased by the aviation and maritime industries' exploration of hydrogen as a zero-emission fuel.
What are the Key Trends in the Hydrogen Market in Europe?
Europe is expected to witness significant growth during the forecast period because of robust decarbonization activities, long-term government subsidies, and rapid investment in infrastructure for renewable hydrogen. EU renewable-energy rules establish targets for renewable fuels of non-biological origin, including renewable hydrogen, in specified sectors. Cite the applicable Renewable Energy Directive provisions and distinguish binding targets from national implementation measures. Meanwhile, all sorts of industries, including the car production plant and steel mill, are under the heading of green hydrogen technology so as to create environmentally safe carbon footprints in production.
Germany Market Trends
Germany is an important hydrogen market in Europe, supported by industrial demand, national hydrogen policies, and plans for domestic production and imports. It is also committing significant resources towards both importing green hydrogen into the country and its own production, as it plays a key role in both demand and development of the technical solutions required for this field.
What are the Advancements in the Hydrogen Market in Latin America?
Latin America is expected to witness significant growth in the coming years due to its extremely high share of renewable electricity, which provides a strong foundation for low-cost green hydrogen production. A major advancement in the region is the rapid development of export-oriented green hydrogen hubs. The region is the increasing focus on industrial decarbonization and hydrogen derivatives, especially in hard-to-abate sectors such as steel, refining, fertilizers, and heavy transport.
Brazil Market Trends
Brazil has potential to develop hydrogen projects because of its industrial base, renewable electricity resources, and government-backed National Hydrogen Program (PNH2). Brazil is focusing heavily on scaling hydrogen for domestic industrial decarbonization (fertilizers, steel, refining) and positioning itself as a future global exporter of green hydrogen and hydrogen-based fuels.
How is the Middle East and Africa Region Growing in the Hydrogen Market?
The Middle East and Africa are expected to have significant market growth in the upcoming years, driven by abundant solar and wind renewable energy projects, robust fiscal policies, and the forward-thinking decarbonization of national governments. Crucially, leaders in green hydrogen initiatives, like Saudi Arabia and the UAE, and this has made them potential global hydrogen and green ammonia providers too. Governments are developing hydrogen corridors and port infrastructure and large-scale industrial clusters that would integrate hydrogen into international trade networks.
Saudi Arabia Market Trends
Saudi Arabia leads the region mainly due to its massive giga-projects, complemented by robust governmental backing and early launches of initiatives such as the NEOM Green Hydrogen Project. It further boasts a broad pipeline of hydrogen, from refining and chemical to ammonia export projects, establishing its role as a pioneer in blue and green hydrogen technologies.
Hydrogen Market Companies
- Linde plc
- Chevron Corporation
- Saudi Arabian Oil Co.,
- Worthington Industries
- INOX India Limited
- Hexagon Purus
- NPROXX
- Cryolor
- Pragma Industries
- BayoTech
- Luxfer Gas Cylinders
- Chart Industries
- Weldship Corporation
Recent Developments
- In May 2025, China began production at its first green hydrogen project at Daye Green Power's $476m facility in Hubei province, which uses electrolysers supplied by Sungrow Hydrogen. The project initiated in the 27MW facility in the city of Daye is the first in China which stores hydrogen in an underground cavern and employs both 5MW alkaline electrolysers and a 2MW PEM machine.
- In May 2025, MT Group in collaboration with Vilnius City Municipality and Vilnius Heat Networks, the largest supplier of centralized heat in Lithunia has signed an engineering, procurement and construction (EPC) contract for building a 3MW green hydrogen plant in Vilnius, Lithuania. The project is scheduled to start up in the first half of 2026 is anticipated to produce up to 3.45 million metres of green hydrogen annually for replacing diesel-fuelled public transport buses in the city.
- In May 2025, UAE's clean energy company, Masdar signed a non-binding Letter of Intent (LOI) with OMV, Austria's integrated energy firm for jointly exploring the development of green hydrogen, synthetic sustainable aviation fuel (eSAF) and other eco-friendly projects.
Hydrogen Market Segments
By Value Chain Stage
- Hydrogen Production
- Green Hydrogen
- Alkaline Electrolysis
- PEM Electrolysis
- Solid Oxide Electrolysis
- Blue Hydrogen (SMR + Carbon Capture)
- Grey Hydrogen (SMR without CCS)
- Turquoise Hydrogen (Methane Pyrolysis)
- Biomass Gasification
- Photoelectrochemical and Biological Methods (emerging)
- Green Hydrogen
- Hydrogen Storage
- Physical Storage
- Compressed Hydrogen (Type I–IV cylinders)
- Liquid Hydrogen (Cryogenic storage)
- Material-based Storage
- Metal Hydrides
- Chemical Hydrides
- Carbon-based storage
- Geological Storage
- Salt Caverns
- Depleted Oil & Gas Fields
- Aquifers (under evaluation)
- Physical Storage
- Hydrogen Transportation & Distribution
- Pipeline
- Dedicated Hydrogen Pipelines
- Natural Gas Blending Pipelines
- Road Transport
- Tube Trailers (high-pressure gas transport)
- Cryogenic Liquid Hydrogen Trucks
- Rail Transport
- Maritime Transport
- LOHC (Liquid Organic Hydrogen Carrier)
- Ammonia as Carrier
- Liquid Hydrogen Shipping
- Pipeline
- Hydrogen Refueling Infrastructure
- Refueling Station Types
- Permanent (Fixed) Stations
- Mobile/Temporary Stations
- Refueling Station Types
- By Capacity
- <500 kg/day
- 500-1,000 kg/day
- 1,000 kg/day
- Components
- Dispensers
- Compressors
- Storage Vessels
- Cooling Units
- Safety & Control Systems
- Hydrogen Applications
- Mobility
- Passenger Cars
- Buses
- Trucks (HDV)
- Rail (Hydrogen Trains)
- Ships & Ferries
- Aircraft (short-range, prototype)
- Industrial
- Steel Production (DRI process)
- Ammonia & Fertilizer Production
- Refining & Petrochemical Processes
- Electronics Manufacturing
- Power & Utilities
- Stationary Fuel Cells
- Peaking Power Plants
- Grid-Scale Hydrogen Storage (Power-to-Gas)
- Residential & Commercial
- Hydrogen for Heating
- CHP Systems (Combined Heat and Power)
- Mobility
By Technology:
- Production Technologies
- PEM Electrolyzers
- Alkaline Electrolyzers
- Solid Oxide Electrolyzers
- SMR with/without CCS
- Autothermal Reforming (ATR)
- Pyrolysis (Methane)
- Biomass Gasification
- Fuel Cell Technologies
- Proton Exchange Membrane (PEMFC)
- Solid Oxide Fuel Cells (SOFC)
- Alkaline Fuel Cells (AFC)
- Direct Methanol Fuel Cells (DMFC)
By End-Use Industry:
- Transportation
- Automotive
- Rail
- Aviation
- Maritime
- Industrial Manufacturing
- Chemicals
- Steel
- Glass
- Electronics
- Utilities & Energy Storage
- Peak Shaving
- Seasonal Storage
- Grid Balancing
- Residential & Commercial
- Heating Systems
- Microgrids
- Building Energy Supply
By Geography
- North America
- Asia Pacific
- Europe
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting