



Cell and Gene Therapy Clinical Trials Market Trends, Leading Companies, Company Revenue / Sales Performance, Clinical Trial Volume, R&D Spending, Technology Adoption, Reimbursement Analysis, Competitive Landscape, and Growth Outlook
The global cell and gene therapy clinical trials market size is stood to hit around USD 54.29 billion by 2034 from USD 13.32 billion in 2024 with a CAGR of 15.09% The market growth is driven by rising R&D investment, increasing demand for novel therapies, growing adoption of cell and gene therapies for cancer and rare diseases, supportive regulatory policies, and an expanding clinical trial pipeline.
Source: https://www.precedenceresearch.com/cell-and-gene-therapy-clinical-trials-market
 Get a Sample
 Table Of Content
Cell and Gene Therapy Clinical Trials Market Size and Forecast 2025 to 2034
The global cell and gene therapy clinical trials market size was estimated at USD 13.32 billion in 2024 and is predicted to increase from USD 15.33 billion in 2025 to approximately USD 54.29 billion by 2034, expanding at a CAGR of 15.09% from 2025 to 2034. Gene therapy entails the delivery of genetic material, frequently in the form of transport or vector, and the incorporation of the gene into the appropriate bodily cells. Cell treatment involves giving the patient cells the right purpose. Gene therapy and cell treatment are sometimes combined in operations.
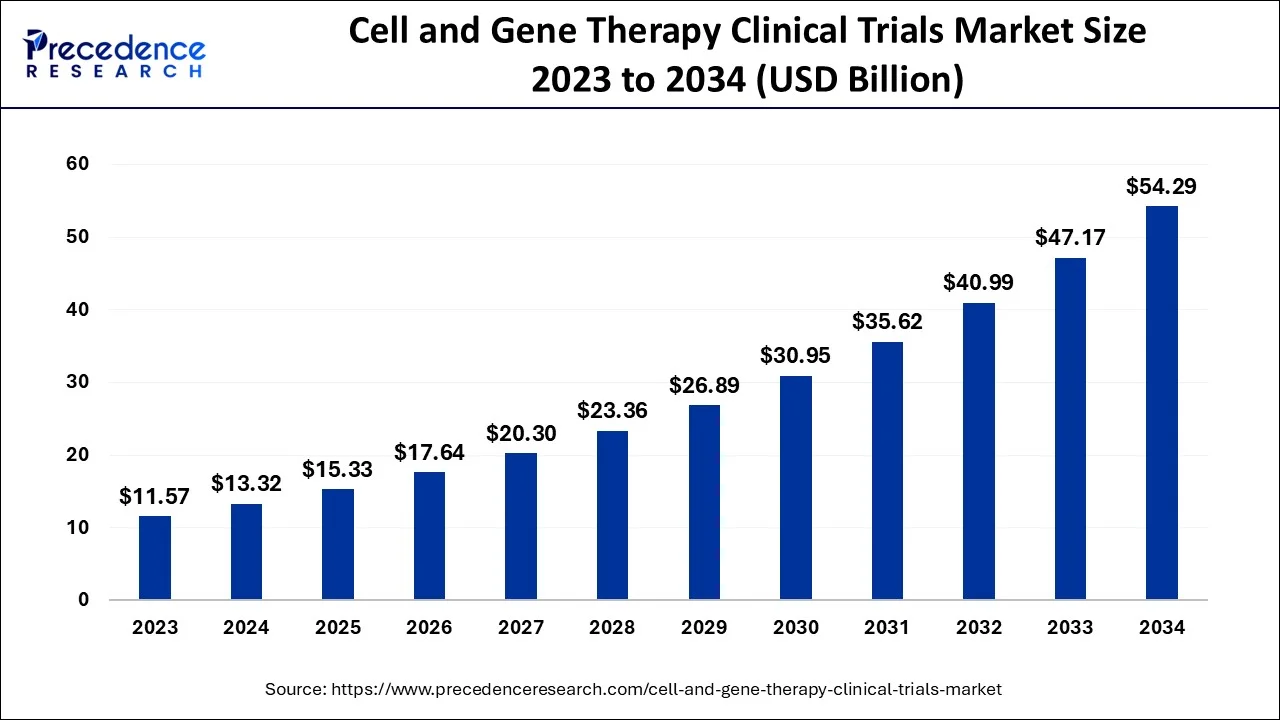
Cell and Gene Therapy Clinical Trials Market Key Takeaways
- In terms of revenue, the global cell and gene therapy clinical trials market was valued at USD 13.32 billion in 2024.
- It is projected to reach USD 54.29 billion by 2034.
- The market is expected to grow at a CAGR of 15.09% from 2025 to 2034.
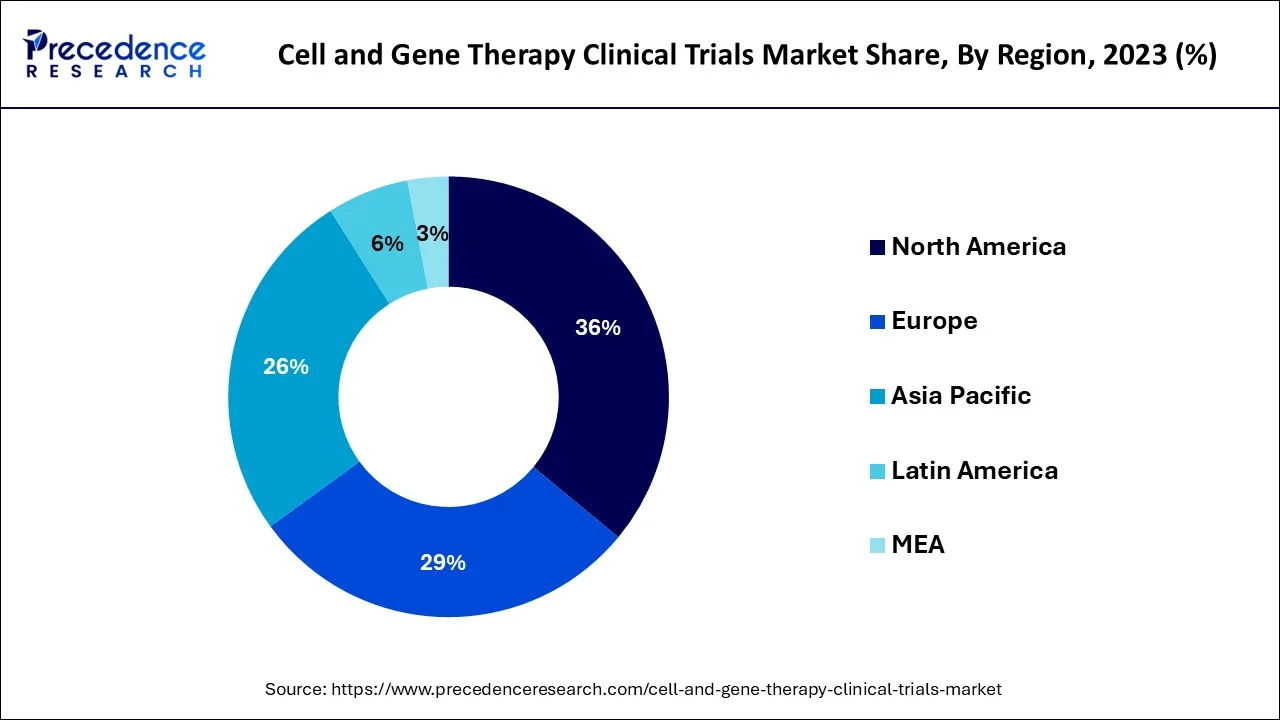
- North America dominated the global market with the largest market share of 36% in 2024.
- Asia Pacific is expected to expand at the fastest CAGR between 2024 and 2034.
- On the basis of phase, the phase II segment dominated the market and contributed more than 54% of the total revenue share in 2024.
- On the basis of indication, the oncology sector led the global market and contributed more than 47.70% of the total revenue share in 2024.
Market Overview
The cell and gene therapy clinical trials market includes planning, execution, monitoring, and management of clinical trials that evaluate cell- and gene based treatments. The clinical trial conduction includes protocol design, patient recruitment, clinical monitoring, data management, site management, regulatory affairs, pharmacovigilance, and post-trial analysis. These trials are designed to evaluate the safety and efficacy of advanced therapies including Cat cell therapy, CRISPR gene editing and stem cell research.
Cell and Gene Therapy Clinical Trials Market Growth Factor
An increase in R&D financing, increasing patient demand for novel therapies, rising interest in cell and gene therapies for cancer treatment, and a supportive regulatory climate are the main market drivers. A brand-new front in the battle against numerous fatal illnesses, such as cancers and uncommon genetic conditions, is cell and gene therapy (CGT). It stands for the most recent round of invention in the life sciences sector. Early in the 2020s, the COVID-19 epidemic decreased the number of gene therapy clinical trials because the majority of research was devoted to treating and identifying COVID-19.
An increase in R&D financing, increasing patient demand for novel therapies, rising interest in cell and gene therapies for cancer treatment, and a supportive regulatory climate are the main market drivers. A brand-new front in the battle against numerous fatal illnesses, such as cancers and uncommon genetic conditions, is cell and gene therapy (CGT). It stands for the most recent round of invention in the life sciences sector. Early in the 2020s, the COVID-19 epidemic decreased the number of gene therapy clinical trials because the majority of research was devoted to treating and identifying COVID-19.
In comparison to small-molecule compounds, which had an R&D success rate of 8.2% between 2008 and 2018, CGT medicines had an 11% success rate from Phase I to commercialization. The size and sophistication of the new businesses joining the industry are both growing significantly. Small biotech companies made up a large portion of the early movers in this industry. The important biopharma companies attracted a lot of attention. Most of the big pharmaceutical firms are now making CGT investments. For instance, Novartis announced in December 2021 that it had inked a purchase deal with Gyroscope Therapeutics, a provider of ocular gene therapy.
With this purchase, Novartis will be better positioned to offer gene therapy for eye diseases. Other notable purchases include Gilead's purchase of Kite Pharma, Roche's purchase of Spark Therapeutics, and Bristol-Myers Squibb's purchase of Celgene. Since the year 2000 and the advent of new technologies, interest in the CGT sector has steadily increased. By 2025, the FDA projected that it would authorize 10 to 20 novel BLAs for cell therapy products annually in the United States alone. The clearance of CGT by the American FDA has also increased recently.
For instance, the FDA granted CAR T-Cell Therapy, created by Penn Medicine for the treatment of relapsed or Refractory Follicular Lymphoma (FL) in adults, its third clearance in May 2022. Such approvals are anticipated to raise interest in CGT study, which will fuel market expansion. In addition to being used to treat cancer, CGT is increasingly significant in the management of COVID-19. The FDA authorized BioCardia to begin a Phase I/II clinical study of BCDA-04 in adults recovering from COVID-19-linked acute respiratory distress syndrome in April 2022 after the company's Investigational New Drug (IND) proposal was accepted. (ARDS). Such permits are probably going to help the industry expand.
- Growing financing, expenditures in R&D, and successful product releases are accelerating market growth.
- The market has been mainly led by an exponential increase in the trial pipeline and an increase in the number of regulatory clearances for novel medications.
- The market of cell and gene therapy has witnessed significant growth over the past few years with pharma firms partnering to create effective and accessible therapies for patients
Market Outlook
- Industry growth overview - The cell and gene therapy clinical trials market is expected to grow as demand is increasing for precision medication and gene editing technologies, which supports rising clinical trial activity.
- Global expansion - Clinical trials are expanding across North America, Europe and Asia Pacific regions due to rising investment and strong research infrastructure development.
- Major Investors - Pharmaceutical companies, biotechnology firms, contract research organisations (CROs) and government backed funds are strengthening clinical trial activities in cell and gene therapies. Major investors in the market include Novartis AG, Gilead Sciences, Bristol Myers Squibb, RA Capital Management, OrbiMed, ARCH Venture Partners and Vertex Pharmaceuticals.
Market Scope
| Report Coverage | Details |
| Market Size in 2024 | USD 13.32 Billion |
| Market Size in 2025 | USD 15.33 Billion |
| Market Size by 2034 | USD 54.29 Billion |
| Growth Rate from 2025 to 2034 | CAGR of 15.09% |
| Largest Market | North America |
| Fastest Growing Market | Asia-Pacific |
| Base Year | 2024 |
| Forecast Period | 2025 to 2034 |
| Segments Covered | Phase, Indication, and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America and Middle East & Africa |
Market Dynamics
Drivers
Increasing prevalence of cardiovascular disease
Over the projection period, rising cardiovascular disease rates are anticipated to fuel market development for cell and gene therapies. For instance, according to a World Health Organization study released in June 2021, 32% of all deaths worldwide in 2019 were attributed to cardiovascular illnesses, killing an estimated 17.9 million people. Heart attacks and strokes worldwide accounted for 85% of these deaths. Globally, cardiovascular illnesses were responsible for 38% of the 17 million premature deaths (under the age of 70) in 2019 that were caused by non-communicable conditions. Additionally, the same source estimates that by May 20, 2022, low- and middle-income (LMIC) nations like Bangladesh and India will account for nearly 90% of all COPD-related fatalities in people under the age of 70 worldwide.
Challenges
High cost
Gene therapy's high upfront cost and the absence of benevolent reimbursement policies are two factors that may limit market development to some degree during the projection period. Other factors that are anticipated to impede market growth in the future include a lack of awareness of cell and gene therapy, the absence of developed healthcare infrastructure in developing and underdeveloped nations worldwide, and the rising number of difficulties in developing products for gene and cell therapy.
Over the course of the forecast period, factors such as the rising prevalence of adverse immune system reactions, severe off-target effects, difficulties with vector delivery to the target cell, and growing challenges with scalability and manufacturing of cell and gene therapy products are predicted to further restrict the uptake of these treatments and possibly restrain market revenue growth.
Opportunities
Increasing private and public investments
Cell and gene therapy businesses are drawing more private and governmental funding despite the low number of approvals. Over the past ten years, life sciences have seen a sharp rise in private equity and capital funding. Similarly, there has been a notable increase in funding in businesses that provide cell and gene therapy. For example, spending has increased dramatically, going from USD 362 million in 2020 to almost USD 68 billion in 2021. The demand for outsourcing is anticipated to rise as a result, fueling the expansion of the cell and gene therapy production industries.
Segmental Insights
Phase Insights
The market has been divided into phases I, II, III, and IV on the premise of phases. Given that the majority of cell and gene therapies are in this stage of the clinical trial, the phase II section dominated the worldwide market in 2023 and made for the biggest part of more than 54% of the total revenue. Due to rising R&D expenditures, an increase in phase II clinical trials funded by both industry and non-industry, and the complexity of phase II clinical trials, the sector is also anticipated to expand at the fastest rate over the forecast period.
Additionally, the majority of studies involving cell and gene therapy are presently stopping short of finishing their research. Additionally, this adds to the segment market's largest portion. In 2022, the phase 1 segment is anticipated to record a sizable percentage. The successful transition of medications from non-clinical initiatives into First-in-Human clinical trials is one of the main factors contributing to the segment's growth. Even though phase I and phase II clinical trials for cell and gene therapy still make up the overwhelming majority of trials, the percentage of trials now in phase III and phase IV is marginally increasing. The market development in the later stages of clinical research is anticipated to be enhanced by this.
Indication Insights
Oncology, Cardiology, CNS, Musculoskeletal, Infectious Diseases, Dermatology, Endocrine, Metabolic, Genetic, Immunology & Inflammation, Ophthalmology, Hematology, Gastroenterology, and others make up the market's indications segment. With a revenue share of more than 47.70% in 2023, the oncology sector dominated the global market, and it is expected that it will continue to hold the lead throughout the projection period. Global data projects that in 2021, the cancer sector will alone account for 1,375 of the total number of CGT clinical trials. The investment in cancer emphasizes the significance of creating quick and effective CGT clinical study delivery methods and tackling scaling to commercialization challenges.
Due to the worldwide proliferation of the COVID-19 pandemic, clinical trials for cancer were put on hold in the early 2020s. However, due to the increasing burden of cancer globally, there has been a sizable increase in clinical trials for cancer in 2022 and is anticipated to expand at a faster pace during the forecast period. A greater interest in CGTs in cancer has been made possible by the creation of CAR-T cell therapies like Kymriah and Yescarta as well as their effectiveness in treating hematological malignancies. Global investments in this strategy to treat different kinds of cancer are being made by both biotech and pharmaceutical firms.
Regional Insights
U.S. Cell and Gene Therapy Clinical Trials Market Size and Forecast 2025 to 2034
The United States represents the largest share of the cell and gene therapy clinical trials market in North America. The growth is driven by a strong pharmaceutical and biotechnology industry, advanced healthcare infrastructure, and strong FDA support. The presence of major pharmaceutical companies and Contract Research Organizations (CROs) such as Pfizer, Gilead and Bristol Myers Squibb further drives market expansion. The strong investment from public and private companies in research and development and clinical trial conduct further supports market growth.
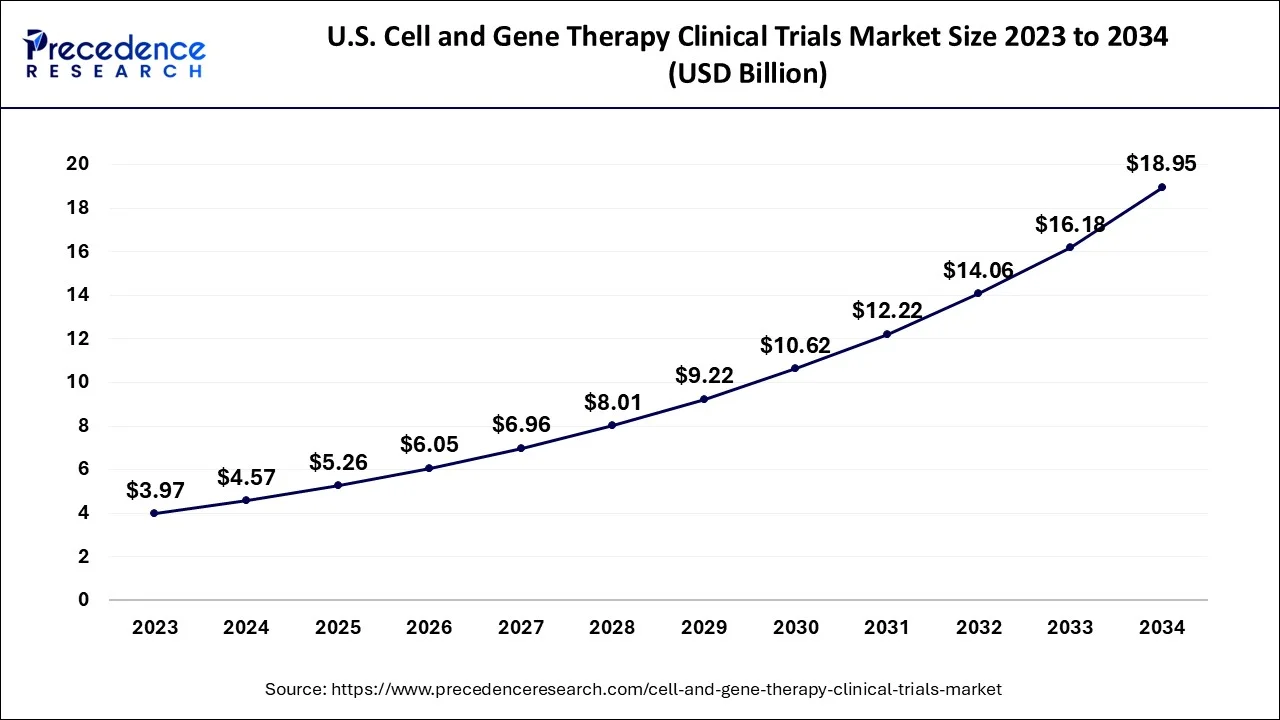
The U.S. cell and gene therapy clinical trials market size accounted for USD 4.57 billion in 2024 and is predicted to be worth around USD 18.95 billion by 2034, growing at a CAGR of 15.28% from 2025 to 2034.
In 2024, North America made for the biggest portion of worldwide revenue 36% and it is anticipated that it will continue to hold the lead throughout the forecast period. A favorable legislative climate, particularly in the US, is blamed for this. In addition, the United States is home to many of the world's top research institutions and has a well-established regulatory framework for conducting clinical trials. The region has a strong focus on oncology, with many trials evaluating cell and gene therapies for various types of cancer.
Asia Pacific is predicted to experience the fastest CAGR growth during the forecast period. Bioengineering firms with an emphasis on regenerative medicine are multiplying in the Asia Pacific region. The region is also anticipated to maintain its status as the center of cell research and therapy due to the constant growth of medical tourism hotspots like Thailand, Singapore, and India. Asia is also experiencing an increase in CGT clinical study subjects compared to North America and Europe. Due to the large patient population and low cost of testing, this is advantageous for the Asia Pacific industry.
China Market Trends
China accounts for the largest share of the cell and gene therapy clinical trials market in Asia-Pacific in 2025. The growth of the region is driven by a large patient base, strong government funding, and supportive regulatory frameworks. The growing investment in healthcare infrastructure and research capabilities is supporting market expansion. Rising prevalence of chronic disease and rare disease drives demand for new treatments. The regulatory agencies are reforming their protocols to smooth the approval of advanced research such as CAR-T and gene editing platforms. Global pharmaceutical companies are increasing partnerships with regional biotech firms, further strengthening market competitiveness.
Which Factors Made Europe a Significantly Growing Region in the Market?
Europe is expected to grow at a considerable CAGR in the cell and gene therapy clinical trials market in the coming period. The growth is driven by government supported healthcare systems and strong healthcare infrastructure. The increasing government support for advanced cell and gene therapies and growing investment in biotechnology research further support market growth. Countries including Germany, the United Kingdom, France, and Italy are strengthening cell therapy infrastructure and reimbursement pathways to support the adoption of advanced therapies.
Germany Market Trends
Germany leads the European cell and gene therapy clinical trials market in 2025 due to government backed research funding and strong presence of biotechnology companies. The growing collaboration among universities, research institutions, contract research organisations, and biotechnology and pharmaceutical companies is supporting advancement in the market. Munich, Berlin and Heidelberg remain major research centres in Germany with strong clinical infrastructure. The regulatory bodies across the country are supporting innovation in oncology treatments, which further supports market growth.
What are the Advancements in the Market in Latin America?
Latin America held a considerable share of the cell and gene therapy clinical trials market in 2025, supported by rising chronic and genetic disease prevalence and government efforts to strengthen research infrastructure. Countries such as Brazil, Mexico, Chile, and Colombia are increasing participation in oncology and regenerative medicine studies to strengthen regional capabilities in healthcare. The diverse patient population and lower operational costs make the region suitable for the conduct of clinical trials.
Brazil Market Trends
Brazil accounts for the largest share of the Latin American cell and gene therapy clinical trials market in 2025, due to its large population and expanding healthcare infrastructure. The country's regulatory body – ANVISA provides clear regulations and approval pathways for Advanced Therapy Medicinal Products (ATMPs). This encourages researchers and pharmaceutical companies to explore advanced therapies and clinical trials. The growing investment from public and private funds supports local manufacturing and trial execution. The large population also supports broader clinical trial recruitment.
What are the Key Trends in the Market in the Middle East and Africa Region?
The Middle East & Africa held a notable share of the cell and gene therapy clinical trials market in 2025, driven by expanding hospital infrastructure, biotechnology investment, and healthcare modernization. Countries such as Saudi Arabia, the UAE, and South Africa are expanding access to advanced therapies through partnerships with global healthcare companies. However, high treatment costs and limited manufacturing capabilities remain major challenges in some parts of South Africa.
Saudi Arabia Market Trends
Saudi Arabia represents the leading market within the Middle East and Africa cell and gene therapy clinical trials market in 2025, supported by high local prevalence of genetic disorders and strong healthcare modernisation initiatives under Vision 2030. The government in the country is investing in the development of genomics, precision medicines and advanced therapy research. The Saudi Food and Drug Authority has established regulatory pathways for advanced therapy product approvals. The global healthcare collaboration further contributes to the market growth.
Competitive Landscape
The cell and gene therapy clinical trials market is highly competitive, with global pharmaceutical companies, biotechnology firms and contract research organisations. The leading companies in the market include IQVIA, ICON plc, LabCorp, Charles River Laboratories, Syneos Health, Thermo Fisher Scientific, Inc., Novotech, PAREXEL International Corp and Medpace. Companies are strengthening their market position by integrating trial management and global clinical networks. Strategic partnerships, collaboration, mergers and acquisitions with biotechnology and pharmaceutical companies further support long-term market presence.
For future growth in the cell and gene therapy clinical trials market, companies should invest in scalable manufacturing, integration of AI in trial management and strong regulatory collaborations.
Top Companies in the Cell and Gene Therapy Clinical Trials Market and Their Offerings
- IQVIA - A United States based one of the world's largest clinical research organisations. It offers clinical trial services including trial design, patient recruitment, regulatory compliance and advanced data analytics.
- ICON Plc - An Ireland based leading global CRO with experience in cell and gene therapy studies. It provides Phase I to Phase IV trial management, site optimization, and decentralised trials.
- Parexel - A United States based company that specialises in advanced therapy clinical trials for biotechnology and pharmaceutical companies. It offers oncology and rare disease trial management, patient recruitment and regulatory compliance.
- Thermo Fisher Scientific - A United States based company that offers clinical trial management, decentralized trials, and manufacturing services for cell and gene therapies.
- Charles River Laboratories - A United States based company associated with early phase trial conduction. It offers preclinical research, safety assessment, and CDMO services.
Cell and Gene Therapy Clinical Trials Market Companies

- IQVIA
- ICON Plc
- Laboratory Corporation of America Holdings
- Charles River Laboratories International, Inc.
- PAREXEL International Corp.
- Syneos Health
- Medpace Holdings, Inc.
- PPD Inc.
- Novotech
- Veristat, LLC
Recent Developments
- In September 2025, MaxisIT, a leading provider of clinical data analytics platforms, launched Maxis AI is agentic AI platform that transforms clinical trials in pharmaceutical and life science.
- In July 2026, according to WCG reports, 92% of clinical trial organisations are planning to invest in artificial intelligence to improve workflows and reduce operational costs.
- In July 2026, Bio Rad Laboratories, Inc., a global leader in life science research and clinical diagnostics products, launched the QX700 System compatible Vericheck ddPCR Kit for critical quality control 9QC) workflows in advanced cell and gene therapy development.
- In January 2020, Charles River Laboratory paid USD 380 million in cash to purchase HemaCare Corp., a significant producer of human-derived cellular goods for the cell therapy market.
- Labcorp and Xcell Biosciences partnered in April 2022 to help the latter create CGTs for the treatment of cancer, Parkinson's disease, and other rare illnesses.
Segments Covered in the Report:
By Phase
- Phase I
- Phase II
- Phase III
- Phase IV
By Indication
- Oncology
- Cardiology
- CNS
- Musculoskeletal
- Infectious Diseases
- Dermatology
- Endocrine, Metabolic, Genetic
- Immunology & Inflammation
- Ophthalmology
- Hematology
- Gastroenterology
- Others
By Geography
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
