



Esophageal Cancer Market Size, Trends, Segmentation, Regional Outlook, and Forecast 2026-2035
Esophageal Cancer Market (By Cancer Type: Adenocarcinoma, Squamous Cell Carcinoma, Others (e.g., small cell carcinoma); By Diagnosis: Endoscopy, Biopsy, Barium Swallow (Esophagram), Imaging (CT, PET, MRI), Esophageal Manometry, Blood Tests; By Treatment: Therapy Type, Drug Class; By Stage: Stage 0 (Carcinoma in situ), Stage I, Stage II, Stage III, Stage IV (Metastatic); By Route of Administration: Oral, Intravenous, Others; By End User: Hospitals, Specialty Cancer Centers, Academic & Research Institutes, Ambulatory Surgical Centers (ASCs), Homecare Settings; By Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies) - Global Industry Analysis, Size, Trends, Leading Companies, Regional Outlook, and Forecast 2026 to 2035
Source: https://www.precedenceresearch.com/esophageal-cancer-market
 Get a Sample
 Table Of Content


What is the Esophageal Cancer Market Size?
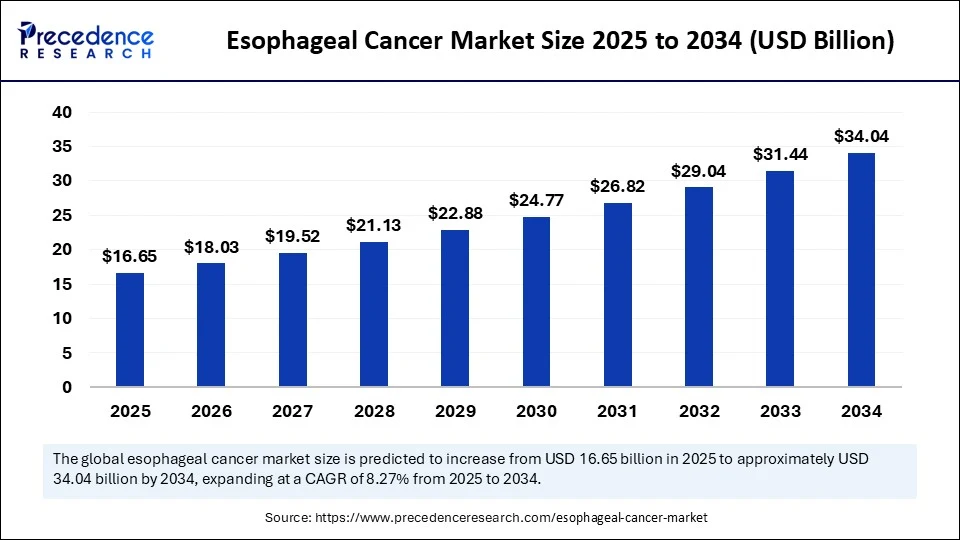
The global esophageal cancer market size is predicted to increase from USD 18.03 billion in 2026 to approximately USD 36.51 billion by 2035, expanding at a CAGR of 8.17% from 2026 to 2035. The growth of the esophageal cancer market is driven by increasing disease prevalence around the world, an aging population, the development of advanced diagnostic tools, and demand for targeted therapies.
Esophageal Cancer Market Key Takeaways
- In terms of revenue, the global esophageal cancer market was valued at USD 18.03 billion in 2026.
- It is projected to reach USD 36.51 billion by 2035.
- The market is expected to grow at a CAGR of 8.17% from 2026 to 2035.
- North America dominated the esophageal cancer market with the largest market share of 40% in 2026.
- Asia Pacific is expected to witness the fastest growth during the forecast years.
- By cancer type, the squamous cell carcinoma segment led the market with the biggest market share of 80% in 2026.
- By cancer type, the adenocarcinoma segment is anticipated to show considerable growth over the forecast period.
- By diagnosis, the endoscopy segment held the significant market share of 40% in 2026.
- By diagnosis, the imaging segment is anticipated to show considerable growth over the forecast period.
- By treatment, the therapy type segment generated the highest market share of 60% in 2026.
- By stage, the stage II segment captured the remarkable market share of 35% in 2026.
- By route of administration, the intravenous segment contributed the biggest market share of 85% in 2026.
- By route of administration, the oral segment is anticipated to show notable growth during the forecast period.
- By end user, the hospitals segment accounted for major market share of 70% in 2026.
- By end user, the ambulatory surgical centers segment is anticipated to show considerable growth over the forecast period.
- By distribution channel, the hospital pharmacies segment led the market with a biggest market share 60% in 2026.
- By distribution channel, the online pharmacies segment is anticipated to show considerable growth over the forecast period.
Market Overview
The esophageal cancer Market refers to the global ecosystem of products, services, technologies, and stakeholders involved in the diagnosis, treatment, and management of esophageal cancer, a malignancy affecting the esophagus. This market encompasses pharmaceuticals (chemotherapy, targeted therapy, and immunotherapy), diagnostics (biopsies, imaging), surgical and non-surgical treatments, and supportive care. The growth of this market is driven by increasing incidence rates, advancements in targeted therapies and immuno-oncology, and evolving diagnostic technologies.
The market is expected to grow as demand for esophageal cancer diagnosis and treatment evolves alongside advances in diagnostic technologies and therapies. Factors like an aging population, smoking, alcohol consumption, obesity, and Barrett's esophagus contribute to this growth. Increased investment in cancer research by pharmaceutical companies and healthcare expansion in new markets further improve treatment access and drive market growth.
How is AI Transforming the Diagnosis of Esophageal Cancer?
Artificial intelligence is transforming the esophageal cancer market by improving identification and management. AI analyzes vast data, including medical history and imaging results, to identify high-risk individuals. AI-assisted systems detect anomalies, like precancerous lesions, with greater accuracy, enabling earlier treatment and improved outcomes. Moreover, AI accelerates the drug discovery process by identifying potential drug targets, predicting drug efficacy, and optimizing clinical trial designs. This reduces the time and cost associated with bringing new therapies to market, expanding treatment options.
What Factors are Fueling the Growth of the Esophageal Cancer Market?
- Aging population and Increase in Incidence: The market is growing substantially due to rising global incidence of esophageal cancer, particularly among the aging population. Increased patient numbers and risk factors like smoking, alcohol use, and poor diet boost demand for diagnostics, therapies, and advanced treatments in both developed and developing healthcare sectors.
- Targeted Therapies and Immunotherapies Development: The development of newer, more personalized medicines is transforming the esophageal cancer treatment approaches with targeted therapies and immunotherapies such as the PD-1/PD-L1 inhibitors. Expanding treatment options leads to increased adoption and investment in novel treatments. New FDA approvals for esophageal cancer treatments and ongoing clinical trials may expand treatment options; cite the relevant FDA approvals and trial records.
- Rising Health Awareness and Screening Strategies: Public health initiatives may improve awareness and encourage timely evaluation of symptoms and risk factors; cite specific programs where their impact on diagnosis has been measured. Symptom-specific and risk factor-specific campaigns are increasing diagnosis rates.
Market Dynamics
Drivers
Growing Disease Incidence and Improved Treatment Accessibility
The prevalence of esophageal cancer has increased worldwide, driven by several risk factors, which include smoking, excessive drinking, poor diet, and the widespread occurrence of gastroesophageal reflux disease (GERD). According to the National Agency for Research on Cancer, in 2020 there were estimated to be about 604,000 new cases of esophageal cancer and about 544,000 deaths from esophageal cancer globally, with large variations in incidence and mortality across world regions. The highest incidence rates were observed in Eastern Asia and Southern and Eastern Africa. This significantly prompted the need for better screening and action strategies. Since people have become more aware of the importance and benefits of early diagnosis, there is an increasing investment in this area. Governments and healthcare organizations around the world are responding by implementing endoscopic screening programs and improved diagnostic technology. The increased need for early diagnosis leads to the demand for new diagnostic methods and less invasive procedures, boosting the growth of the market. (Source: https://www.iarc.who.int)
Restraint
High Treatment Costs and Limited Access to Early Diagnosis
The high costs associated with novel treatments, especially immunotherapies and biologics, are major factors restraining the growth of the esophageal cancer market. These treatments are costly, creating barriers for potential patients particularly in low- and middle-income countries. The economic factor is a major obstacle for pharmaceutical companies and healthcare providers. Limited early screening and diagnostic programs, especially in rural and underserved areas, also restrain the market. The lack of early diagnosis leads to later-stage diagnoses, reducing treatment effectiveness and survival rates. Moreover, the complexity of esophageal cancer treatment, requiring multidisciplinary approaches and specialized expertise, poses challenges for healthcare providers.
Opportunity
Enhanced Convenience through Advanced Diagnostic and Treatment Technologies
A major opportunity for the esophageal cancer market lies in the rapid advancements in diagnostic technologies, contributing to early diagnosis and patient comfort. Advanced endoscopic techniques and biomarker-based tests may support the detection and assessment of esophageal cancer; cite validated applications where early-detection benefits have been demonstrated. Prompt diagnosis improves treatment outcomes and patient survival. A combined diagnostic stage evaluates tumor location, condition stage, and molecular features, aiding in treatment selection and personalized medicine. In addition, the rising development of personalized medicine creates immense opportunities in the market. Developing personalized medicine approaches, including biomarker-driven therapies and tailored treatment plans, can improve treatment efficacy and patient outcomes.
Segments Insights
Cancer Type Insights
Why Did the Squamous Cell Carcinoma Segment Dominate the Esophageal Cancer Market in 2026?
The squamous cell carcinoma segment dominated the market with a 80% share in 2026. Squamous cell carcinoma (SCC) develops in the squamous cells that line the upper and middle esophagus and is closely associated with the risk factors like tobacco consumption, excessive consumption of alcohol, and nutritional deficiencies. SCC is often diagnosed at the late stage due to atypical early symptoms, leading to a poor prognosis and a need for effective treatments. Ongoing research targeting SCC-specific pathways and novel treatment modalities drives investment and segmental expansion.
The adenocarcinoma segment is expected to grow at the fastest CAGR over the forecast period. Adenocarcinoma of the esophagus typically develops in the glandular cells of the lower esophagus, at the junction with the stomach, and is largely connected to risk factors such as obesity, gastroesophageal reflux disease, and Barrett's esophagus, a known precursor disorder. Obesity, gastroesophageal reflux disease, and Barrett's esophagus are established risk factors for esophageal adenocarcinoma. The rising development of novel detection tools, including screening for Barrett's esophagus, is leading to increased diagnostic rates. This significantly increases the demand for more effective and accurate therapies, including immunotherapies and molecularly targeted drugs.
Diagnosis Insights
How Does the Endoscopy Segment Dominate the Market in 2026?
The endoscopy segment dominated the esophageal cancer market with a 40% share in 2026. Upper gastrointestinal endoscopy with biopsy is a key method for diagnosing esophageal cancer. Besides diagnosis, endoscopy is also used for treatment, including endoscopic mucosal resection (EMR) and ablation techniques, increasingly used to treat early-stage esophageal cancer and precancerous lesions like Barrett's esophagus. Due to increased awareness and screening programs for esophageal cancer, the demand for endoscopic procedures is projected to remain high, continuing its dominance in the market.
The imaging (CT, PET, MRI) segment is expected to grow at the highest CAGR during the projection period. The growth of the segment is attributed to the increasing need for early disease detection. In esophageal cancer, imaging modalities are crucial for staging, treatment planning, and monitoring treatment response. CT scans provide detailed cross-sectional views of the chest and abdomen, allowing for measurements of tumor size, local infiltration, and lymph node involvement. PET scans are valuable for detecting metabolically active cancer cells, which aids in identifying distant metastases and guiding treatment decisions. Ongoing advancements in imaging technology are enhancing diagnostic accuracy.
Treatment Insights
What Made Therapy Type the Most Preferred Approach for Esophageal Cancer Treatment?
The therapy-type segment accounted for a reported 60% share in 2026. Chemotherapy, radiation therapy, and combined chemoradiation are among the treatment approaches used for esophageal cancer. Therapeutic approaches are tailored to the cancer stage, histological subtype (adenocarcinoma or squamous cell carcinoma), and the patient's overall condition. They are also applied in cases of recurrence or metastatic diseases when conventional treatments are less effective. The development of new agents and combination regimens is increasing, which can address unmet medical needs. In addition, the rising demand for targeted therapies is likely to ensure the long-term growth of the market.
Stage Insights
Why Did the Stage II Segment Dominate the Market in 2026?
The stage II segment led the market with a 35% share in 2026. Stage II esophageal cancer is defined by the applicable TNM staging criteria, which consider tumor invasion, regional lymph-node involvement, and other clinical or pathological findings. Stage II esophageal cancer is further divided into IIA and IIB based on tumor size, lymph node involvement, and grade. Stage II disease is typically treated with chemotherapy or radiation therapy, often in combination, to reduce tumor burden and improve surgical outcomes. Early intervention in this stage leads to a better prognosis, driving the demand for effective therapeutic regimens.
Route of Administration Insights
How Did the Intravenous Segment Lead the Esophageal Cancer Market?
The intravenous (IV) segment led the market with a 85% share in 2026. The segment's share may reflect the use of intravenous chemotherapy, immunotherapy, and selected targeted therapies; cite the market data supporting this explanation. The rapid onset of action of IV therapies enhance patient outcomes. Many chemotherapy and immunotherapies are administered via IV injection, ensuring rapid and controlled entry of the medicine into the bloodstream and full distribution throughout the body. IV therapy can be used alone or with other treatments like surgery and radiation, forming part of multimodal therapy. It offers a clinical advantage due to the controlled medication dosage and the ability to use drugs that cannot be taken orally, especially for aggressive or end-stage cancers.
The oral segment is expected to grow at the fastest rate during the forecast period. Oral medications, particularly targeted therapies and chemotherapeutic agents, offer patients the convenience of self-administration at home. This is especially appealing in maintenance therapy and early cancer management, where intermittent treatment over a long period is needed. Advancements in pharmaceutical innovation have led to the development of more effective oral medications with higher bioavailability and tolerability, increasing their use in esophageal cancer treatment.
End User Insights
What Made Hospitals the Prominent End-user?
The hospitals segment dominated the esophageal cancer market with a 70% share in 2026. Hospitals are equipped with multidisciplinary oncology care, advanced technology, and the resources to manage complex cases and provide treatment across different stages of the disease. They facilitate advanced surgeries like esophagectomies, which often require close post-operative care, solidifying their role as primary treatment centers. Hospitals also conduct clinical research and trials, fostering innovations in esophageal cancer treatment.
The ambulatory surgical centers segment is expected to grow at a significant rate in the upcoming period. The growth of the segment is attributed to the increasing demand for cost-effective treatments. ASCs offer a convenient and less expensive option for treating esophageal cancer, especially in its early stages and for precancerous lesions like Barrett's esophagus. Selected endoscopic procedures for early-stage disease or precancerous lesions may be performed in ambulatory settings when clinically appropriate. Esophagectomy generally requires specialized surgical facilities and postoperative inpatient care. The increasing use of advanced endoscopies and laparoscopies is expanding the range of esophageal cancer procedures safely performed in these centers.
Distribution Channel Insights
Why Did the Hospital Pharmacies Segment Dominate the Market in 2026?
The hospital pharmacies segment dominated the esophageal cancer market with a 60% share in 2026. This is mainly due to the increased patient volumes in hospitals, leading to a heightened demand for centralized purchase and distribution of expensive oncology drugs within institutional settings, such as hospitals and specialty centers. These environments offer benefits like high-quality assurance, advanced chemotherapy and targeted treatment management, and robust clinical oversight, ensuring safe and efficient medication use. Hospital pharmacies are crucial in clinical trials, managing investigational drugs and supporting the supply chain of innovative medications.
The online pharmacies segment is expected to grow at the rapid pace over the studied period. This is mainly due to the increasing need to reduce frequent hospital visits. Online pharmacies offer patients a convenient way to order prescriptions from the comfort of their homes. They provide easy access to medications, including specialty drugs, which can be crucial for cancer treatment. The rise of digital health and e-commerce has made online pharmacies more accessible and user-friendly. These pharmacies provide doorstep delivery, eliminating the need to visit physical pharmacies and attracting more patients.
Regional Insights
What Made North America the Dominant Region in the Esophageal Cancer Market in 2026?
North America registered dominance in the market with a major revenue share in 2026. This is mainly due to the increased incidence of esophageal cancer and well-established healthcare systems. There is high adoption of advanced diagnostic technologies, including high-resolution endoscopy, molecular imaging, and AI-based diagnostic tools, leading to increased diagnostic accuracy. This further prompted the need for novel therapeutics. The region has also seen improvements in early-diagnosis capabilities. The market has also been positively influenced by government initiatives that promote early cancer screening and increase disease awareness.
What is the U.S. Esophageal Cancer Market Size?
The U.S. esophageal cancer market size was exhibited at USD 5.05 billion in 2026 and is projected to be worth around USD 10.47 billion by 2035, growing at a CAGR of approximately 8.45% from 2026 to 2035.

The U.S. plays a major role in the market, holding the majority of the share in 2026. The U.S. market benefits from comprehensive insurance coverage, strong reimbursement systems, and collaborative partnerships between academia, biotech firms, and clinical trial groups. There is heightened awareness of health and wellness and improved access to superior care, supporting market growth.
Why is Asia Pacific Expected to Witness the Fastest Growth in the Esophageal Cancer Market?
Asia Pacific is expected to grow at the fastest CAGR during the forecast period. The growth of the market is supported by the expansion of oncological research infrastructure and health initiatives by governments that focus on early detection and intervention strategies. The rising healthcare policies, enhancing access to medications, and rising development of novel treatments are shaping the future of the esophageal cancer market. China is an important market within Asia Pacific, supported by its large patient population and pharmaceutical manufacturing base. There is a high availability of affordable medicines. The robust pharmaceutical manufacturing sector and rising investments in cancer research are fostering innovation in the market. With heightened awareness and international collaborations with medical institutions, there is a concurrent rise in access to more advanced diagnostic and therapeutic options.
What Opportunities Exist in the European Esophageal Cancer Market?
The European esophageal cancer market is expected to grow during the forecast period. The market within the region is expected to grow due to its well-developed healthcare systems, focusing on early screening and specialized cancer treatment. There is a rising demand for advanced treatments as a result of increased cancer burden. Moreover, increased access to innovative treatment approaches, including immunotherapies and targeted therapies, is improving treatment outcomes and expanding patient treatment choices. Germany is a major player due to its highly developed healthcare system, high diagnosis rates, and significant investments in cancer research.
Germany Market Trends
Germany's strong healthcare system offers access to advanced robotic-assisted esophagectomy, brachytherapy, and even tailored, multidisciplinary care. Substantial investment in pharmaceutical R&D for molecular diagnostics is thus introducing more personalized, high-value treatment alternatives.
How is Latin America Growing in the Esophageal Cancer Market?
Latin America is expected to show notable growth during the forecast period. The region faces a high, rising burden of disease with high mortality rates, largely because of late-stage diagnosis and limited access to specialized care. Esophageal cancer incidence varies across Latin America; cite a current IARC or national cancer-registry source for any country-level ranking, demanding tailored, localized solutions. Specific lifestyle factors, like high tobacco use and alcohol consumption, necessitate stronger prevention and even early detection programs.
Brazil Market Trends
Brazil has high incidence rates, mainly in southern regions, with a significant portion of cases associated with high alcohol and tobacco consumption. Growth is driven by advancements in esophageal stents along with minimally invasive surgical procedures.
Will the Middle East and Africa Grow in the Esophageal Cancer Market?
The Middle East and Africa region is expected to grow at a notable CAGR in the foreseeable future, driven by a combination of increasing incidence rates, high unmet clinical demands, and rapid healthcare modernization. Access to targeted therapies and immunotherapy may create market opportunities, although adoption varies across countries; cite regional treatment-access or utilization data.
UAE Market Trends
It is driven by growing lifestyle-related risk factors, advancements in targeted immunotherapies, and improved diagnostic tools such as molecular imaging. Increased adoption of endoscopic techniques and AI-driven diagnostics for earlier, more precise cancer detection also boosts the market.
Esophageal Cancer Market Companies
- AstraZeneca plc: AstraZeneca plc is offering a specialized portfolio aimed at immunotherapy for esophageal and gastric cancers, mainly for resectable early-stage and locally advanced cases.
- Eli Lilly and Company: Eli Lilly and Company markets CYRAMZA (ramucirumab), a VEGFR-2 antagonist approved for specific gastric or gastroesophageal junction adenocarcinoma settings; cite the current prescribing information and clarify its relevance to the market scope.
- Novartis AG: Novartis AG is heavily focused on the esophageal cancer industry, mainly through the development and commercialization of tislelizumab, a humanized IgG4 anti-PD-1 monoclonal antibody programmed to treat advanced or metastatic esophageal squamous cell carcinoma.
- Amgen Inc.: Amgen Inc. is actively developing targeted therapies and immunotherapies for esophageal cancer, along with the gastroesophageal junction cancer, with a strong focus on personalized medicine.
Other Companies and Organizations Mentioned
- F. Hoffmann-La Roche Ltd
- Merck & Co., Inc.
- Bristol-Myers Squibb Company
- Pfizer Inc.
- Johnson & Johnson (Janssen Biotech)
- Daiichi Sankyo Company, Limited
- GlaxoSmithKline plc (GSK)
- Bayer AG
- AbbVie Inc.
- Takeda Pharmaceutical Company Limited
- Illumina, Inc. (diagnostics)
- Thermo Fisher Scientific Inc. (diagnostics)
Recent Developments
- In June 2025, Tevimbra (tislelizumab), a drug therapy of lung and esophageal cancer, a product of immuno-oncology treatment of Glenmark Pharmaceuticals Ltd, a research based and a global pharmaceutical company based in India was launched when the drug got approval by the Central Drugs Standard Control Organization (CDSCO).
- In June 2025, Lucid Diagnostics Inc., a cancer prevention medical diagnostics firm at the commercial-stage and a fully owned subsidiary of PAVmed Inc., stated that Hoag has been granted a program of esophageal precancer integration that integrates the care areas like diagnostics, treatment, education, and prevention.
Esophageal Cancer Market Segments
By Cancer Type
- Adenocarcinoma
- Squamous Cell Carcinoma
- Others (e.g., small cell carcinoma)
By Diagnosis
- Endoscopy
- Biopsy
- Barium Swallow (Esophagram)
- Imaging (CT, PET, MRI)
- Esophageal Manometry
- Blood Tests
By Treatment
- Therapy Type
- Chemotherapy
- Radiation Therapy
- Targeted Therapy
- Immunotherapy (e.g., checkpoint inhibitors)
- Surgery
- Endoscopic Treatments (e.g., mucosal resection)
- Palliative Care
- Drug Class
- PD-1/PD-L1 Inhibitors
- HER2 Inhibitors
- VEGF Inhibitors
- Cytotoxic Agents
- Tyrosine Kinase Inhibitors (TKIs)
- Antimetabolites
- Others
By Stage
- Stage 0 (Carcinoma in situ)
- Stage I
- Stage II
- Stage III
- Stage IV (Metastatic)
By Route of Administration
- Oral
- Intravenous
- Others
By End User
- Hospitals
- Specialty Cancer Centers
- Academic & Research Institutes
- Ambulatory Surgical Centers (ASCs)
- Homecare Settings
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- Europe
- Asia Pacific
- MEA
- South America
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
