
Europe Phase 3 Clinical Trials Market Size, Key Companies, Company Production Capacity, Healthcare Infrastructure Growth, Product Utilization, Regulatory Compliance, Company Expansion Strategies, Company Investment Strategies, and Market Outlook
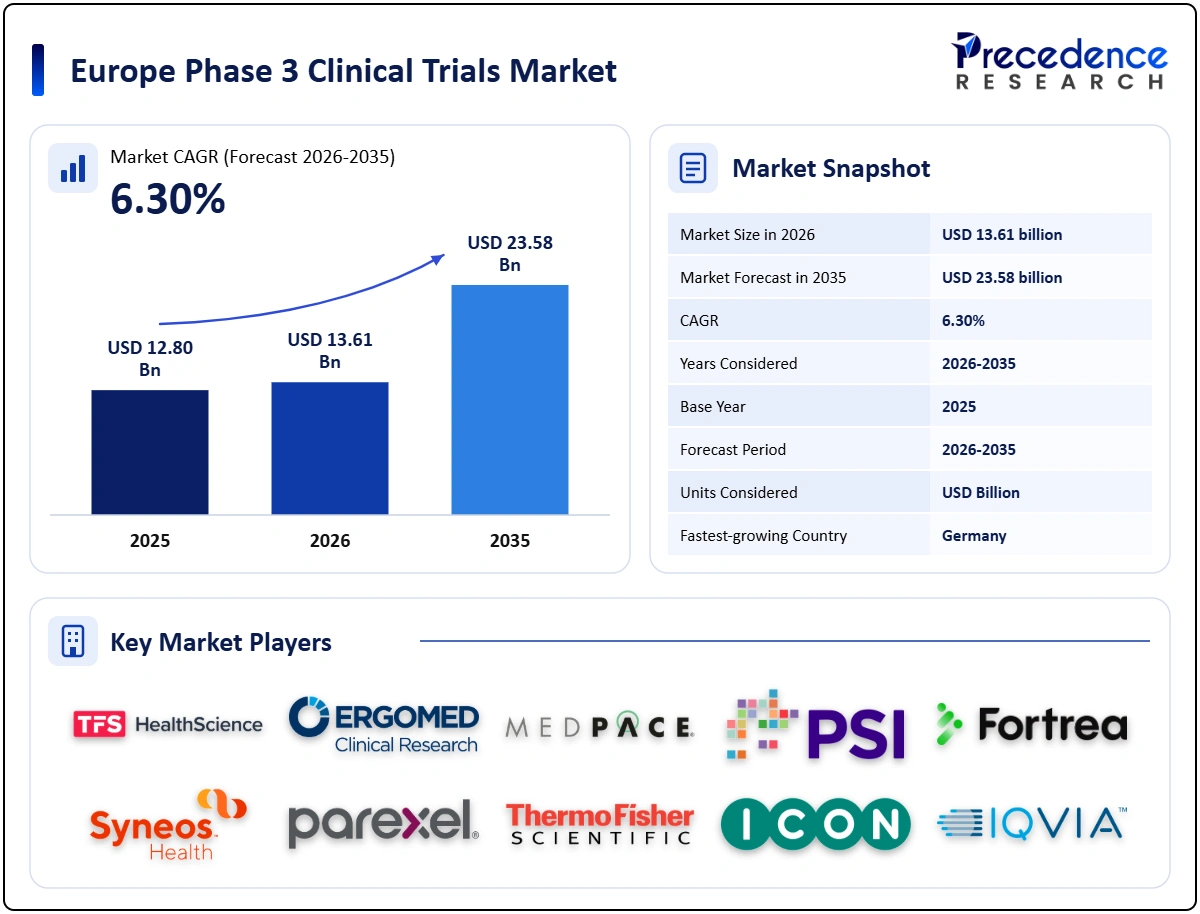
Payal Rabde, a Healthcare Industry Expert, highlights that the Europe Phase 3 clinical trials market has reached USD 13.61 billion in 2026 and is on track to reach USD 23.58 billion by 2035, advancing at a CAGR of 6.30%. Key Europe Phase 3 clinical trials market companies shaping the market include IQVIA, ICON, Parexel while major growth segments span indication, sponsor, service type, trial model.
Source: https://www.precedenceresearch.com/europe-phase-3-clinical-trials-market
 Get a Sample
 Report Description
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 12.80 billion
- Estimated market size in 2026: USD 13.61 billion
- Projected market size by 2035: USD 23.58 billion
- CAGR (2026-2035): 6.30%
Regional Market Insights
- Germany dominated the market with an 18.20% share and was valued at USD 2.33 billion in 2025.
- U.K. accounted for 15.60% of the market share and reached USD 2.00 billion in 2025.
- Spain held a 12.60% share, reaching USD 1.61 billion in 2025 and is projected to be the fastest-growing country, at a CAGR of 7.11% from 2026 to 2035.
Segmental Highlights
- By indication, the oncology segment accounted for 30.40% market share, with a market size of USD 3.89 billion in 2025.
- By sponsor, pharmaceutical companies contributed a 62.40% share and generated USD 7.99 billion in 2025.
- By service type, site management & monitoring held a 38.60% share and reached USD 4.94 billion in 2025.
- By trial model, traditional site-based captured 71.40% (USD 9.14 billion) of the market share in 2025.
Europe Phase 3 Clinical Trials Market Size and Forecast, 2025-2035 (USD Billion)
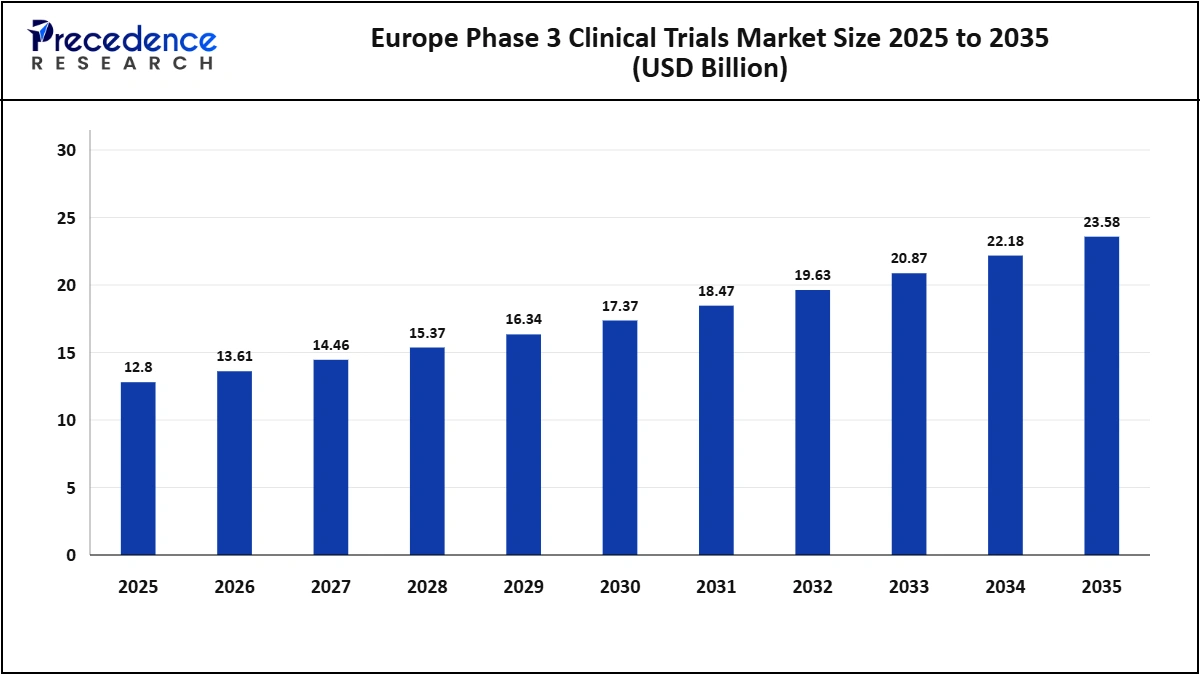
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The Europe Phase 3 clinical trials market was valued at USD 12.80 billion in 2025. It is estimated to reach USD 23.58 billion by 2035 because Phase 3 trials are the most expensive stage of drug development, and large late-stage pipelines in obesity, oncology, and immunology keep spending in Europe rising. Large cardiometabolic outcome trials, oncology combination studies, CRO outsourcing, decentralized trial technologies, and higher per-patient costs support steady growth, moderated by biotech funding cycles and efforts to make trials more efficient, lifting the market to USD 17.37 billion by 2030 and sustaining a CAGR of 6.30% during 2026 to 2035.
Analyst View: Europe's Phase 3 clinical trials market is set for steady growth, supported by strong late-stage drug pipelines in oncology, obesity, and immunology. Rising trial complexity, CRO outsourcing, and adoption of decentralized technologies are creating new spending opportunities. However, funding uncertainty and pressure to improve trial efficiency may temper growth. The growth rate is based on evidence from pipeline and regulatory trends, moderated by efforts to control trial costs.
Market Trends
- Risk-based monitoring is gaining traction as sponsors adopt ICH E6(R3) guidelines to improve trial quality.
- Hybrid and decentralized trial models are becoming more common, offering greater flexibility and convenience for patients.
- AI-assisted tools are helping sponsors improve clinical trial site selection.
- Large cardiometabolic outcome trials are driving demand for extensive patient enrolment and long-term clinical data collection.
- Biotech-sponsored late-stage development programs are creating new opportunities for Phase 3 trial service providers.
Drivers, Restraints, and Opportunities
Driver
The market is benefiting from large late-stage drug development pipelines, particularly in obesity and cardiometabolic diseases, where trials often require extensive patient enrolment. Additionally, oncology combination therapies are increasing the number and complexity of studies, while sponsors are increasingly outsourcing trial activities to CROs to manage costs and operational demands.
Restraint
Phase 3 trials remain expensive and time-consuming, with patient recruitment challenges often delaying study completion. These pressures are further compounded by cyclical biotech funding, shortages of skilled site staff, and regulatory complexity across European markets, making trial execution more difficult.
Opportunity
These challenges are creating opportunities for more efficient trial approaches, including decentralized elements that improve patient access and AI-powered tools that support recruitment. Additionally, adaptive trial designs can help control costs, while broader patient diversity can expand site networks, and real-world data can strengthen clinical trial planning.
Market Segmentation: 2025 Share and Size
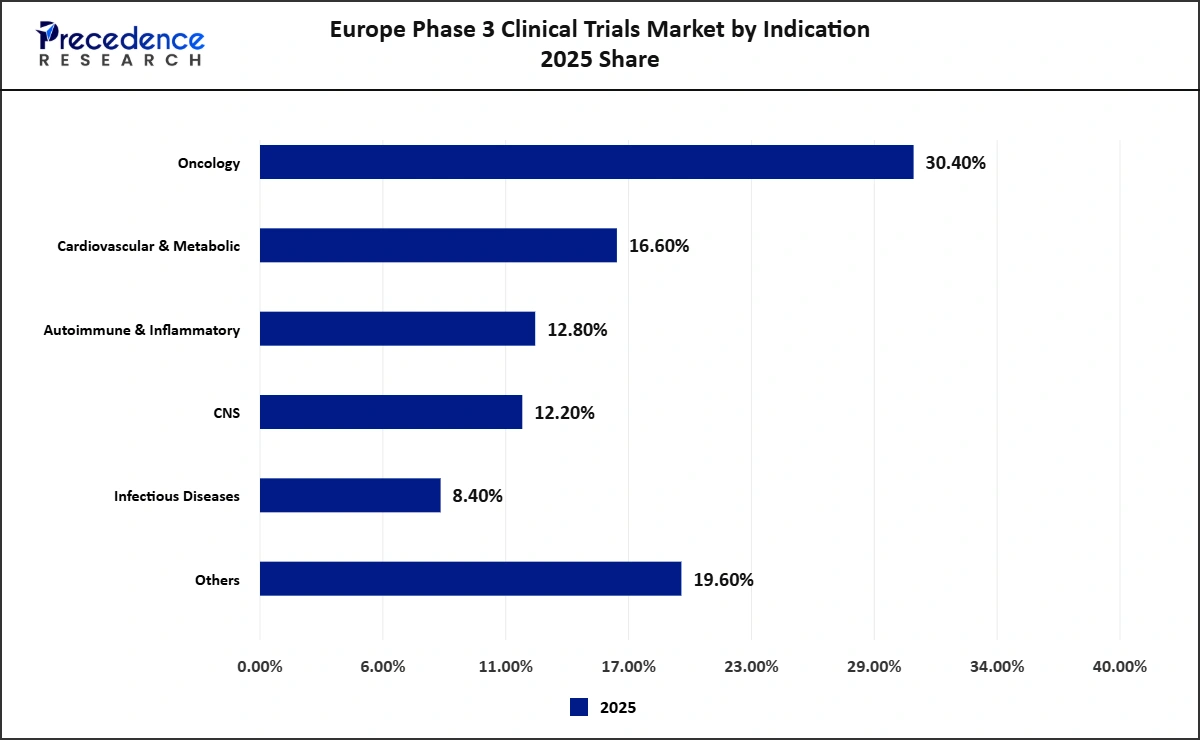
Europe Phase 3 Clinical Trials Market by Indication 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Oncology dominates with 30.40% share and reached USD 3.89 billion in 2025, cardiovascular & metabolic for 16.60% (USD 2.12 billion), autoimmune & inflammatory for 12.80% (USD 1.64 billion), CNS for 12.20% (USD 1.56 billion), infectious diseases for 8.40% (USD 1.08 billion), and others for 19.60% (USD 2.51 billion).
Oncology: In 2025, this segment held a 30.40% share of the market, valued at USD 3.89 billion. It is expected to grow to USD 6.81 billion by 2035, registering a CAGR of 5.76% during 2026 to 2035. Oncology is the largest indication because cancer drugs dominate late-stage pipelines, including immunotherapy combinations, antibody-drug conjugates, and targeted therapies, and oncology studies require long follow-up, imaging, and biomarker testing.
Cardiovascular & Metabolic: The market size of this segment was valued at USD 2.12 billion in 2025 and is projected to reach USD 4.44 billion by 2035, at a CAGR of 7.66%. Cardiovascular & metabolic studies, including obesity, diabetes, heart failure, and kidney disease outcome trials, are the fastest-growing indication because incretin and other cardiometabolic drugs require very large, long trials and post-approval outcome evidence.
Autoimmune & Inflammatory: This segment accounted for 12.80% market share and reached USD 1.64 billion in 2025. It is expected to rise to USD 2.98 billion by 2035, exhibiting a CAGR of 6.16% during the forecast period. Autoimmune & inflammatory studies cover rheumatoid arthritis, inflammatory bowel disease, psoriasis, atopic dermatitis, and lupus, with many new biologics and oral drugs in development.
CNS: The CNS segment was valued at USD 1.56 billion in 2025, accounting for 12.20% of the market. It is projected to reach USD 2.84 billion by 2035, registering a CAGR of 6.16% over the study period. CNS clinical studies cover Alzheimer's disease, depression, schizophrenia, migraine, and pain management. These trials often require large patient populations, extended follow-up periods, and complex clinical endpoints, increasing study complexity and testing requirements.
Infectious Diseases: This segment was valued at USD 1.08 billion in 2025 and is projected to reach USD 1.95 billion by 2035, growing at a CAGR of 6.16% over the forecast period. Infectious disease studies include vaccines, antivirals, and antibiotics, where large vaccine trials can involve tens of thousands of participants.
Others: The Others segment held a 19.60% share and generated USD 2.51 billion in 2025 and is projected to reach USD 4.56 billion by 2035, registering a CAGR of 6.16% from 2026 to 2035. Others include respiratory, renal, ophthalmology, dermatology, women's health, and rare disease studies.
Europe Phase 3 Clinical Trials Market by Sponsor 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Pharmaceutical Companies | 62.40% | 7.99 | 14.02 | 5.78% |
| Biotechnology Companies | 28.60% | 3.66 | 7.46 | 7.38% |
| Medical Device & Others | 9.00% | 1.15 | 2.10 | 6.18% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Pharmaceutical Companies accounted for a 62.40% share and generated USD 7.99 billion in 2025. Biotechnology companies held a 28.60% share (USD 3.66 billion), and medical device and others contributed a 9.00% share (USD 1.15 billion) in 2025.
Pharmaceutical Companies: The segment dominated the market in 2025, accounting for 62.40% of total revenue, valued at USD 7.99 billion. It is projected to reach USD 14.02 billion by 2035, registering a CAGR of 5.78% from 2026 to 2035. Pharmaceutical companies represent the largest clinical trial sponsors, managing large-scale global development programmes and outsourcing a substantial share of clinical research activities to contract research organizations (CROs).
Biotechnology Companies: The segment accounted for 28.60% of the market in 2025, valued at USD 3.66 billion. It is projected to reach USD 7.46 billion by 2035, registering a CAGR of 7.38% from 2026 to 2035. Biotechnology companies represent the fastest-growing sponsor segment, driven by the increasing number of late-stage drug candidates originating from biotech firms and their strong reliance on full-service contract research organizations (CROs) for clinical development and trial management.
Medical Device & Others: This segment accounted for 9.00% (USD 1.15 billion) in 2025 and is estimated to reach USD 2.10 billion by 2035, expanding at a CAGR of 6.18% over the forecast period. Medical device companies and others, including academic and government sponsors, run pivotal and post-market device studies and investigator-initiated trials.
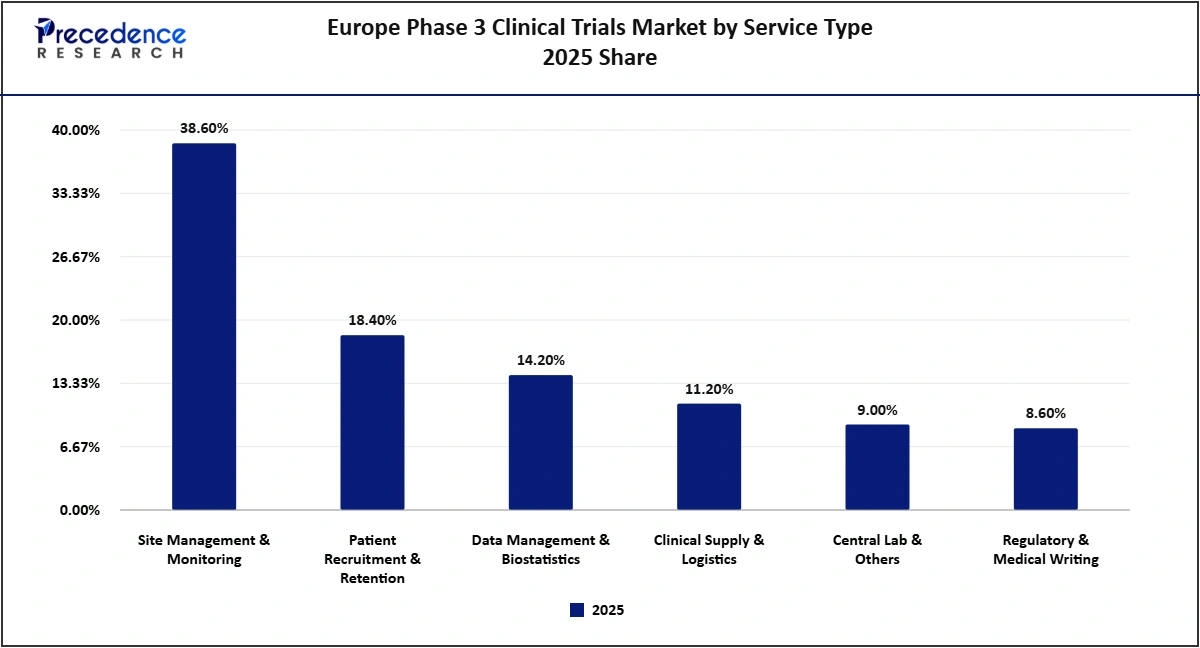
Europe Phase 3 Clinical Trials Market by Service Type 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Site Management & Monitoring accounted for 38.60% (USD 4.94 billion) in 2025, patient recruitment & retention for 18.40% (USD 2.36 billion), data management & biostatistics for 14.20% (USD 1.82 billion), clinical supply & logistics for 11.20% (USD 1.43 billion), central lab & others for 9.00% (USD 1.15 billion) and regulatory & medical writing for 8.60% (USD 1.10 billion).
Site Management & Monitoring: This segment accounted for a 38.60% share and was valued at USD 4.94 billion in 2025. It is expected to reach USD 8.65 billion by 2035, at a CAGR of 5.76% from 2026 to 2035. Site management & monitoring is the largest service, covering site selection, activation, investigator payments, and on-site and risk-based monitoring.
Patient Recruitment & Retention: The segment reached USD 2.36 billion in 2025 and is projected to grow to USD 4.93 billion by 2035, exhibiting a CAGR of 7.66% over the forecast period. Patient recruitment & retention is the fastest-growing service because enrolment is the main cause of delays, and sponsors use digital outreach, AI-based site selection, and patient support to speed it up.
Data Management & Biostatistics: The segment was valued at USD 1.82 billion in 2025, accounting for 14.20% of the market. It is projected to reach USD 3.30 billion by 2035, registering a CAGR of 6.16% from 2026 to 2035. Key services include electronic data capture (EDC), clinical data cleaning, statistical analysis, and reporting to support clinical trial execution and regulatory submissions.
Clinical Supply & Logistics: The market size of this segment reached USD 1.43 billion in 2025 and is estimated to reach USD 2.61 billion by 2035, expanding at a CAGR of 6.16% from 2026 to 2035. Clinical supply & logistics include manufacturing, packaging, labelling, and distribution of investigational products, including temperature-controlled supply.
Central Lab & Others: This segment accounted for 9.00% (USD 1.15 billion) in 2025 and is projected to reach USD 2.09 billion by 2035, expanding at a CAGR of 6.16% over the forecast period. Central laboratory & other services include central lab testing, imaging reading, and biomarker analysis.
Regulatory & Medical Writing: In 2025, this segment held an 8.60% share of the Europe Phase 3 clinical trials market, valued at USD 1.10 billion. It is expected to grow to USD 2.00 billion by 2035, registering a CAGR of 6.16% during the forecast period. Regulatory and medical writing include protocols, clinical study reports, and regulatory submissions.
Europe Phase 3 Clinical Trials Market by Trial Model 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Traditional Site-Based | 71.40% | 9.14 | 15.70 | 5.56% |
| Hybrid & Decentralized | 28.60% | 3.66 | 7.88 | 7.96% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Traditional site-based accounted for 71.40% (USD 9.14 billion), and hybrid & decentralized for 28.60% (USD 3.66 billion) in 2025.
Traditional Site-Based: The segment dominates the market with a 71.40% share and reached USD 9.14 billion in 2025 and is estimated to reach USD 15.70 billion by 2035, growing at a CAGR of 5.56% from 2026 to 2035. Traditional site-based trials remain dominant because most Phase 3 procedures require in-person visits at hospitals and clinics.
Hybrid & Decentralized Trials: The segment accounted for 28.60% of the market in 2025, valued at USD 3.66 billion. It is projected to reach USD 7.88 billion by 2035, registering a CAGR of 7.96% during the forecast period. These trials combine remote visits, home nursing, electronic informed consent (eConsent), and wearable devices to support clinical study participation outside traditional trial sites. They represent the fastest-growing trial model, driven by improved patient access, greater participation flexibility, and higher patient retention.
Analyst View: The Europe Phase 3 clinical trials market is driven by oncology studies and pharmaceutical organization sponsorship, reflecting strong late-stage drug pipelines and continued demand for complex clinical research. Meanwhile, patient recruitment and retention are gaining importance as sponsors seek to reduce enrolment delays, while hybrid and decentralized trial models are expanding access and improving patient participation. Overall, CRO outsourcing, growing biotech pipelines, and the adoption of technology-enabled trial models will remain key factors shaping the market growth.
Country Analysis
Europe Phase 3 Clinical Trials Market by Country 2025 Share & Size
| Country | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026-2035 |
| Germany | 18.20% | 2.33 | 4.30 | 6.31% |
| U.K. | 15.60% | 2.00 | 3.68 | 6.31% |
| France | 13.40% | 1.72 | 3.16 | 6.31% |
| Spain | 12.60% | 1.61 | 3.21 | 7.11% |
| Italy | 10.80% | 1.38 | 2.55 | 6.31% |
| Rest of Europe | 29.40% | 3.76 | 6.68 | 5.91% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Germany accounted for 18.20% (USD 2.33 billion) in 2025, the U.K. for 15.60% (USD 2.00 billion), France for 13.40% (USD 1.72 billion), Spain for 12.60% (USD 1.61 billion), Italy for 10.80% (USD 1.38 billion), and the rest of Europe for 29.40% (USD 3.76 billion).
Germany: Germany led the European market with an 18.20% share in 2025, generating USD 2.33 billion in revenue. The market is projected to reach USD 4.30 billion by 2035, registering a CAGR of 6.31% from 2026 to 2035. Germany's strong clinical research infrastructure, extensive network of trial sites, established university hospitals, and broad therapeutic expertise support its leading position in multinational clinical trials.
U.K.: Accounting for a 15.60% share in 2025, this country generated USD 2.00 billion in revenue. Continued growth is expected to take its market value to USD 3.68 billion by 2035, reflecting a CAGR of 6.31% over the forecast period. The U.K. has strong NHS research networks, the MHRA's faster approval pathways, and investments such as a Health Data Research Service announced in 2025, supporting trial activity outside the EU framework.
France: The French market was valued at USD 1.72 billion in 2025 and is projected to reach USD 3.16 billion by 2035, registering a CAGR of 6.31% from 2026 to 2035. Strong oncology and rare disease research networks, supported by national initiatives to accelerate clinical trial approvals, strengthen France's position in the European clinical research market.
Spain: This country contributed 12.60% market share and reached USD 1.61 billion in 2025 and is projected to grow to USD 3.21 billion by 2035, expanding at a CAGR of 7.11% during the forecast period. Spain is the fastest-growing country because of fast start-up times, efficient ethics approvals, high recruitment rates, and strong oncology networks, making it a preferred country for multinational studies.
Italy: The Italian market was valued at USD 1.38 billion in 2025 and is projected to reach USD 2.55 billion by 2035, registering a CAGR of 6.31% from 2026 to 2035. Italy's extensive hospital network, increasing clinical trial activity, and reforms to ethics committee processes support market expansion and strengthen the country's clinical research infrastructure.
Rest of Europe: The region captured 29.40% of the market share and reached USD 3.76 billion in 2025 and is projected to rise to USD 6.68 billion by 2035, at a CAGR of 5.91% over the forecast period. The rest of Europe includes Poland, the Netherlands, Belgium, the Nordic countries, and Central and Eastern Europe, which offer fast recruitment and lower costs.
Analyst View: Germany leads the European Phase 3 clinical trials market, supported by its strong hospital network, established research infrastructure, and broad therapeutic expertise. The U.K. and France remain important markets due to their well-developed clinical research ecosystems. Meanwhile, Spain is emerging as a key growth market, benefiting from faster trial approvals and efficient patient recruitment. Growing trial activity across the European countries further strengthens the region's overall market potential.
Competitive Landscape
Top 10 Companies in the Europe Phase 3 Clinical Trials Market
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | IQVIA | 1.50 | 11.72% | Full-service clinical development | United States |
| 2 | ICON | 1.30 | 10.16% | Full-service CRO | Ireland |
| 3 | Thermo Fisher (PPD) | 1.00 | 7.81% | PPD clinical research services | United States |
| 4 | Parexel | 0.80 | 6.25% | Full-service CRO | United States |
| 5 | Syneos Health | 0.60 | 4.69% | Biopharmaceutical solutions | United States |
| 6 | Fortrea | 0.50 | 3.91% | Clinical development services | United States |
| 7 | PSI CRO | 0.45 | 3.52% | Full-service CRO | Switzerland |
| 8 | Medpace | 0.40 | 3.12% | Biotech-focused full-service CRO | United States |
| 9 | Ergomed | 0.15 | 1.17% | Clinical research and pharmacovigilance | United Kingdom |
| 10 | TFS HealthScience | 0.12 | 0.94% | Mid-size full-service CRO | Sweden |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
IQVIA led the Europe Phase 3 clinical trials market with 11.72% share and reached USD 1.50 billion in 2025 revenue, followed by ICON at 10.16% (USD 1.30 billion) and Thermo Fisher (PPD) at 7.81% (USD 1.00 billion). IQVIA leads with the largest clinical development presence across European countries. Parexel, Syneos Health, Fortrea, PSI CRO, Medpace, Ergomed, and TFS HealthScience compete through full-service delivery, biotech focus, strong Central and Eastern European site networks, and specialized European expertise.
The top 10 companies accounted for 53.28% share (USD 6.82 billion) of 2025 revenue, while the remaining 46.72% share (USD 5.98 billion) was shared among smaller CROs, site networks, academic research organizations, and in-house sponsor teams. The Europe Phase 3 clinical trials market is moderately concentrated among large CROs, and competition centers on therapeutic expertise, site networks, recruitment speed, data and technology platforms, regulatory experience, quality, and price. Sponsors increasingly use strategic partnerships with a few full-service providers.
Companies Ecosystem
The European Phase 3 clinical trials ecosystem links sponsors with CROs, site networks, technology and data providers, central laboratories, regulators, ethics committees and patients.
| Ecosystem Stage | Role in the Market | Key Companies |
| Sponsors | Fund and design studies | Pharma, biotech and device companies |
| CROs | Run outsourced studies | IQVIA, ICON, Thermo Fisher (PPD), Parexel, Syneos Health, Medpace |
| Sites & Investigators | Enroll and treat patients | Hospitals, academic centers, site networks |
| Technology & Data | Provide EDC, eCOA, and real-world data | Medidata, Oracle, Veeva, data providers |
| Regulators & Ethics | Approve and oversee studies | FDA, EMA, national authorities, IRBs and ethics committees |
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Precedence Research Companies Quadrant
The Precedence Research Companies Quadrant positions key participants in the Europe Phase 3 clinical trials market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 revenue in this market and our assessment of its technology, therapeutic expertise and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Leaders: IQVIA, ICON, Thermo Fisher (PPD), Parexel, Syneos Health, and Fortrea combine large revenue with global reach, broad therapeutic expertise, and data and technology platforms.
Challengers: PSI CRO has large operations but is restructured or less differentiated.
Innovators: Medpace and Ergomed bring specialized therapeutic focus or real-world data capabilities.
Niche Players: TFS HealthScience serves narrower regional or therapeutic segments.
Recent Developments
- July 2025: The revised ICH E6(R3) Good Clinical Practice guideline, covering the overarching principles and Annex 1. It introduced a more flexible, risk-proportionate approach to clinical trial management, with greater emphasis on quality-by-design, participant safety, and reliable trial data.
- January 2025: The EU Clinical Trials Regulation (CTR) became fully applicable, requiring all ongoing clinical trials to transition to the Clinical Trials Information System (CTIS). More than 5,000 trials were successfully transitioned during the three-year implementation period, establishing a unified framework for clinical trial applications, oversight, and transparency across the EU.
Europe Phase 3 Clinical Trials Market Segments
By Indication
- Oncology
- Cardiovascular & Metabolic
- Autoimmune & Inflammatory
- CNS
- Infectious Diseases
- Others
By Sponsor
- Pharmaceutical Companies
- Biotechnology Companies
- Medical Device & Others
By Service Type
- Site Management & Monitoring
- Patient Recruitment & Retention
- Data Management & Biostatistics
- Clinical Supply & Logistics
- Central Lab & Others
- Regulatory & Medical Writing
By Trial Model
- Traditional Site-Based
- Hybrid & Decentralized
By Country
- Germany
- U.K.
- France
- Spain
- Italy
- Rest of Europe
Research Methodology
The Europe Phase 3 clinical trials market was defined as Phase 3 clinical trial spending, including sponsor and outsourced services, in Europe. The 2025 base year was built bottom-up from active Phase 3 studies, patients, and costs by indication, sponsor, service type, and region, and checked top-down against published clinical trial market estimates by phase and the revenues of leading CROs. Segment, country, and company values were allocated from indications, sponsors, services, and regional study activity. Key estimates were verified by cross-checking company disclosures, regulatory and industry data, and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional, and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View
The Europe Phase 3 clinical trials market is driven by strong late-stage drug pipelines, rising trial complexity, and increasing reliance on CROs for clinical development activities. Growing investments in oncology, obesity, and cardiometabolic programs are supporting demand, while hybrid trial models and technology adoption are improving trial efficiency. However, high study costs, patient recruitment challenges, and fluctuations in biotech funding may limit growth. Overall, market expansion will depend on pipeline strength, outsourcing demand, and the ability to manage trial costs and timelines.
Sources and References
- European Medicines Agency. "Clinical Trials Regulation now fully applicable in EU". January 2025. (Source: ema.europa.eu)
- European Medicines Agency. "The ICH E6(R3) Guideline: A Major Update to Good Clinical Practice". July 2025. Article. https://www.thefdalawblog.com/2025/02/the-ich-e6r3-guideline-a-major-update-to-good-clinical-practice/
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting