
Process Oil Market Size, Key Companies, Company Market Share, Production Capacity, Raw Material Pricing, Export & Import Analysis, Manufacturing Cost, Competitive Positioning, and Demand Forecast
Vidyesh Swar, a Chemical and Materials Industry Expert, estimates the process oil market at USD 6.17 billion in 2026 to USD 8.93 billion by 2035, growing at a CAGR of 4.20%. Major process oil market companies such as ExxonMobil, Shell, Nynas, Nynas are competing across key material and application segments, including type, function, application and region.
Source: https://www.precedenceresearch.com/process-oil-market
 Get a Sample
 Report Description


Process Oil Market Trends, Share, and Growth Analysis 2035
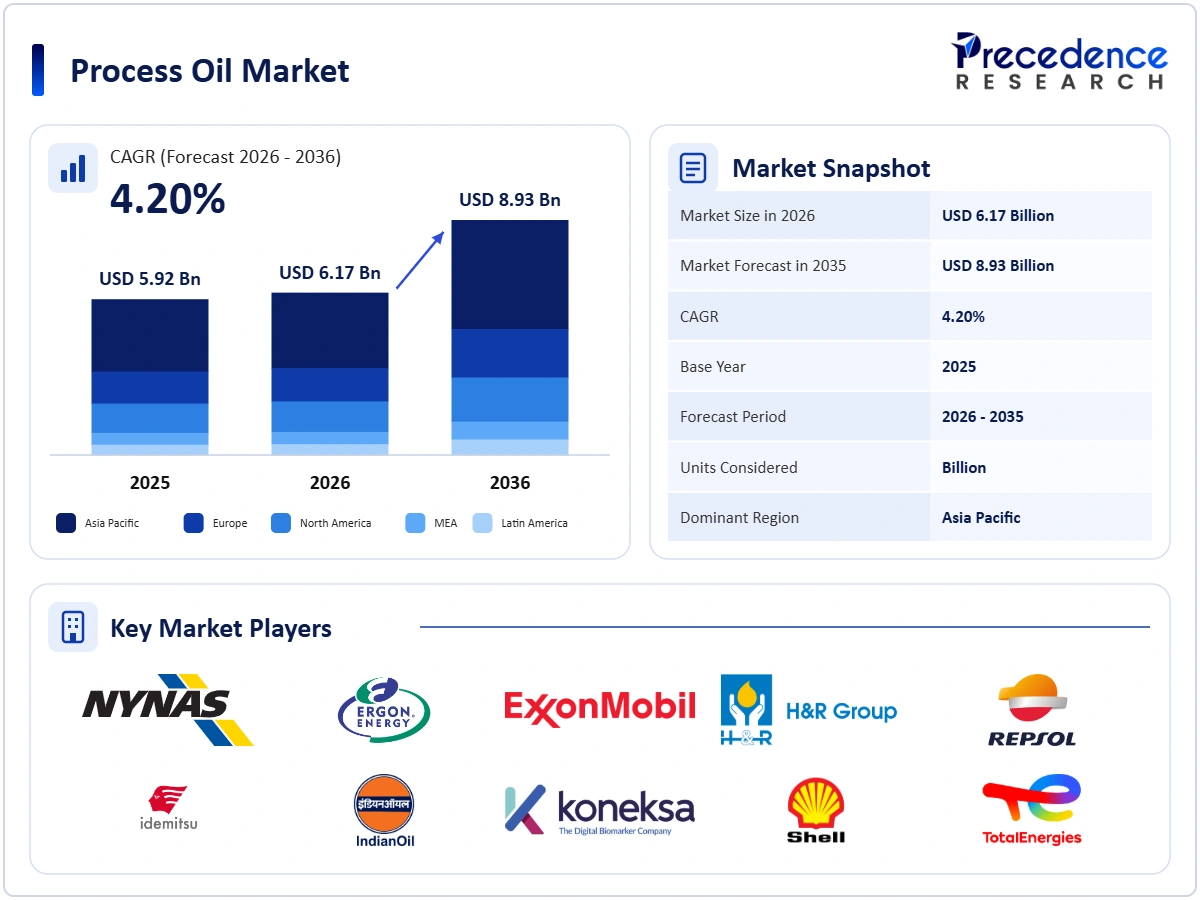
The process oil market is forecasted to expand from USD 6.17 billion in 2026 to USD 8.93 billion by 2035, growing at a CAGR of 4.20% from 2026 to 2035.
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 5.92 billion
- Estimated market size in 2026: USD 6.17 billion
- Projected market size by 2035: USD 8.93 billion
- CAGR (2026-2035): 4.20%
Regional Market Spotlight
- Asia Pacific led the market with a 46.40% share of USD 2.75 billion in 2025 and is projected to be the fastest-growing region, at a CAGR of 4.72% from 2025 to 2035.
- Europe accounted for 20.60% with USD 1.22 billion of the market in 2025.
- North America accounted for 18.80% with USD 1.11 billion of the market in 2025.
Segmental Spotlight
- By type, paraffinic accounted for 38.60% with USD 2.29 billion in 2025.
- By function, extender oil accounted for 44.60% with USD 2.64 billion in 2025.
- By application, tyres & rubber processing accounted for 52.20% with USD 3.09 billion in 2025.
Process Oil Market Size and Forecast, 2025-2035 (USD Billion)
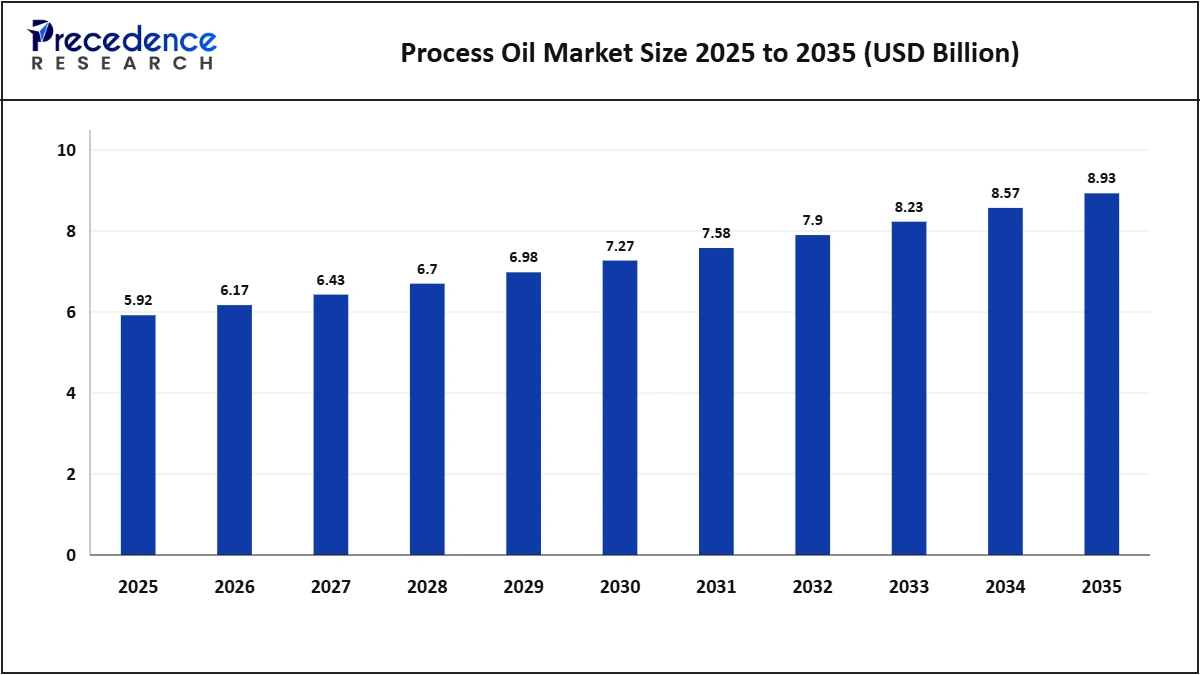
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The process oil market is projected to grow from USD 5.92 billion in 2025 to USD 8.93 billion by 2035 because tyre, rubber, polymer, adhesive, and consumer product makers use process oils to improve processing, flexibility, and cost in their formulations. Regulations on polycyclic aromatic hydrocarbons shift demand toward higher-value non-carcinogenic oils, lifting the market to USD 7.27 billion by 2030 and sustaining a CAGR of 4.20% from 2026 to 2035.
- Analyst View: We built the estimate from process oil consumption volumes by type, function, application and region, multiplied by average prices for naphthenic, paraffinic, non-carcinogenic aromatic and white oil grades. Volumes reflect tyre and rubber production, polymer and thermoplastic elastomer output, adhesive and coating manufacturing and consumer product demand. The total was cross-checked against the specialty oil revenue of leading refiners and against published estimates, which places our base year slightly above the comparable figures. The growth rate reflects rubber and polymer growth in Asia and low-PAH substitution, moderated by base oil price volatility.
Market Trends
- Non-carcinogenic oils replace high-PAH aromatics.
- Naphthenic oils gain in adhesives and polymers.
- Thermoplastic elastomers increase paraffinic oil use.
- High-purity white oils grow in consumer products.
- Group I closures tighten paraffinic supply.
- Distributors consolidate regionally.
Drivers, Restraints and Opportunities
Driver
Tyre and rubber production continues to grow, especially in Asia. Polymer and thermoplastic elastomer manufacturing uses process oils as plasticisers. Adhesives, sealants and coatings industries expand with construction and packaging. Regulations restricting polycyclic aromatic hydrocarbons drive demand for non-carcinogenic oils. Consumer products and pharmaceuticals need high-purity white oils.
Restraint
Closures of Group I base oil refineries reduce paraffinic and aromatic process oil supply. Crude and base oil price volatility affects margins. Bio-based oils compete in some applications. Electric vehicles may change tyre compound requirements. Environmental scrutiny of mineral oils in consumer products is increasing.
Opportunity
Non-carcinogenic and bio-blended process oils can command premiums. Tyre production for electric vehicles may need specialised oils. Growth in thermoplastic elastomers offers new demand. Re-refined and circular process oils can address sustainability goals. Expanding rubber and polymer industries in India and Southeast Asia offer growth.
Market Segmentation: 2025 Share and Value
Process Oil Market By Type 2025 Share
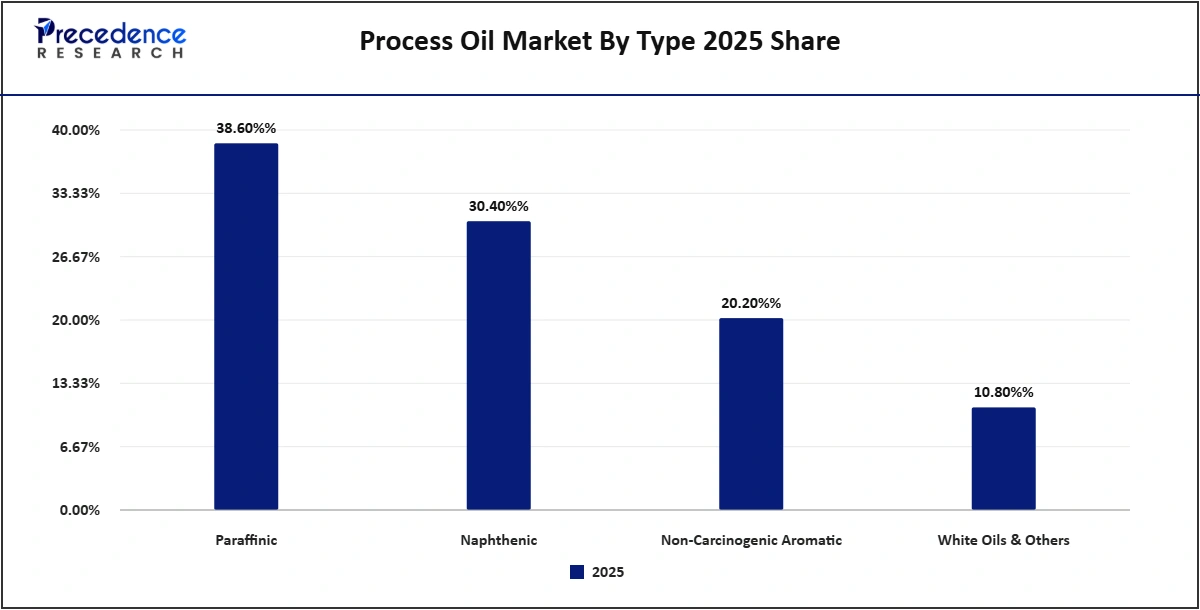
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Paraffinic process oils accounted for 38.60% with USD 2.29 billion in 2025 because they offer good oxidation stability, low colour, and compatibility with EPDM, thermoplastic elastomers, and many polymers, and are widely produced by Group I and Group II refiners. Naphthenic oils, at 30.40% with USD 1.80 billion, provide high solvency and low-temperature performance for rubber, adhesives, inks, and transformer and metalworking applications.
Non-carcinogenic aromatic oils such as TDAE, MES, and RAE account for 20.20% with USD 1.20 billion and are the fastest-growing type because European and other regulations restrict polycyclic aromatic hydrocarbons in tyres and consumer goods. White oils and others account for 10.80% with USD 0.64 billion.
Process Oil Market By Function 2025 Share & Size
| Segments | 2025 Share | 2025 Market Value |
| Extender Oil | 44.60% | USD 2.64 billion |
| Plasticizer | 26.20% | USD 1.55 billion |
| Solvent | 11.40% | USD 0.67 billion |
| Defoamer & Others | 17.80% | USD 1.05 billion |
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Extender oil accounted for 44.60% with USD 2.64 billion in 2025 because tyre and synthetic rubber producers add large quantities of oil to rubber compounds to improve processing and reduce cost. Plasticizer uses account for 26.20% with USD 1.55 billion, solvents for 11.40% with USD 0.67 billion, and defoamers and others for 17.80% with USD 1.05 billion.
Process Oil Market By Application 2025 Share
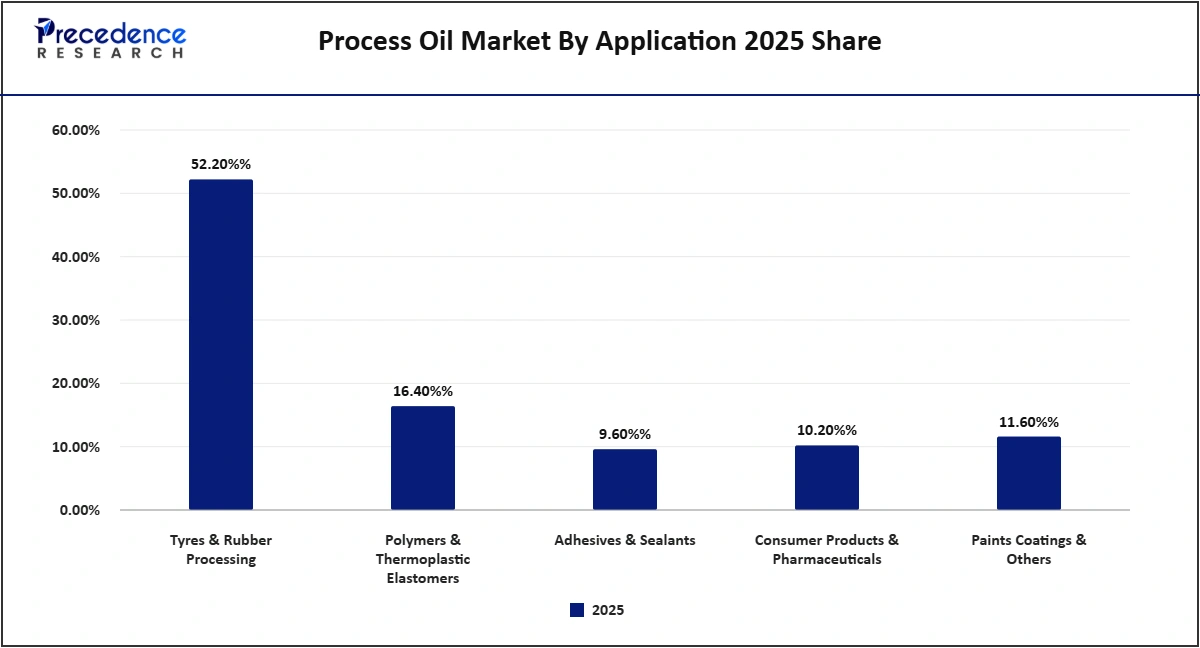
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Tyres and rubber processing accounted for 52.20% with USD 3.09 billion in 2025 because tyres, belts, hoses, and other rubber goods use large volumes of extender and plasticizer oils. Polymers and thermoplastic elastomers account for 16.40% with USD 0.97 billion and are the fastest-growing application, consumer products and pharmaceuticals for 10.20% with USD 0.60 billion, adhesives and sealants for 9.60% with USD 0.57 billion and paints, coatings, and others for 11.60% with USD 0.69 billion.
- Analyst View: Segment values were allocated by matching process oil volumes and prices to types, functions, and applications, using refiner revenue mixes. Paraffinic oils lead because of broad rubber and polymer use, and tyres lead because of extender oil volumes. We expect non-carcinogenic oils and polymers and thermoplastic elastomers to gain share.
Regional Analysis
Process Oil Market By Region 2025 Share
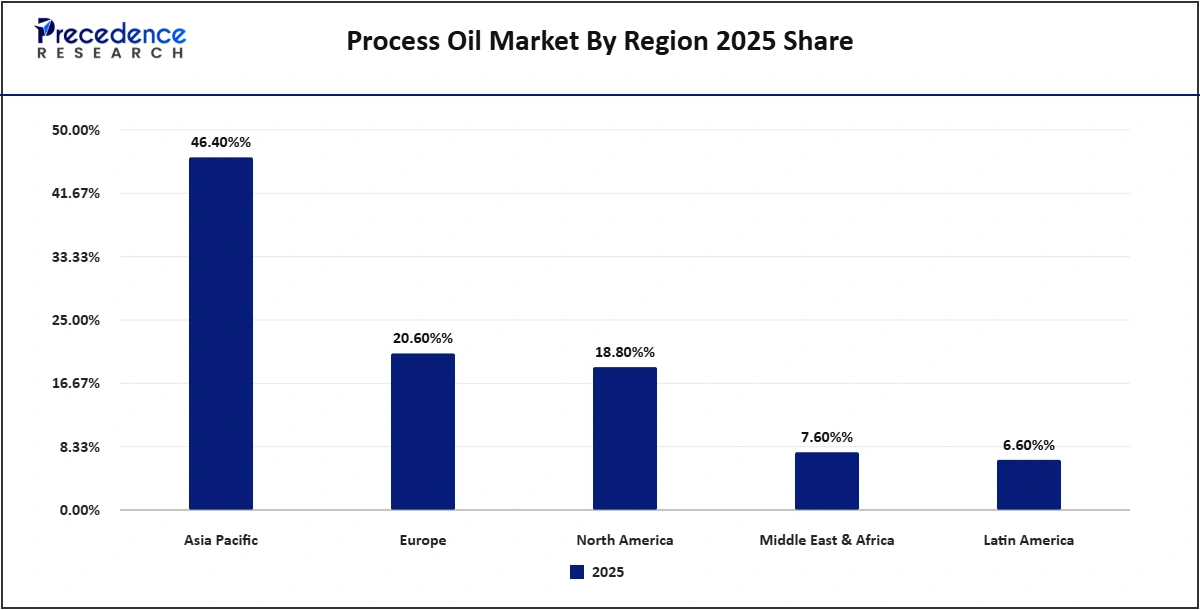
Note: 2025 is the base year.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Asia Pacific accounted for 46.40% with USD 2.75 billion in 2025, the largest share and the fastest growth, supported by tyre manufacturing in China, India, Thailand, Indonesia and Japan, large polymer and rubber goods industries and growing consumer product demand. Europe, at 20.60% with USD 1.22 billion, is supported by tyre and rubber production, strict PAH regulations, and specialty naphthenic refiners such as Nynas. North America, at 18.80% with USD 1.11 billion, is supported by naphthenic refiners such as Ergon and Calumet, tyre production, and adhesives and polymer industries. The Middle East and Africa, at 7.60% with USD 0.45 billion, and Latin America, at 6.60% with USD 0.39 billion, are supported by refining capacity, tyre plants, and rubber goods manufacturing.
Asia Pacific accounted for 46.40% with USD 2.75 billion in 2025 and is the largest and fastest-growing region. China, India and Thailand are major tyre and rubber producers. Polymer and thermoplastic elastomer output is expanding. Regional refiners supply paraffinic and aromatic oils.
Europe accounted for 20.60% with USD 1.22 billion in 2025. EU REACH rules restrict PAH content in tyres and consumer goods, driving demand for TDAE, MES and naphthenic oils. Nynas, a leading naphthenic specialist, reported higher full-year 2025 adjusted EBITDA. Tyre makers in Germany, France and Italy are major users.
North America accounted for 18.80% with USD 1.11 billion in 2025. Specialty naphthenic refiners in the United States supply rubber, adhesives, and industrial users. Tyre plants and polymer producers drive demand. Distributors consolidate to serve customers.
The Middle East and Africa accounted for 7.60% with USD 0.45 billion in 2025. Gulf refiners produce base oils and process oils for export. Tyre and rubber plants in the region add demand.
Latin America accounted for 6.60% with USD 0.39 billion in 2025. Tyre and rubber goods industries in Brazil and Mexico drive demand.
Analyst View: Regional shares were built from process oil consumption, refining capacity, and prices in each region. Asia Pacific leads because of tyre and rubber manufacturing scale. We assign Asia Pacific the highest growth premium because rubber, polymer, and consumer product output is growing fastest there.
Top 10 Companies in the Process Oil Market
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | ExxonMobil | 0.52 | 8.78% | Paraffinic and naphthenic process oils | United States |
| 2 | Shell | 0.46 | 7.77% | Catenex and Flavex process oils | United Kingdom |
| 3 | Nynas | 0.42 | 7.09% | Naphthenic process oils | Sweden |
| 4 | Ergon | 0.38 | 6.42% | Hyprene naphthenic process oils | United States |
| 5 | Calumet | 0.30 | 5.07% | Naphthenic and paraffinic specialty oils | United States |
| 6 | H&R Group | 0.28 | 4.73% | TDAE and specialty process oils | Germany |
| 7 | Indian Oil | 0.22 | 3.72% | Rubber process oils | India |
| 8 | Idemitsu Kosan | 0.18 | 3.04% | Diana process oils | Japan |
| 9 | Repsol | 0.14 | 2.36% | Extensoil process oils | Spain |
| 10 | TotalEnergies | 0.14 | 2.36% | Plaxolene and Torilis process oils | France |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
ExxonMobil led the process oil market with an estimated 8.78% of USD 0.52 billion of 2025 revenue, followed by Shell at 7.77% with USD 0.46 billion and Nynas at 7.09% with USD 0.42 billion. ExxonMobil leads with a broad range of paraffinic and naphthenic process oils supplied from integrated refineries to tyre, rubber and polymer customers worldwide. Shell competes with Catenex and other process oils, and Nynas is a leading naphthenic specialist whose Naphthenic Specialty Products business offset lower fourth-quarter 2025 volumes with higher unit margins. Ergon and Calumet are major North American naphthenic refiners, H&R Group is a leading TDAE producer in Europe, and Indian Oil, Idemitsu, Repsol and TotalEnergies supply process oils from their refineries.
The top 10 companies accounted for an estimated 51.35% with USD 3.04 billion of 2025 revenue, while the remaining 48.65% with USD 2.88 billion was shared among regional refiners, re-refiners and specialty oil distributors. The process oil market is moderately concentrated among refiners with specialty processing capability, and competition centres on solvency, PAH compliance, purity, consistency, supply reliability, and price. Naphthenic and non-carcinogenic grades command premiums, while standard paraffinic oils compete closely with Group I base oil availability.
Recent Developments
- In February 2026, Nynas reported full-year 2025 adjusted EBITDA of SEK 1,401 million, up from SEK 1,333 million, with higher unit margins in its Naphthenic Specialty Products business offsetting lower fourth-quarter volumes.
Process Oil Market Segments
By Type
- Paraffinic
- Naphthenic
- Non-Carcinogenic Aromatic (TDAE, MES, RAE)
- White Oils & Others
By Function
- Extender Oil
- Plasticizer
- Solvent
- Defoamer & Others
By Application
- Tyres & Rubber Processing
- Polymers & Thermoplastic Elastomers
- Adhesives & Sealants
- Consumer Products & Pharmaceuticals
- Paints, Coatings & Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- U.K.
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC
- South Africa
- Rest of MEA
Research Methodology
The process oil market was defined as paraffinic, naphthenic, non-carcinogenic aromatic and white process oils for rubber, polymers, adhesives, coatings and consumer products, worldwide. The 2025 base year was built bottom-up from process oil consumption volumes by type, function, application and region and average prices, and checked top-down against the specialty oil revenue of leading refiners. Segment, regional and company values were allocated from types, functions, applications and regional demand.
Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View Overall Market
The process oil market is a steady market tied to tyre, rubber and polymer production, with value shifting toward naphthenic and non-carcinogenic grades. Our estimate links demand to consumption volumes and prices by type and application, so the forecast follows rubber and polymer output, regulation and refinery supply. The main upside comes from non-carcinogenic oils and Asian growth, while the main risks are base oil supply changes and price volatility.
Sources and References
- Nynas. "Nynas reports strong Q4 earnings growth and improved financial position". 2026-02-26. Nynas 2025 results. https://nynas.com/en/investors/ir-press-releases/2026/nynas-reports-strong-q4-earnings-growth-and-improved-financial-position/
- Digital Refining. "Ergon to expand capabilities at its specialty oil refinery". 2014-10-14. Ergon naphthenic refinery. https://www.digitalrefining.com/news/1003178/ergon-to-expand-capabilities-at-its-specialty-oil-refinery
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions
Tags


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample

 sales@precedenceresearch.com
 Schedule a Meeting