



Adrenoleukodystrophy Drugs Market Size, Growth, Trends, Segmentation, and Forecast 2026-2034
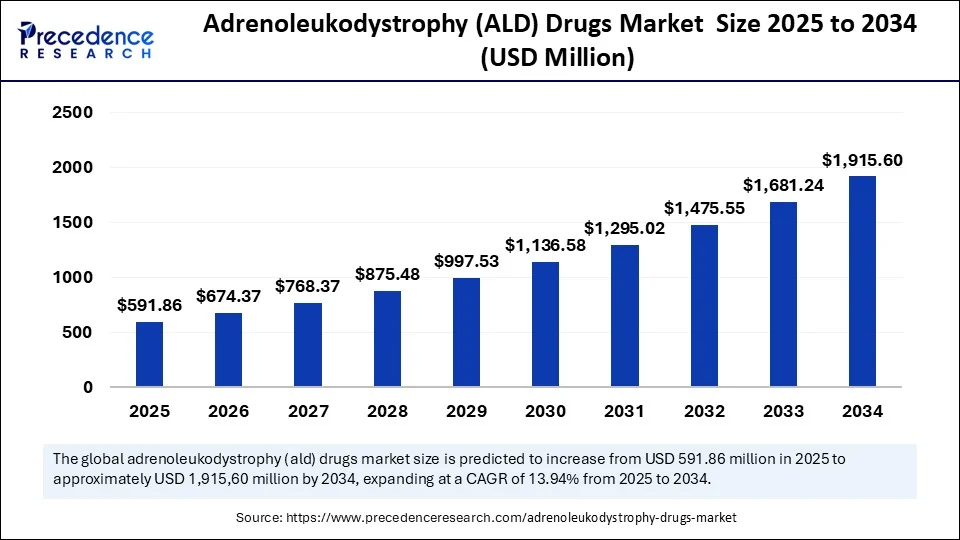
The global adrenoleukodystrophy (ALD) drugs market size accounted for USD 674.37 million in 2026 and is forecasted to hit around USD 1,915.60 million by 2034, representing a CAGR of 13.94% from 2026 to 2034. The North America market size was estimated at USD 228.56 million in 2024 and is expanding at a CAGR of 14.07% during the forecast period. The market sizing and forecasts are revenue-based (USD Million/Billion), with 2026 as the base year.
Source: https://www.precedenceresearch.com/adrenoleukodystrophy-drugs-market
 Get a Sample
 Table Of Content


Adrenoleukodystrophy (ALD) Drugs Market Size and Forecast 2026 to 2034
The global adrenoleukodystrophy (ALD) drugs market size was valued at USD 674.37 million in 2026 and is projected to reach approximately USD 1,915.60 million by 2034, growing at a CAGR of 13.94% from 2026 to 2034. Improved detection through newborn screening, greater disease awareness, and the development of new treatment options may support demand in the ALD drugs market.
Adrenoleukodystrophy (ALD) Drugs Market Key Takeaways
- In terms of revenue, the global adrenoleukodystrophy (ALD) drugs market was valued at USD 674.37 million in 2026.
- It is projected to reach USD 1,915.60 million by 2034.
- The market is expected to grow at a CAGR of 13.94% from 2026 to 2034.
- North America dominated the adrenoleukodystrophy (ALD) drugs market with largest market share of 44% in 2026.
- Asia-Pacific is expected to expand at the fastest CAGR between 2026 and 2034.
- By treatment type, the gene therapy (lenti-based) segment contributed the biggest market share of 38% in 2026.
- By treatment type, the AAV-based gene therapy segment is expected to grow at a significant CAGR during the forecast period.
- By disease type, the childhood cerebral ALD segment captured the highest market share of 52% in 2026.
- By disease type, the adrenomyeloneuropathy (AMN) segment is expected to grow at the highest CAGR between 2026 and 2034.
- By route of administration, the intravenous (IV) segment held the major market share of 47% in 2026.
- By route of administration, the intrathecal segment is expected to grow at the fastest rate between 2026 and 2034.
- By distribution channel, the hospital pharmacies segment generated the significant share of 40% in 2026.
- By distribution channel, the online pharmacies segment is expected to grow at the fastest CAGR in the coming years.
How is Artificial Intelligence Supporting Rare Disease Research and Diagnosis?
Artificial intelligence is revolutionizing the treatment approaches of rare diseases, including ALD, by optimizing diagnosis, drug discovery, and clinical trials. AI algorithms are being employed in the early detection and diagnosis of ALD, AI may help researchers investigate diagnostic patterns in rare diseases, although its impact on ALD diagnosis requires further clinical validation. Machine learning models trained on electronic health records and imaging data are identifying subtle patterns in brain magnetic resonance imaging MRIs that cloud indicate cerebral ALD. Beyond diagnosis, AI tools may support target identification and compound screening, although their impact on ALD drug development remains to be established. Traditional drug development can take up to a decade, but AI-driven platforms are analyzing massive datasets to predict molecular targets and optimize drug compounds that target neuroinflammation and oxidative stress associated with ALD progression.
Personalized treatment is another area where AI is making a mark. Predictive analytics help doctors understand how individual patients might respond to therapies based on their genomic profiles, allowing for a more tailored and effective treatment plan. This precision medicine approach could be especially vital for a complex disease like ALD, which presents with diverse phenotypes and progression patterns. In clinical trials, AI enhances patient recruitment and monitoring. Natural language processing tools may help researchers identify eligible participants from clinical records, subject to data access, privacy requirements, and validation.
Market Overview
The adrenoleukodystrophy (ALD) drugs market comprises pharmacological treatments and investigational therapies aimed at treating or managing adrenoleukodystrophy, a rare, X-linked genetic disorder caused by mutations in the ABCD1 gene. The condition leads to the accumulation of very-long-chain fatty acids (VLCFAs) in the brain and adrenal cortex, impacting the nervous system and adrenal gland function. The market includes corticosteroids, gene therapies, hematopoietic stem cell transplantation (HSCT)-linked therapies, dietary management adjuncts, and emerging pharmacological agents that attempt to halt or reverse disease progression, especially in cerebral and adrenomyeloneuropathy (AMN) subtypes.
Adrenoleukodystrophy is a rare, inherited metabolic disorder that affects the adrenal glands, spinal cord, and white matter of the nervous system. ALD is an X-linked genetic disorder associated with ABCD1 gene variants and can manifest in childhood or adulthood, with clinical presentations that include cerebral ALD, adrenomyeloneuropathy, and adrenal insufficiency. A major growth catalyst is the availability of newborn screening programs, especially in developed nations. Early detection through screening has led to increased diagnosis, which in turn fuels the demand for timely intervention.
Key Market Trends
- Advancements in gene therapy: One of the most significant factors boosting the growth of the market is advancements in gene therapy, particularly Skysona (elivaldogene autotemcel), an FDA-approved gene therapy for eligible patients with early, active cerebral adrenoleukodystrophy. This one-time gene therapy uses a patient's genetically modified hematopoietic stem cells to introduce functional copies of the ABCD1 gene for the treatment of eligible patients with cerebral ALD.
- Expansion of newborn screening programs: Early diagnosis is critical for drugs, and newborn screening is emerging as a game-changer. Early detection is driving earlier treatment interventions and improved prognoses.
Regulatory support for orphan drugs: Governments and regulatory bodies worldwide are offering incentives to boost the development of novel therapies for rare diseases like ALD. - Integration of artificial intelligence in R&D: AI is being increasingly deployed across the ALD R&D and drug development lifecycle. AI models are expediting drug discovery and target identification. Clinical trial efficiency is improving through AI-supported patient identification and monitoring.
Market Dynamics
Drivers
Increasing Awareness and Supportive Government Initiatives
A key driver in the adrenoleukodystrophy (ALD) drugs market is the growing awareness and advocacy surrounding rare diseases. As people are becoming more aware of ALD, the demand for early diagnosis is rising to reduce lifetime complexity. As a result of the increasing prevalence of rare diseases, governments around the world are taking significant steps by providing funding for R&D and launching campaigns to spread awareness in underserved areas.
Advancements in Treatment Options
Another major driver is the rising development of novel drugs and therapies, including gene therapies. The approval of Skysona has expanded treatment options for eligible patients with early, active cerebral ALD. The therapy uses genetically modified hematopoietic stem cells to introduce functional copies of the ABCD1 gene, although eligibility, safety, and treatment outcomes remain important considerations, encouraging more biopharma companies to enter the market with novel technologies and delivery platforms. Regulatory pathways, including applicable expedited-development and review designations, may support the development of eligible rare-disease therapies. Research funding is provided through separate public and private funding programs. Government incentives and orphan drug policies are further propelling market growth.
Restraint
High Treatment Costs and Limited Patient Population
The adrenoleukodystrophy (ALD) drugs market is restrained by several fundamental challenges. One of the most prominent challenges is the high cost of treatment of ALD. Gene therapies and orphan drugs often carry hefty price tags, making them inaccessible to many patients, even in developed regions. This raises ethical questions about equity in care and puts pressure on insurance systems and reimbursement frameworks. Another limiting factor is the complexity of the disease itself. ALD presents in various forms, such as childhood cerebral, adrenomyeloneuropathy (AMN), and addison-only, each with different rates of progression. This heterogeneity complicates both diagnosis and treatment strategies, slowing clinical trial recruitment and increasing trial design costs due to the need for stratified patient groups.
The market also grapples with a limited patient population and data scarcity. As a rare disease, ALD affects a very small number of individuals, which makes it difficult to conduct large-scale clinical trials. The lack of extensive longitudinal data hampers drug validation and regulatory approval. It also restricts pharmaceutical companies from projecting reliable returns on investment. Regulatory hurdles pose additional challenges. While orphan drug pathways offer incentives, the regulatory scrutiny for gene therapies remains stringent due to long-term safety concerns. Approval processes can be delayed by the need for extensive post-marketing surveillance and detailed follow-up data, which places a burden on smaller biotech players with limited resources.
Opportunity
Expansion into Emerging Markets
Improved diagnosis, healthcare access, and rare-disease treatment infrastructure could create opportunities for ALD drug manufacturers in emerging markets. Despite low prevalence, the severity of the disease creates a high value per patient model, making it an attractive proposition for pharmaceutical companies aiming to diversify their orphan drug portfolios. This rare disease space allows smaller firms to carve out specialized leadership with less competition. There is also a growing opportunity for geographic expansion, especially across several regions. As awareness spreads the healthcare infrastructure helps in improving the development and manufacturing of the drugs. These evaluations, designed as coping mechanism tests, are administered to patients to gain a deeper understanding of the symptomatology, thereby enabling more targeted and efficacious treatment strategies.
Segments Insights
Treatment Type Insights
Why Did the Gene Therapy Segment Dominate the Market in 2026?
The gene therapy segment dominated the adrenoleukodystrophy (ALD) drugs market with the largest share in 2026. This is mainly due to the proven effectiveness of gene therapies in treating rare diseases. These therapies offer a revolutionary approach by targeting the root genetic cause of the disorder. Treatments like elivaldogene autotemcel, sold under the brand name Skysona, have set a new benchmark. Gene therapy may help preserve neurological function in eligible patients with early, active cerebral ALD. Treatment outcomes, eligibility, and long-term safety require careful clinical assessment.
The lentiviral vector-based gene therapy held the largest share as a sub-segment, due to its unique ability to integrate genetic material into the host cell's genome effectively. This integration allows for stable expression of the therapeutic gene over time, making it particularly advantageous for treating chronic diseases. Lentiviral vectors are used in certain gene therapies because they can integrate therapeutic genetic material into target cells; their suitability depends on the treatment design and clinical indication. Furthermore, lentiviral vectors have a broad cellular tropism, meaning they can transduce a wide range of cell types, including both dividing and non-dividing cells.
The growth outlook for AAV-based gene therapy in ALD depends on the progress of ALD-specific research, clinical trials, and regulatory approvals. AAV-based gene therapy has emerged as a promising area in the field of genetic medicine, utilizing adeno-associated viruses (AAVs) as vectors for delivering therapeutic genes into cells. AAVs are known for their ability to infect a broad range of human cell types without causing disease, making them suitable candidates for gene therapy applications. AAV vectors offer specific delivery characteristics, but their safety depends on the vector design, dose, target tissue, immune response, and clinical indication.
Unlike some viral vectors, AAVs do not integrate into the host genome, which reduces the risk of insertional mutagenesis, a concern in gene therapy that could potentially lead to cancer. This characteristic has led to AAVs being utilized in various clinical trials and approved therapies for several genetic disorders. Researchers are continuously developing new serotypes of AAVs and engineering to enhance their targeting capabilities, which can lead to more effective treatments with fewer side effects. These improvements have broadened the applications of AAV gene therapies to include conditions like spinal muscular atrophy, hemophilia, retinal diseases, and certain inherited metabolic disorders.
Disease Type Insights
What Made Childhood Cerebral ALD the Dominant Segment in the Adrenoleukodystrophy (ALD) Drugs Market?
The childhood cerebral ALD (ccALD) dominated the market in 2026, due to its aggressive progression and high treatment urgency. Childhood cerebral ALD often develops during childhood and can progress rapidly, making early identification and timely specialist assessment important. This form of ALD requires immediate and intensive intervention, often in the form of gene therapy or hematopoietic stem cell transplantation.
Parents and clinicians have become aware of early signs such as behavioral changes, attention difficulties, and coordination loss, prompting faster diagnosis compared to adult-onset forms. This has increased pediatric patient inclusion in clinical trials and treatment programs. Due to its severity and measurable response to early treatment, most of the regulatory and R&D efforts are concentrated around childhood cerebral ALD. Many of the FDA-approved and orphan-designated drugs specifically target this phenotype.
Meanwhile, the adrenomyeloneuropathy (AMN) segment is expected to grow at the fastest rate during the forecast period, as it is the most common phenotype of ALD. This, in turn, drives the demand for drugs specifically targeting AMN. The increasing awareness about AMN and improved diagnostic capabilities further support segmental growth. Unlike the childhood cerebral form, AMN progresses slowly, making it underdiagnosed for decades. However, new advancements in neurometabolic screening are bringing this form into clearer clinical focus. As adult males with ALD begin to experience symptoms like spasticity, bladder dysfunction, and progressive weakness, they are now more likely to be correctly diagnosed as having AMN rather than being misclassified under broader neurodegenerative conditions. This improved identification is naturally fueling the demand for targeted therapies. Moreover, the absence of curative treatment for AMN creates a vast space for innovation and intervention. While supportive therapies such as physiotherapy and pain management are common, patients and clinicians are increasingly seeking disease-modifying options, including gene therapy and neuroprotective agents. This unmet need drives pharmaceutical research and market interest.
As individuals with ALD live into adulthood, ongoing monitoring for adult-onset manifestations, including AMN, remains important. The extent to which changes in survival affect the diagnosed AMN population requires epidemiological evidence. As this patient population grows, the market demand for long-term, adult-focused care and medication will only continue to rise. The rise in patient advocacy and clinical trial activity targeting AMN is turning it into a spotlight condition within the ALD family. Research pipelines now include therapies tailored specifically to the spinal cord and peripheral nerves, making AMN not just a growing challenge but also a promising growth area in the rare disease treatment landscape.
Route of Administration Insights
How Does the Intravenous (IV) Segment Dominate the Market in 2026?
The intravenous (IV) segment dominated the adrenoleukodystrophy (ALD) drugs market with a major revenue share in 2026. This is primarily due to the complexity and potency of treatments like gene and stem cell therapies. These advanced therapies require direct delivery into the bloodstream for maximum efficacy and controlled dispersion. IV administration ensures rapid absorption and immediate therapeutic action, which is crucial in early diagnosed cerebral ALD cases, where neurological decline is swift and irreversible.
IV is the preferred choice for high-impact drugs like elivaldogene autotemcel, which depend on precise systemic distribution. Hospitals and specialty clinics are well-equipped for IV delivery, making it the standard route in pediatric and acute care settings. This facilitates clinical monitoring, especially post-infusion, where side effects or immune responses must be closely observed. Intravenous therapy also allows for the delivery of large molecular weight drugs and gene-based constructs, which cannot be effectively absorbed through oral or intramuscular routes. The pharmacokinetics of such therapies demand IV precision. Intravenous administration is used for certain ALD treatments, including the infusion of gene-modified hematopoietic stem cells. The appropriate route depends on the specific therapy and clinical indication.
On the other hand, intrathecal administration, which involves injecting drugs directly into the spinal fluid, is emerging as the fastest-growing segment due to its direct access to the central nervous system. This approach is particularly valuable in targeting cerebral ALD, where brain inflammation and demyelination are central challenges. By bypassing the blood-brain barrier, intrathecal delivery allows therapeutic agents to reach the affected areas more effectively. Intrathecal delivery is being investigated for selected neurological conditions; its role in ALD requires evidence from ALD-specific clinical studies.
Although still in its early stages of adoption, the precision and CNS-targeted impact of this method have made it attractive in advanced clinical trials. It is being explored especially in patients who may not respond to systemic IV treatment. The clinical role of intrathecal administration in ALD remains dependent on therapy-specific evidence, safety findings, and regulatory developments.
Distribution Channel Insights
Why Did the Hospital Pharmacies Segment Dominate the Adrenoleukodystrophy (ALD) Drugs Market in 2026?
The hospital pharmacies segment dominated the market in 2026, primarily due to their immediate access to medications following diagnosis and treatment. They play a crucial role in patient care by offering a wide range of complex medications that may not be readily available elsewhere and by collaborating closely with healthcare providers to ensure tailored treatment plans. Additionally, hospital pharmacists provide valuable patient education on medication use and safety, enhancing overall treatment efficacy.
On the other hand, the online pharmacies segment is experiencing rapid growth thanks to their convenience and accessibility, allowing customers to order medications from home at any time, often at lower prices. The ability to receive home delivery of prescriptions, along with the integration of telehealth services, makes online pharmacies particularly appealing for patients seeking quick and efficient service. While hospital pharmacies excel in providing immediate care within the healthcare system, online pharmacies cater to increasing consumer demand for convenience and cost-effectiveness.
Regional Insights
U.S. Adrenoleukodystrophy (ALD) Drugs Market Size and Growth 2026 to 2034
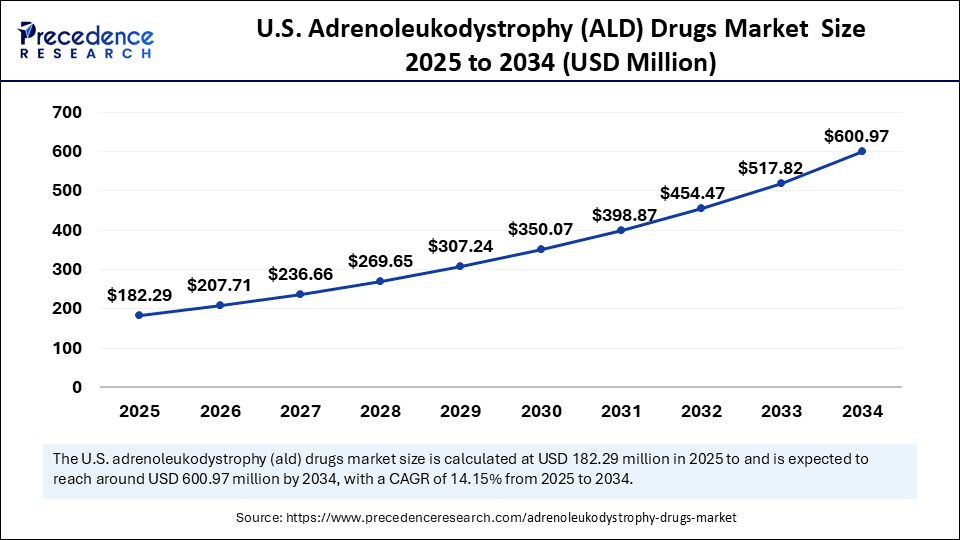
The U.S. adrenoleukodystrophy (ALD) drugs market size was exhibited at USD 207.71 million in 2026 and is projected to be worth around USD 600.97 million by 2034, growing at a CAGR of approximately 14.21% from 2026 to 2034.
What Made North America the Dominant Region in the Adrenoleukodystrophy (ALD) Drugs Market?
North America dominated the market by capturing a 44% share in 2026. The region's dominance is mainly attributed to its robust healthcare infrastructure and the strong presence of leading pharmaceutical and biopharmaceutical companies that are actively engaging in rare disease research and drug development. The United States accounts for a substantial share of the North American ALD drugs market. The U.S. has implemented comprehensive newborn screening programs, significantly increasing early detection rates. This early intervention boosts the demand for targeted therapies, especially in pediatric segments. Regulatory frameworks such as orphan drug designation, accelerated approval, and incentives for ALD-related innovations further support regional market growth.
The rising research funding and public-private partnerships further bolster novel drug development. Moreover, high disease awareness, widespread genetic counseling services, and the availability of advanced diagnostics tools ensure that more patients are not only diagnosed in time but also receive appropriate therapy.
What Factors Support the Growth of the Market in Asia Pacific?
Asia-Pacific is emerging as the fastest-growing market for ALD drugs, fueled by rising healthcare investments and increased rare disease awareness. Countries like India, China, and Japan are witnessing a shift toward early genetic screening and personalized care models. Government initiatives promoting orphan drug research and rare disease registries are gaining traction, especially in urban healthcare systems. This creates opportunities for pharmaceutical companies to explore untapped patient pools. As diagnostic technologies become more affordable and accessible, early detection rates are improving. This shift is unlocking a previously untapped patient base and driving interest in advanced therapies, such as gene editing and cell therapy.
Local biotech firms are increasingly collaborating with international players to bring innovative treatments to the region. These strategic alliances help overcome the hurdles of limited expertise and infrastructure. The Asia-Pacific ALD drugs market may expand as rare-disease awareness, diagnostic capacity, healthcare access, and treatment availability improve.
Adrenoleukodystrophy (ALD) Drugs Market Comapnies
- bluebird bio, Inc.
- Minoryx Therapeutics
- Apollo Therapeutics
- Orchard Therapeutics
- MedDay Pharmaceuticals
- SOM Biotech
- Sage Therapeutics
- Abeona Therapeutics Inc.
- Regenxbio Inc.
- Passage Bio
- PTC Therapeutics
- Polaryx Therapeutics
- BridgeBio Pharma
- Takeda Pharmaceutical Company Ltd.
- Sanofi S.A.
- Novartis AG
- Pfizer Inc.
- BioMarin Pharmaceutical Inc.
Recent Developments
- In June 2025, Viking Therapeutics, Inc., a clinical-stage biopharmaceutical company developing new treatments for metabolic and endocrine disorders, announced the start of the VANQUISH Phase 3 clinical program for VK2735, its dual agonist targeting both the glucagon-like peptide 1 and glucose-dependent insulinotropic polypeptide receptors (Source: https://pipelinereview.com)
Segments Covered in the Report
By Treatment Type
- Gene Therapy
- Lentiviral Vector-Based Gene Therapy
- AAV-Based Gene Therapy
- Corticosteroid Replacement Therapy
- Hydrocortisone
- Prednisolone
- Hematopoietic Stem Cell Transplant (HSCT)-Linked Therapies
- Allogeneic HSCT Supportive Drugs
- Small Molecule Therapy
- Lorenzo's Oil and Derivatives
- Other Fatty Acid Modulators
- Supportive Care & Symptomatic Therapy
- Anticonvulsants
- Anti-inflammatory Agents
By Disease Type
- Childhood Cerebral ALD (ccALD)
- Adrenomyeloneuropathy (AMN)
- Addison-Only ALD
By Route of Administration
- Oral
- Intravenous (IV)
- Intrathecal
By Distribution Channel
- Hospital Pharmacies
- Specialty Clinics
- Online Pharmacies
- Retail Pharmacies
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- MEA
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
