
U.S. Phase 4 Clinical Trials Market Trends, Leading Companies, Company Revenue / Sales Performance, Procedure Volume, Healthcare Spending, Technology Adoption, Reimbursement Analysis, Competitive Landscape, and Growth Outlook
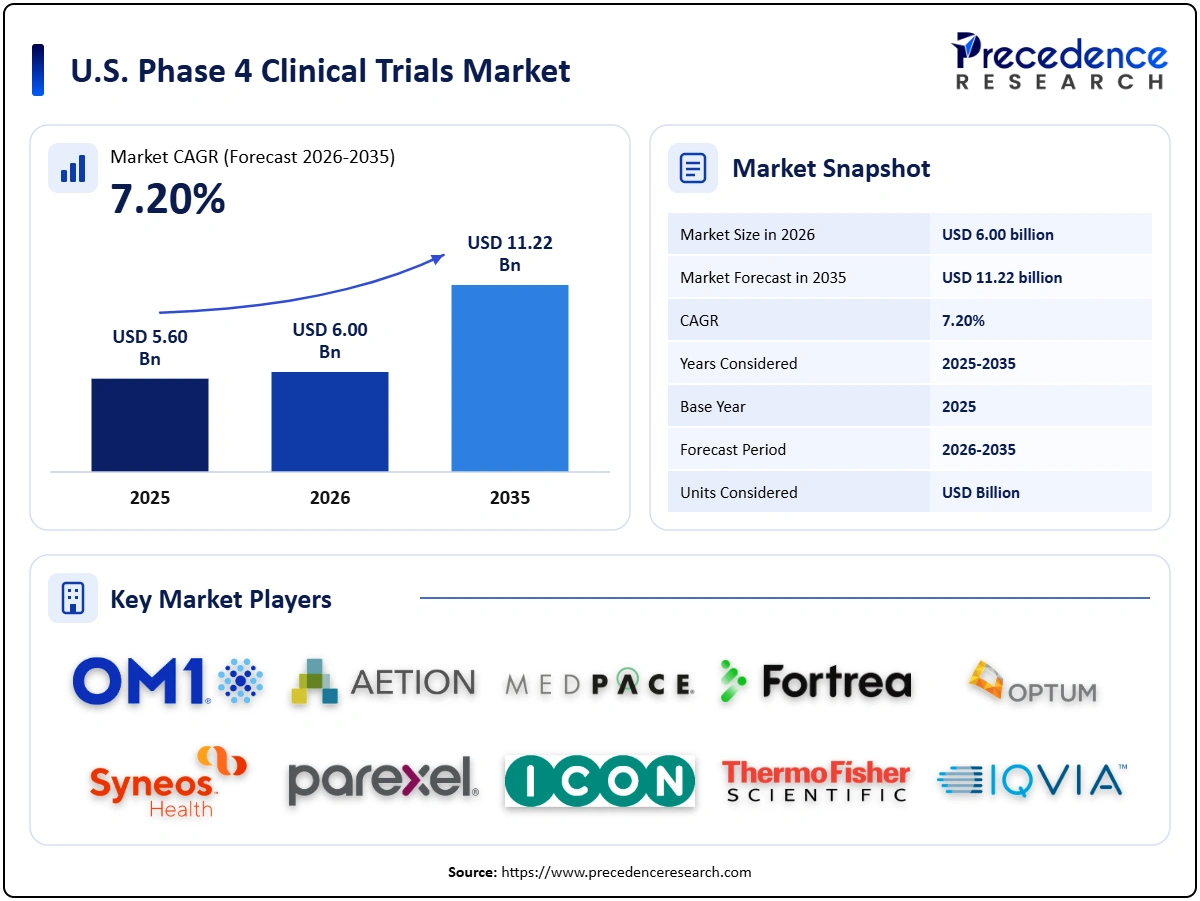
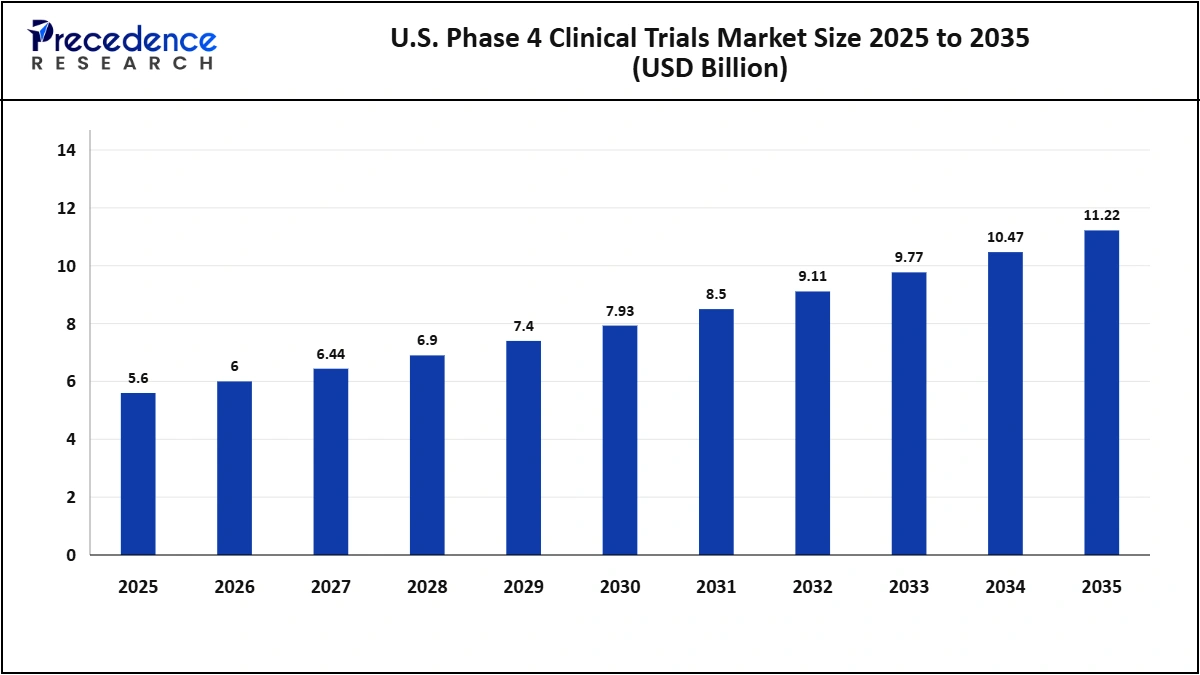
Payal Rabde, a Healthcare Industry Expert, highlights that the U.S. Phase 4 clinical trials market has reached USD 6.00 billion in 2026 and is on track to reach USD 11.22 billion by 2035, advancing at a CAGR of 7.20%. Key U.S. Phase 4 clinical trials market companies shaping the market include IQVIA, ICON, Syneos Health, while major growth segments span study type, indication, sponsor, service type.
Source: https://www.precedenceresearch.com/u-s-phase-4-clinical-trials-market
 Get a Sample
 Report Description

Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 5.60 billion
- Estimated market size in 2026: USD 6.00 billion
- Projected market size by 2035: USD 11.22 billion
- CAGR (2026-2035): 7.20%
Regional Market Spotlight
- Northeast led the market with a 31.40% share, with USD 1.76 billion in 2025.
- South accounted for 30.20% with USD 1.69 billion of the market in 2025 and is projected to be the fastest-growing region, at a CAGR of 7.73% from 2025 to 2035.
- West accounted for 22.80% with USD 1.28 billion of the market in 2025.
Segmental Spotlight
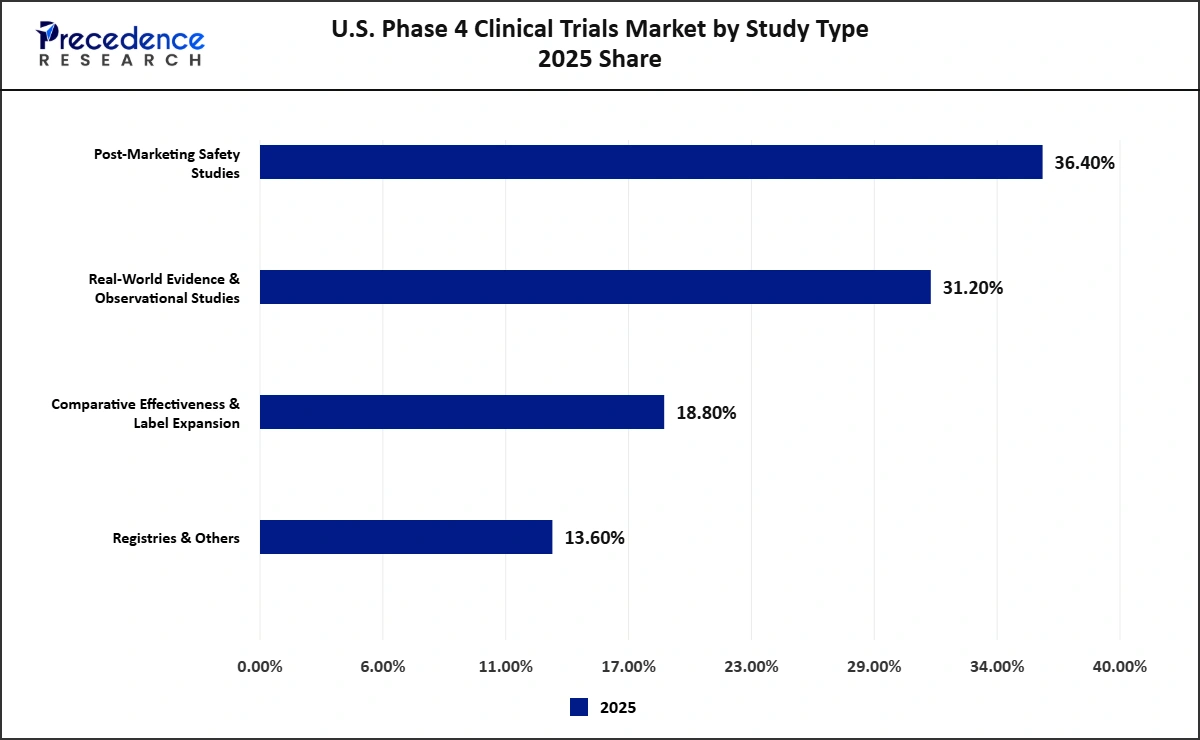
- By study type, the post-marketing safety studies accounted for 36.40% with USD 2.04 billion in 2025.
- By indication, the oncology accounted for 30.40% with USD 1.70 billion in 2025.
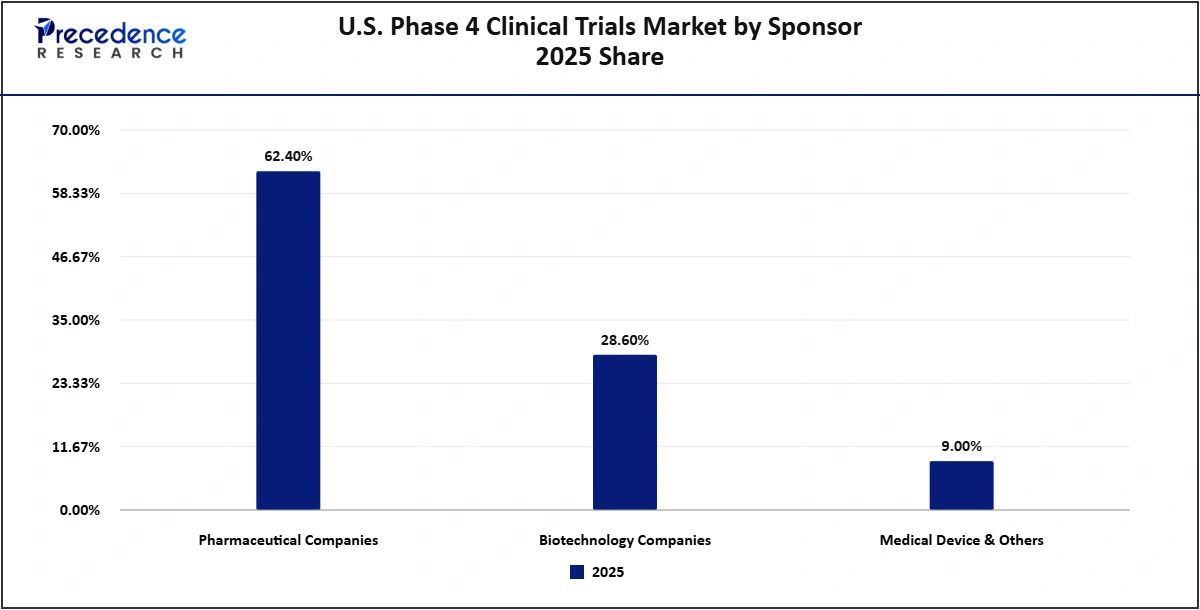
- By sponsor, the pharmaceutical companies accounted for 62.40% with USD 3.49 billion in 2025.
- By service type, the site management & monitoring accounted for 30.20% with USD 1.69 billion in 2025.
U.S. Phase 4 Clinical Trials Market Size and Forecast, 2025-2035 (USD Billion)
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The U.S. Phase 4 clinical trials market is projected to grow from USD 5.60 billion in 2025 to USD 11.22 billion by 2035 because regulators and payers in the United States increasingly require post-approval safety and real-world evidence, and the number of newly approved, complex medicines needing follow-up keeps rising. Real-world evidence demand from regulators and payers, long-term follow-up of cell and gene therapies, registries for rare diseases, digital data collection, and pharmacovigilance outsourcing support solid growth, lifting the market to USD 7.93 billion by 2030 and sustaining a CAGR of 7.20% from 2026 to 2035.
- Analyst View: We built the estimate from the number of active Phase 4 studies in the United States by indication, sponsor, and service type, multiplied by average cost per study and per patient, using trial registry data and sponsor and CRO spending. Study volumes reflect pipelines, approvals and regulatory requirements, while costs reflect trial size, complexity and duration.
The total was cross-checked against U.S. clinical trial market estimates and the reported phase mix, and against the revenues of leading CROs, which places our base year slightly above the highest credible comparable figure for Phase 4. The growth rate is based on evidence from pipeline and regulatory trends, moderated by efforts to control trial costs.
Market Trends
- Real-world evidence for regulatory decisions.
- Linked EHR and claims data.
- Long-term follow-up of gene therapies.
- Digital and remote data collection.
- Registries for rare diseases.
- Outsourced pharmacovigilance.
Drivers, Restraints and Opportunities
Driver
Regulators require post-approval data. Payers want real-world outcomes. Accelerated approvals need confirmation. Advanced therapies need long-term follow-up. Health data access improves.
Restraint
Data quality varies. Privacy rules limit data use. Studies compete for sponsor budgets. Fragmented health systems. Long study durations.
Opportunity
RWE for label expansion. Pragmatic trials in routine care. Patient-reported outcomes via apps. Rare disease registries. Integrated safety and evidence services.
Market Segmentation: 2025 Share and Size
U.S. Phase 4 Clinical Trials Market by Study Type 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Post-Marketing Safety Studies accounted for 36.40% with USD 2.04 billion in 2025; real-world evidence and observational studies for 31.20% with USD 1.75 billion, comparative effectiveness and label expansion for 18.80% with USD 1.05 billion, and registries and others for 13.60% with USD 0.76 billion.
Post-Marketing Safety Studies: This segment accounted for 36.40% with USD 2.04 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.75 billion by 2035, expanding at a CAGR of 6.28% from 2026 to 2035. Post-marketing safety studies, including post-authorisation safety studies and regulatory commitments, lead because regulators require many new medicines to collect further safety data after approval.
Real-World Evidence & Observational Studies: This segment accounted for 31.20% with USD 1.75 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 4.01 billion by 2035, expanding at a CAGR of 8.68% from 2026 to 2035. Real-world evidence and observational studies use electronic health records, claims, and registries to measure outcomes in routine care. They are the fastest-growing study type because regulators and payers increasingly accept and demand real-world evidence.
Comparative Effectiveness & Label Expansion: This segment accounted for 18.80% with USD 1.05 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.01 billion by 2035, expanding at a CAGR of 6.68% from 2026 to 2035. Comparative effectiveness and label expansion studies compare treatments in practice or test approved drugs in new populations and doses.
Registries & Others: This segment accounted for 13.60% with USD 0.76 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.45 billion by 2035, expanding at a CAGR of 6.68% from 2026 to 2035. Registries and others include disease and product registries, especially for rare diseases and long-term follow-up of cell and gene therapies.
U.S. Phase 4 Clinical Trials Market by Indication 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026–2035 |
| Oncology | 30.40% | 1.70 | 3.26 | 6.71% |
| Cardiovascular & Metabolic | 16.60% | 0.93 | 2.07 | 8.31% |
| Autoimmune & Inflammatory | 12.80% | 0.72 | 1.42 | 7.11% |
| CNS | 12.20% | 0.68 | 1.36 | 7.11% |
| Infectious Diseases | 8.40% | 0.47 | 0.93 | 7.11% |
| Others | 19.60% | 1.10 | 2.18 | 7.11% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Oncology accounted for 30.40% with USD 1.70 billion in 2025, cardiovascular and metabolic for 16.60% with USD 0.93 billion, autoimmune and inflammatory for 12.80% with USD 0.72 billion, CNS for 12.20% with USD 0.68 billion, infectious diseases for 8.40% with USD 0.47 billion, and others for 19.60% with USD 1.10 billion.
Oncology: This segment accounted for 30.40% (USD 1.70 billion) of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.26 billion by 2035, expanding at a CAGR of 6.71% from 2026 to 2035. Oncology is the largest indication because cancer drugs dominate late-stage pipelines, including immunotherapy combinations, antibody-drug conjugates, and targeted therapies, and oncology studies require long follow-up, imaging, and biomarker testing.
Cardiovascular & Metabolic: This segment accounted for 16.60% with USD 0.93 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.07 billion by 2035, expanding at a CAGR of 8.31% from 2026 to 2035. Cardiovascular and metabolic studies, including obesity, diabetes, heart failure, and kidney disease outcome trials, are the fastest-growing indication because incretin and other cardiometabolic drugs require very large, long trials and post-approval outcome evidence.
Autoimmune & Inflammatory: This segment accounted for 12.80% with USD 0.72 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.42 billion by 2035, expanding at a CAGR of 7.11% from 2026 to 2035. Autoimmune and inflammatory studies cover rheumatoid arthritis, inflammatory bowel disease, psoriasis, atopic dermatitis, and lupus, with many new biologics and oral drugs in development.
CNS: This segment accounted for 12.20% with USD 0.68 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.36 billion by 2035, expanding at a CAGR of 7.11% from 2026 to 2035. CNS studies include Alzheimer's disease, depression, schizophrenia, migraine, and pain, which require large patient numbers and complex endpoints.
Infectious Diseases: This segment accounted for 8.40% with USD 0.47 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 0.93 billion by 2035, expanding at a CAGR of 7.11% from 2026 to 2035. Infectious disease studies include vaccines, antivirals, and antibiotics, where large vaccine trials can involve tens of thousands of participants.
Others: This segment accounted for 19.60% with USD 1.10 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.18 billion by 2035, expanding at a CAGR of 7.11% from 2026 to 2035. Others include respiratory, renal, ophthalmology, dermatology, women's health, and rare disease studies.
U.S. Phase 4 Clinical Trials Market by Sponsor 2025 Share
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Pharmaceutical Companies accounted for 62.40% (USD 3.49 billion) in 2025, biotechnology companies for 28.60% with USD 1.60 billion, and medical devices and others for 9.00% (USD 0.50 billion).
Pharmaceutical Companies: This segment accounted for 62.40% with USD 3.49 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 6.70 billion by 2035, expanding at a CAGR of 6.75% from 2026 to 2035. Pharmaceutical companies are the largest sponsors, running large global programmes and outsourcing much of the work to CROs.
Biotechnology Companies: This segment accounted for 28.60% with USD 1.60 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.51 billion by 2035, expanding at a CAGR of 8.15% from 2026 to 2035. Biotechnology companies are the fastest-growing sponsors because many late-stage assets now originate in biotech, and these companies rely heavily on full-service CROs.
Medical Device & Others: This segment accounted for 9.00% with USD 0.50 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.01 billion by 2035, expanding at a CAGR of 7.15% from 2026 to 2035. Medical device companies and others, including academic and government sponsors, run pivotal and post-market device studies and investigator-initiated trials.
U.S. Phase 4 Clinical Trials Market by Service Type 2025 Share & Size
| Segments | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026–2035 |
| Site Management & Monitoring | 30.20% | 1.69 | 3.15 | 6.43% |
| Data Management & RWD Analytics | 22.60% | 1.27 | 2.95 | 8.83% |
| Pharmacovigilance & Safety Reporting | 18.40% | 1.03 | 2.00 | 6.83% |
| Patient Recruitment | 14.40% | 0.81 | 1.56 | 6.83% |
| Others | 14.40% | 0.81 | 1.56 | 6.83% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Site Management and Monitoring accounted for 30.20% with USD 1.69 billion in 2025; data management and RWD analytics for 22.60% with USD 1.27 billion; pharmacovigilance and safety reporting for 18.40% with USD 1.03 billion; patient recruitment for 14.40% with USD 0.81 billion; and others for 14.40% with USD 0.81 billion.
Site Management & Monitoring: This segment accounted for 30.20% with USD 1.69 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.15 billion by 2035, expanding at a CAGR of 6.43% from 2026 to 2035. Site management and monitoring is the largest service, covering site selection, activation, investigator payments, and on-site and risk-based monitoring.
Data Management & RWD Analytics: This segment accounted for 22.60% with USD 1.27 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.95 billion by 2035, expanding at a CAGR of 8.83% from 2026 to 2035. Data management and real-world data analytics are the fastest-growing services as studies rely more on linked health data, tokenisation, and advanced analytics.
Pharmacovigilance & Safety Reporting: This segment accounted for 18.40% with USD 1.03 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.00 billion by 2035, expanding at a CAGR of 6.83% from 2026 to 2035. Pharmacovigilance and safety reporting include adverse event collection, signal detection, and periodic safety reports.
Patient Recruitment: This segment accounted for 14.40% with USD 0.81 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.56 billion by 2035, expanding at a CAGR of 6.83% from 2026 to 2035. Patient recruitment for Phase 4 studies uses physician networks, patient communities, and digital channels.
Others: This segment accounted for 14.40% with USD 0.81 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.56 billion by 2035, expanding at a CAGR of 6.83% from 2026 to 2035. Others include medical writing, regulatory support, health economics and outcomes research, and project management.
Analyst View: Segment values were allocated by matching study volumes and costs to study type, indication, sponsor, and service type, using trial registry data and CRO revenue mixes. Safety studies, oncology, pharmaceutical sponsors, and site management lead, while real-world evidence studies, cardiometabolic research, and data analytics gain share.
Country Analysis
U.S. Phase 4 Clinical Trials Market by Country 2025 Share
| Country | 2025 Share | 2025 Value (USD Billion) | 2035 Value (USD Billion) | CAGR 2026–2035 |
| Northeast | 31.40% | 1.76 | 3.38 | 6.74% |
| South | 30.20% | 1.69 | 3.56 | 7.74% |
| West | 22.80% | 1.28 | 2.54 | 7.14% |
| Midwest | 15.60% | 0.87 | 1.74 | 7.14% |
Note: 2025 is the base year; 2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The Northeast accounted for 31.40% with USD 1.76 billion in 2025, the South for 30.20% with USD 1.69 billion, the West for 22.80% with USD 1.28 billion, and the Midwest for 15.60% with USD 0.87 billion. The Northeast leads, while the South is growing fastest.
Northeast: This region accounted for 31.40% with USD 1.76 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.38 billion by 2035, expanding at a CAGR of 6.74% from 2026 to 2035. The Northeast has the densest concentration of sponsors, academic medical centres and investigative sites in Boston, New York, New Jersey and Philadelphia.
South: This region accounted for 30.20% with USD 1.69 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 3.56 billion by 2035, expanding at a CAGR of 7.74% from 2026 to 2035. The South, including Texas, Florida, North Carolina, and Georgia, has large and diverse patient populations, many independent research sites, and growing CRO operations. It is the fastest-growing region as sponsors seek faster enrolment and more diverse participants.
West: This region accounted for 22.80% with USD 1.28 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 2.54 billion by 2035, expanding at a CAGR of 7.14% from 2026 to 2035. The West includes California's biotech hubs in the San Francisco Bay Area and San Diego, and major medical centres in Los Angeles and Seattle.
Midwest: This region accounted for 15.60% with USD 0.87 billion of the U.S. Phase 4 clinical trials market in 2025 and is projected to reach USD 1.74 billion by 2035, expanding at a CAGR of 7.14% from 2026 to 2035. The Midwest has large health systems and academic centres such as the Mayo Clinic, Cleveland Clinic and university hospitals, and growing community research networks.
Analyst View: Regional shares were built from active study sites and spending in each region. The Northeast leads because of its sponsor and academic base. We assign the South the highest growth premium because sponsors are expanding there for faster and more diverse enrolment.
Competitive Landscape
Top 10 Companies in the U.S. Phase 4 Clinical Trials Market, 2025
| Rank | Company Name | Market-Specific Revenue (USD Billion) | 2025 Share | Key Products / Business | Headquarters |
| 1 | IQVIA | 0.85 | 15.18% | Real-world evidence and late-phase studies | United States |
| 2 | Thermo Fisher (PPD) | 0.45 | 8.04% | PPD and Evidera real-world evidence | United States |
| 3 | ICON | 0.40 | 7.14% | Late-phase and real-world studies | Ireland |
| 4 | Parexel | 0.30 | 5.36% | Real-world and late-phase research | United States |
| 5 | Syneos Health | 0.25 | 4.46% | Late-phase and commercial solutions | United States |
| 6 | Optum Life Sciences | 0.20 | 3.57% | Real-world data and studies | United States |
| 7 | Fortrea | 0.15 | 2.68% | Late-phase services | United States |
| 8 | Medpace | 0.10 | 1.79% | Post-approval studies | United States |
| 9 | Aetion | 0.05 | 0.89% | Real-world evidence platform | United States |
| 10 | OM1 | 0.04 | 0.71% | Real-world data and registries | United States |
Note: Company revenues and shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
IQVIA led the U.S. Phase 4 clinical trials market with an estimated 15.18% share, with USD 0.85 billion of 2025 revenue, followed by Thermo Fisher (PPD) at 8.04% with USD 0.45 billion and ICON at 7.14% with USD 0.40 billion. IQVIA leads with the largest real-world data assets and late-phase study capabilities in the United States. Thermo Fisher's PPD and Evidera businesses and ICON follow with late-phase and real-world evidence services. Parexel, Syneos Health, Optum Life Sciences, Fortrea, Medpace, Aetion and OM1 compete through late-phase research, commercial solutions, claims and EHR data, post-approval services and real-world evidence platforms.
The top 10 companies accounted for an estimated 49.82% with USD 2.79 billion of 2025 revenue, while the remaining 50.18% with USD 2.81 billion was shared among smaller CROs, site networks, academic research organisations and in-house sponsor teams. The U.S. Phase 4 clinical trials market is moderately concentrated among large CROs, and competition centres on therapeutic expertise, site networks, recruitment speed, data and technology platforms, regulatory experience, quality and price. Sponsors increasingly use strategic partnerships with a few full-service providers.
Companies Ecosystem
The U.S. Phase 4 clinical trials ecosystem links sponsors with CROs, site networks, technology and data providers, central laboratories, regulators, ethics committees and patients.
| Ecosystem Stage | Role in the Market | Key Companies |
| Sponsors | Fund and design studies | Pharma, biotech and device companies |
| CROs | Run outsourced studies | IQVIA, ICON, Thermo Fisher (PPD), Parexel, Syneos Health, Medpace |
| Sites & Investigators | Enrol and treat patients | Hospitals, academic centres, site networks |
| Technology & Data | Provide EDC, eCOA and real-world data | Medidata, Oracle, Veeva, data providers |
| Regulators & Ethics | Approve and oversee studies | FDA, EMA, national authorities, IRBs and ethics committees |
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Precedence Research Companies Quadrant
The Precedence Research Companies Quadrant positions key participants in the U.S. Phase 4 clinical trials market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 revenue in this market and our assessment of its technology, therapeutic expertise and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Leaders: IQVIA, Thermo Fisher (PPD), ICON, Parexel, Syneos Health and Optum Life Sciences combine large revenue with global reach, broad therapeutic expertise and data and technology platforms.
Challengers: Fortrea has large operations but is restructuring or less differentiated.
Innovators: Medpace and Aetion bring specialised therapeutic focus or real-world data capabilities.
Niche Players: OM1 serves narrower regional or therapeutic segments.
Recent Developments
- In December 2025, the FDA published final guidance on the use of real-world evidence to support regulatory decision-making for medical devices, replacing its 2017 guidance and clarifying how real-world data quality is assessed.
U.S. Phase 4 Clinical Trials Market Segments
By Study Type
- Post-Marketing Safety Studies
- Real-World Evidence & Observational Studies
- Comparative Effectiveness & Label Expansion
- Registries & Others
By Indication
- Oncology
- Cardiovascular & Metabolic
- Autoimmune & Inflammatory
- CNS
- Infectious Diseases
- Others
By Sponsor
- Pharmaceutical Companies
- Biotechnology Companies
- Medical Device & Others
By Service Type
- Site Management & Monitoring
- Data Management & RWD Analytics
- Pharmacovigilance & Safety Reporting
- Patient Recruitment
- Others
By Country
- Northeast
- South
- West
- Midwest
Research Methodology
The U.S. Phase 4 clinical trials market was defined as Phase 4 post-marketing, real-world evidence, label-expansion, and registry study spending, including sponsor and outsourced services, in the United States. The 2025 base year was built bottom-up from active Phase 4 studies, patients and costs by indication, sponsor, service type and region, and checked top-down against published clinical trial market estimates by phase and the revenues of leading CROs.
Segment, regional and company values were allocated from indications, sponsors, services and regional study activity. Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: Overall Market
The U.S. Phase 4 clinical trials market is growing faster than overall clinical spending as regulators and payers demand evidence beyond approval. Our estimate links demand to study volumes and costs, so the forecast follows approvals, regulatory requirements and real-world data access. The main upside comes from real-world evidence and advanced therapy follow-up, while the main risks are data quality and privacy constraints.
Sources and References
- Federal Register. "Use of Real-World Evidence to Support Regulatory Decision-Making for Medical Devices; Guidance for Industry and FDA Staff". December 2025. Regulatory notice. https://www.govinfo.gov/content/pkg/FR-2025-12-18/html/2025-23252.htm
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting