



North America Bioprocessing Technology Market Revenue, Leading Companies, Company Technology / Innovation, Diagnostic Testing Volume, Adoption Rates, Pricing Metrics, Supply Chain Performance, Competitive Positioning, and Industry Trends
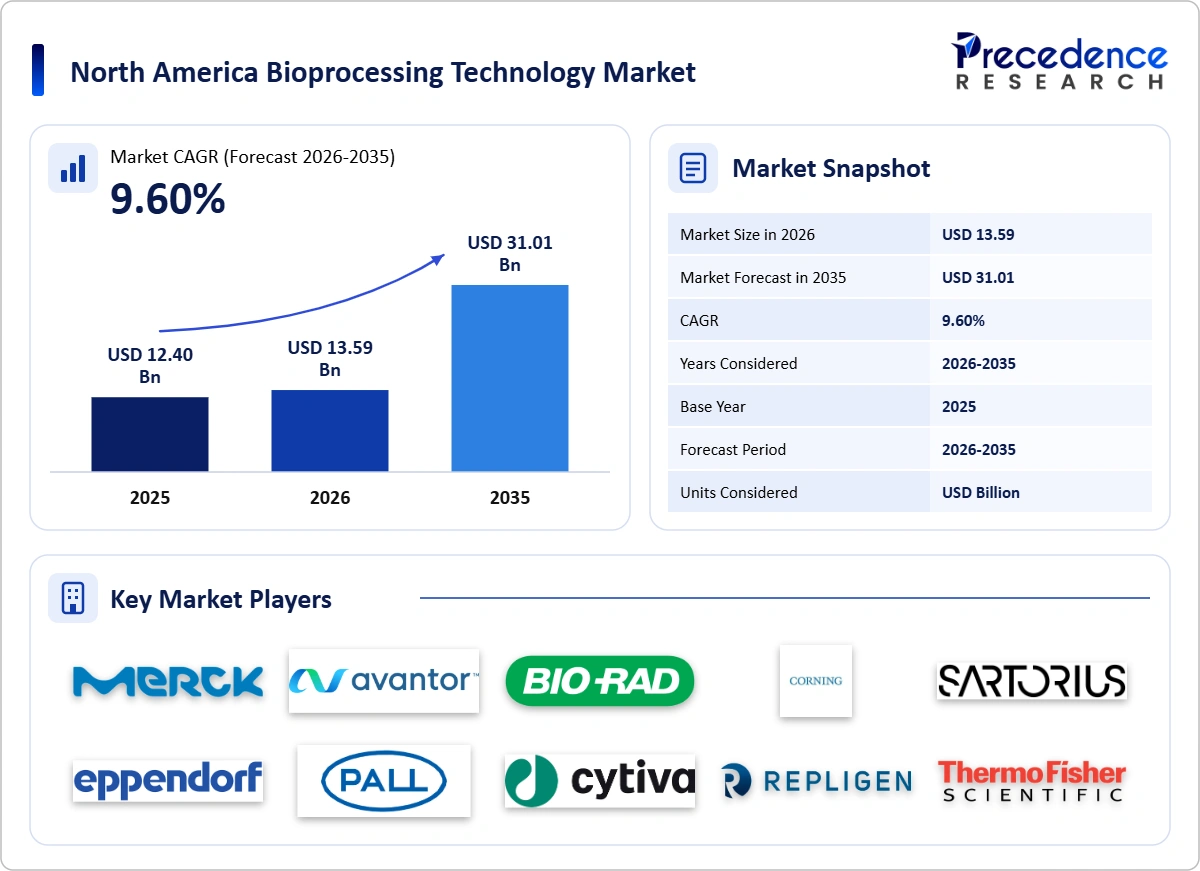
Payal Rabde, a Healthcare Industry Expert, highlights that the North America bioprocessing technology market has reached USD 13.59 billion in 2026 and is on track to reach USD 31.01 billion by 2035, advancing at a CAGR of 9.60%. Key North America bioprocessing technology market companies shaping the market include Thermo Fisher Scientific, Cytiva (Danaher), Merck KGaA (MilliporeSigma while major growth segments span product, process stage, application, end user and region.
Source: https://www.precedenceresearch.com/north-america-bioprocessing-technology-market
 Get a Sample
 Table Of Content
Key Takeaways
Market Size & Growth Outlook
- Market size in 2025: USD 12.40 billion
- Estimated market size in 2026: USD 13.59 billion
- Projected market size by 2035: USD 31.01 billion
- CAGR (2026-2035): 9.60%
Country Market Insights
- The U.S. led the market with the largest share of 88.00% in 2025.
- Canada accounted for 8.00% of the market share in 2025.
- Mexico held a 4.00% share in 2025 and is projected to be the fastest-growing country, at a CAGR of 11.10% from 2026 to 2035.
Segmental Highlights
- By product, Consumables & Single-Use Systems accounted for the largest share of 44.00% in 2025.
- By process stage, the Upstream Processing segment captured a 46.00% share in 2025.
- By application, Monoclonal Antibodies held 48.00% of the market in 2025.
- By end user, Biopharmaceutical Companies contributed 58.00% market share in 2025.
North America Bioprocessing Technology Market Size and Forecast, 2025-2035 (USD Billion)
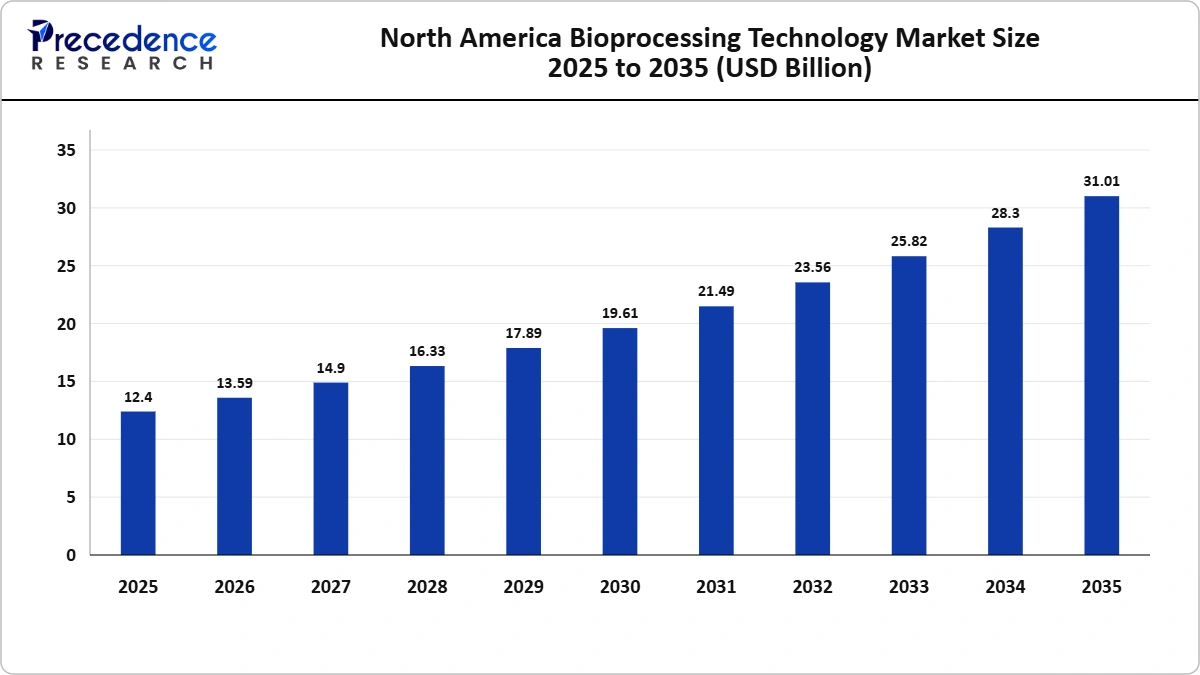
Note: 2025 is the base year; 2026-2035 values are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
The North America bioprocessing technology market is anticipated to grow from USD 12.40 billion in 2025 to USD 31.01 billion by 2035 because North America is the world's largest biologics manufacturing base, and every new antibody, vaccine, and cell therapy plant needs bioprocess equipment and consumables. Biologics pipelines, onshoring investments, CDMO expansion, cell and gene therapy scale-up, and single-use adoption support strong growth, lifting the market to USD 19.61 billion by 2030 and sustaining a CAGR of 9.60% from 2026 to 2035. Bioprocessing demand rises with regenerative medicine and cell therapy programs moving from clinical trials to commercial production.
Analyst View: North America's established biologics manufacturing ecosystem, rising investments in domestic production, and expanding CDMO capacity are driving demand for advanced bioprocessing technologies. Regenerative medicine applications, expanding pipelines for cell and gene therapy, and the move to single-use systems are all contributing to the market's growth and setting the region up for long-term growth.
Market Trends
- Single-use technologies are gaining wider adoption across clinical and commercial manufacturing plants.
- Continuous and intensified processing are improving manufacturing efficiency, productivity, and scalability.
- Process analytical technology and digital twins are enabling better process monitoring, control, and optimization.
- Onshoring initiatives are accelerating domestic biologics manufacturing capacity.
- Growing viral vector and cell therapy pipelines are driving demand for advanced bioprocessing solutions.
- Manufacturers are increasingly adopting dual-sourcing strategies to strengthen supply-chain resilience.
Market Dynamics
Driver
Growing biologics pipelines and biosimilar production are increasing demand for bioprocessing technologies, while onshoring initiatives are driving investments in new manufacturing facilities. Simultaneously, the adoption of single-use systems and the growth of cell and gene therapies are boosting market expansion by decreasing changeover time and increasing manufacturing flexibility.
Restraint
High capital investment requirements and supply bottlenecks for critical consumables continue to challenge market expansion. These challenges are further compounded by skilled labor shortages and environmental concerns associated with single-use plastic waste.
Opportunity
Advancements in continuous processing and process analytics are creating opportunities to improve manufacturing efficiency and process control.
Furthermore, it is anticipated that developing recyclable single-use materials, boosting viral vector production capacity, and growing biosimilar production in Mexico would create new potential opportunities for market players.
Market Drivers - Impact & CAGR Contribution (2026-2035)
| Driver | Impact | ≈ CAGR Contribution | Time Horizon | Key Regions |
| Biologics pipelines grow | High | +3.75 pp | Short to long term | North America-wide, strongest in U.S. |
| Biosimilars expand | Medium | +3.16 pp | Medium to long term | North America-wide, fastest uptake in Mexico |
| Onshoring adds plants | Medium | +2.69 pp | Short to medium term | North America-wide |
| Cell and gene therapies scale up | Low | +2.11 pp | Long term | U.S. and Mexico |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Taken together, these drivers add about 11.71 percentage points to the annual growth of the North America bioprocessing technology market, with biologics pipeline growth having the largest effect. Their influence is strongest in the U.S., while uptake grows fastest in Mexico.
Market Restraints - Impact & Negative CAGR Contribution (2026-2035)
| Restraint | Impact | ≈ Negative CAGR Contribution | Time Horizon | Key Regions |
| High capital costs | High | -0.95 pp | Short to medium term | North America-wide |
| Supply bottlenecks for consumables | High | -0.70 pp | Medium term | Smaller and price-sensitive markets |
| Skilled labor shortages | Medium | -0.46 pp | Short term | U.S. and other mature markets |
Note: Contributions are indicative estimates of each factor's effect on annual growth.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
These restraints are expected to reduce annual growth of the North America bioprocessing technology market by about 2.11 percentage points, led by high capital costs. Their effect eases over the forecast period as suppliers, buyers, and regulators adapt, leaving a net CAGR of 9.60% from 2026 to 2035.
Market Segmentation: 2025 Share and Size
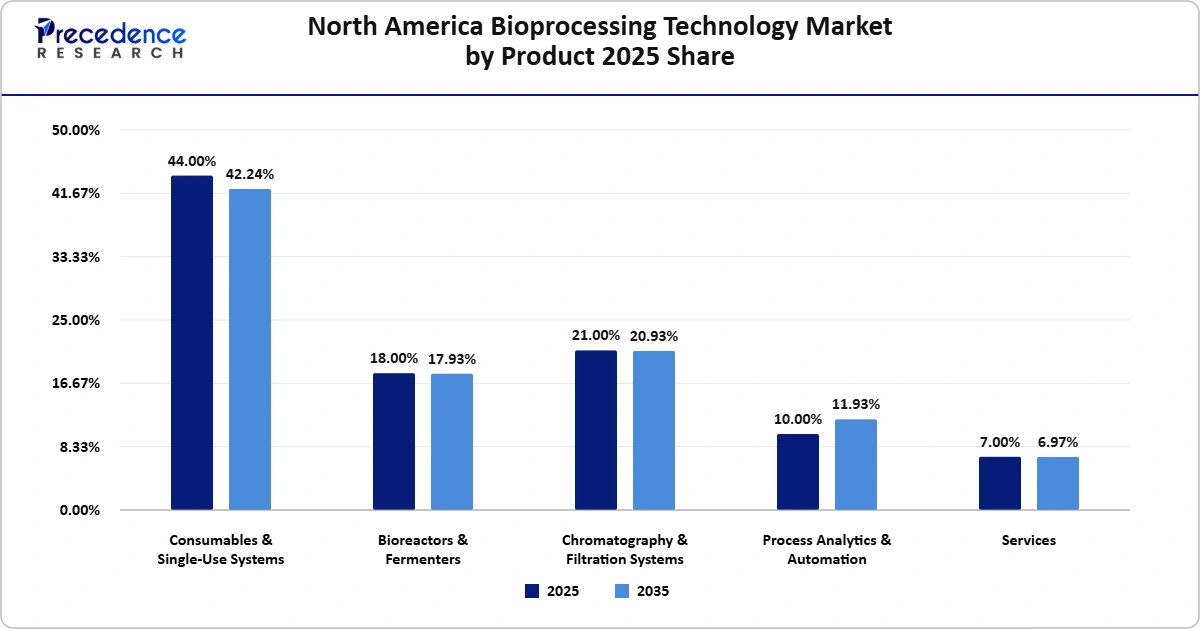
North America Bioprocessing Technology Market by Product 2025 Share
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Consumables & Single-Use Systems accounted for 44.00% in 2025, Bioreactors & Fermenters for 18.00%, Chromatography & Filtration Systems for 21.00%, Process Analytics & Automation for 10.00%, and Services for 7.00%. Consumables & Single-Use Systems lead, while Process Analytics & Automation is growing fastest.
Consumables & Single-Use Systems: The segment captured 44.00% of the market in 2025 and is forecast to register a CAGR of 9.16% during 2026-2035. Consumables & single-use systems lead because every batch uses new bags, tubing, filters, media, and resins, creating recurring purchases. The consumables & single-use systems segment is expected to grow slower than the overall market over the forecast period.
Bioreactors & Fermenters: The segment captured 18.00% of the total market in 2025 and is anticipated to register a CAGR of 9.56% between 2026 and 2035. Bioreactors & fermenters are core capital equipment for cell culture and microbial production. The bioreactors & fermenters segment is expected to grow broadly in line with the overall market over the forecast period.
Chromatography & Filtration Systems: Representing 21.00% of the market in 2025, this segment is forecast to maintain steady growth at a CAGR of 9.56% over the forecast period. Chromatography & filtration systems purify antibodies, proteins, and viral vectors. The chromatography & filtration systems segment is expected to expand broadly in line with the overall market between 2026 and 2035.
Process Analytics & Automation: This segment accounted for 10.00% of the North America bioprocessing technology market in 2025 and is projected to expand at a CAGR of 11.56% from 2026 to 2035. Process analytics & automation grow fastest as plants adopt real-time monitoring and digital control. The process analytics & automation segment is expected to grow faster than the overall market during the forecast period.
The Services segment accounted for 7.00% of the market share in 2025 and is estimated to expand at a CAGR of 9.56% during the forecast period. Services include validation, process development support, and maintenance. The services segment is expected to grow broadly in line with the overall market over the forecast period.
Segment Outlook: Consumables & Single-Use Systems remain the largest product segment through 2035, holding about 42.24% of the market in 2035, while Process Analytics & Automation records the highest CAGR of 11.56% from 2026 to 2035. Services hold the smallest share and serve more specialized needs within the North America bioprocessing technology market.
North America Bioprocessing Technology Market by Process Stage 2025 Share
| Segments | 2025 Share | 2035 Share | CAGR 2026-2035 |
| Upstream Processing | 46.00% | 46.89% | 9.81% |
| Downstream Processing | 42.00% | 41.31% | 9.41% |
| Fill-Finish Support | 12.00% | 11.80% | 9.41% |
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Upstream Processing captured 46.00% in 2025, Downstream Processing at 42.00%, and Fill-Finish Support at 12.00%. Upstream Processing leads and is also growing the fastest.
Upstream Processing: The segment held a substantial 46.00% share of the market in 2025, with its growth projected at a CAGR of 9.81% from 2026 to 2035. Upstream processing leads because cell expansion and production use bioreactors, media, and sensors. The upstream processing segment is expected to grow fastest in line with the overall market during the forecast period.
Downstream Processing: Representing 42.00% of the market in 2025, this segment is forecast to maintain steady growth at a CAGR of 9.41% over the forecast period. Downstream processing covers capture, purification, and polishing. The downstream processing segment is expected to grow broadly in line with the overall market from 2026 to 2035.
Fill-Finish Support: This segment captured 12.00% of the North America bioprocessing technology market in 2025 and is projected to grow at a CAGR of 9.41% from 2026 to 2035. Fill-finish support grows with sterile filtration and single-use transfer systems. The fill-finish support segment is estimated to expand broadly in line with the overall market over the forecast period.
Segment Outlook: Upstream Processing remains the largest process stage segment through 2035, holding about 46.89% of the market in 2035, and also records the highest CAGR of 9.81% from 2026 to 2035, strengthening its lead in the North America bioprocessing technology market.
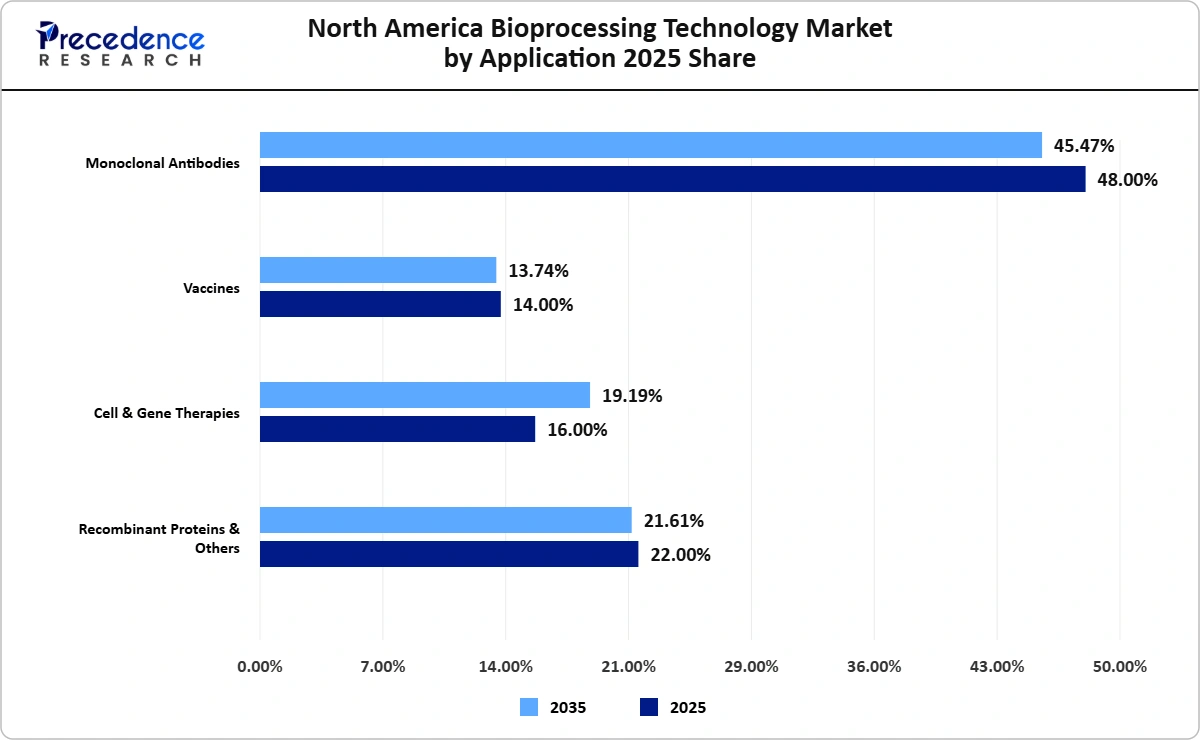
North America Bioprocessing Technology Market by Application 2025 Share
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Monoclonal Antibodies accounted for 48.00% in 2025, Vaccines for 14.00%, Cell & Gene Therapies for 16.00%, and Recombinant Proteins & Others for 22.00%. Monoclonal Antibodies lead, while Cell & Gene Therapies is growing the fastest.
Monoclonal Antibodies: With a market contribution of 48.00% in 2025, the segment is expected to witness sustained expansion at a CAGR of 9.00% from 2026 to 2035. Monoclonal antibodies lead because they are the largest class of biologics made in North America. The monoclonal antibodies segment is expected to grow slower than the overall market over the forecast period.
Vaccines: This segment contributed 14.00% market share in 2025 and is expected to expand at a CAGR of 9.40% over the forecast period. Vaccines use large-scale cell culture and purification. The vaccines segment is projected to grow broadly in line with the overall market during the forecast period.
Cell & Gene Therapies: Holding a 16.00% market share in 2025, this segment is estimated to grow at a CAGR of 11.60% during the forecast period. Cell & gene therapies grow fastest as viral vector and cell therapy plants expand. The cell & gene therapies segment is projected to expand faster than the overall market over the forecast period.
Recombinant Proteins & Others: This segment contributed 22.00% of the North America bioprocessing technology market in 2025 and is projected to expand at a CAGR of 9.40% from 2026 to 2035. Recombinant proteins, peptides, enzymes, and other biologics complete demand. The recombinant proteins & others segment is expected to grow broadly in line with the overall market over the forecast period.
Segment Outlook: Monoclonal Antibodies remain the largest application segment through 2035, holding about 45.47% of the market in 2035, while Cell & Gene Therapies record the highest CAGR of 11.60% from 2026 to 2035. Vaccines hold the smallest share and serve more specialized needs within the North America bioprocessing technology market.
North America Bioprocessing Technology Market by End User 2025 Share
| Segments | 2025 Share | 2035 Share | CAGR 2026-2035 |
| Biopharmaceutical Companies | 58.00% | 54.66% | 8.95% |
| CDMOs & CMOs | 30.00% | 33.60% | 10.85% |
| Academic & Research Institutes | 12.00% | 11.74% | 9.35% |
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Biopharmaceutical Companies held 58.00% in 2025, CDMOs & CMOs at 30.00%, and Academic & Research Institutes at 12.00%. Biopharmaceutical Companies lead, while CDMOs & CMOs are growing fastest.
Biopharmaceutical Companies: In 2025, the segment represented 58.00% of the market share and is expected to achieve a CAGR of 8.95% over the forecast period. Biopharmaceutical companies lead because they run most commercial and clinical biologics plants. The biopharmaceutical companies segment is projected to grow slower than the overall market between 2026 and 2035.
CDMOs & CMOs: The segment's market share stood at 30.00% in 2025, while its growth trajectory is expected to reflect a CAGR of 10.85% during 2026-2035. CDMOs & CMOs grow fastest as drug developers outsource production. The CDMOs & CMOs segment is expected to grow faster than the overall market over the forecast period.
Academic & Research Institutes: This segment accounted for 12.00% of the North America bioprocessing technology market in 2025 and is projected to expand at a CAGR of 9.35% from 2026 to 2035. Academic & research institutes use bioprocess tools for process science and early development. The academic & research institutes segment is expected to grow broadly in line with the overall market during the forecast period.
Segment Outlook: Biopharmaceutical Companies remain the largest end user segment through 2035, holding about 54.66% of the market in 2035, while CDMOs & CMOs record the highest CAGR of 10.85% from 2026 to 2035. Academic & Research Institutes hold the smallest share and serve more specialized needs within the North America bioprocessing technology market.
Analyst View: The market is led by consumables & single-use systems, while process analytics & automation are gaining traction through increased digitalization. Upstream processing dominates due to rising demand for cell growth and bioreactor capacity. Monoclonal antibodies lead by application, while cell and gene therapies are emerging as fast-growing areas. Biopharmaceutical companies remain the leading end users, although CDMOs and CMOs are gaining momentum through increased outsourcing and manufacturing expansion.
Country Analysis
North America Bioprocessing Technology Market by Country 2025 Share
| Country | 2025 Share | 2035 Share | CAGR 2026-2035 |
| U.S. | 88.00% | 87.20% | 9.50% |
| Canada | 8.00% | 8.22% | 9.90% |
| Mexico | 4.00% | 4.58% | 11.10% |
Note: 2025 is the base year; 2035 shares and CAGRs are forecasts.
Sources: Expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
U.S. accounted for 88.00% in 2025, Canada for 8.00%, and Mexico for 4.00%. U.S. leads, while Mexico is growing fastest.
U.S.: Representing 88.00% of the market in 2025, this country is forecast to maintain steady growth at a CAGR of 9.50% over the forecast period. The U.S. leads because it hosts the largest base of biologics plants, CDMOs, and bioprocess suppliers, with clusters in Massachusetts, North Carolina, California, and New Jersey, and new onshoring investments. U.S. is expected to grow broadly in line with the overall market between 2026 and 2035.
Canada: This country captured 8.00% of the North America bioprocessing technology market in 2025 and is expected to grow at a CAGR of 9.90% from 2026 to 2035. Canada is supported by vaccine and biologics capacity in Ontario and Quebec and federal biomanufacturing programs. Canada is projected to expand faster than the overall market over the forecast period.
Mexico: With a market contribution of 4.00% in 2025, the country is expected to witness sustained expansion at a CAGR of 11.10% from 2026 to 2035. Mexico grows fastest as biosimilar makers and contract manufacturers add capacity. Mexico is estimated to grow faster than the overall market between 2026 and 2035.
Analyst View: The U.S. dominates the North American market, supported by its established biologics manufacturing base, extensive CDMO network, and continued onshoring investments. Government-backed biomanufacturing projects help Canada grow its production of vaccines and biologics. Meanwhile, growing contract manufacturing capacity and biosimilar production are driving Mexico's emergence as a high-growth market.
Competitive Landscape
Top Companies in the North America Bioprocessing Technology Market, 2025
| Rank | Company Name | Key Products / Business | Headquarters |
| 1 | Thermo Fisher Scientific | Single-use bioreactors, media, purification and bioprocess services | United States |
| 2 | Cytiva (Danaher) | Bioreactors, chromatography resins and systems, single-use and filtration | United States |
| 3 | Merck KGaA (MilliporeSigma) | Filtration, single-use assemblies, media and process solutions | Germany |
| 4 | Sartorius | Bioreactors, single-use bags, filters and process analytics | Germany |
| 5 | Pall (Danaher) | Filtration and single-use systems | United States |
| 6 | Repligen | TFF and ATF filtration, chromatography columns and process analytics | United States |
| 7 | Avantor | Process chemicals, single-use components and bioprocess consumables | United States |
| 8 | Corning | Cell culture vessels and media | United States |
| 9 | Eppendorf | Benchtop and pilot bioreactors | Germany |
| 10 | Bio-Rad Laboratories | Chromatography resins for process purification | United States |
Note: Company shares are 2025 estimates.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Thermo Fisher Scientific led the North America bioprocessing technology market, followed by Cytiva (Danaher) and Merck KGaA (MilliporeSigma). Thermo Fisher Scientific leads with single-use bioreactors, media, purification, and bioprocess services; Cytiva (Danaher) competes with bioreactors, chromatography resins and systems, single-use and filtration, and Merck KGaA (MilliporeSigma) offers filtration, single-use assemblies, media and process solutions. Sartorius, Pall (Danaher), Repligen, Avantor, Corning, Eppendorf, and Bio-Rad Laboratories compete through a broad portfolio of bioprocessing solutions, including bioreactors, single-use bags, filtration systems, TFF and ATF technologies, and chromatography columns. Their offerings also include process analytics, process chemicals, bioprocess consumables, cell culture vessels and media, benchtop and pilot-scale bioreactors, and chromatography resins for process purification.
The North America bioprocessing technology market is moderately concentrated, and competition centers on single-use portfolios, supply security, regulatory documentation, process development support, digital integration, and total cost of production.
Company Snapshots
Thermo Fisher Scientific: Headquartered in the United States. Its offering centers on Single-use bioreactors, media, purification, and bioprocess services. In the Precedence Research Companies Quadrant, it is positioned as a Leader.
Cytiva (Danaher): The company is headquartered in the United States. Its offering centers on Bioreactors, chromatography resins and systems, single-use, and filtration. It is positioned as a Leader in the Precedence Research Companies Quadrant.
Merck KGaA (MilliporeSigma): Company offerings center on Filtration, single-use assemblies, media, and process solutions. In the Precedence Research Companies Quadrant, it is categorized as a Leader.
Sartorius: Headquartered in Germany, Sartorius specializes in bioreactors, single-use bags, filtration solutions, and process analytics. The company is classified as a Leader in the Precedence Research Companies Quadrant.
Pall (Danaher): United States-based, this company's offerings center on Filtration and single-use systems. Positioning it as a Leader in the Precedence Research Companies Quadrant.
Repligen: Headquartered in the United States, Repligen specializes in bioprocessing solutions, with a portfolio spanning TFF and ATF filtration technologies, chromatography columns, and process analytics. The company is recognized as a Leader in the Precedence Research Companies Quadrant.
Avantor: Its offering centers on Process chemicals, single-use components, and bioprocess consumables. In the Precedence Research Companies Quadrant, it is positioned as an Innovator.
Corning: Corning is headquartered in the United States. The company specializes in cell culture vessels and media solutions, earning an Innovator position in the Precedence Research Companies Quadrant.
Eppendorf: The company is based in Germany. Its offerings center on Benchtop and pilot bioreactors. In the Precedence Research Companies Quadrant, it is positioned as an Innovator.
Bio-Rad Laboratories: Bio-Rad Laboratories is headquartered in the United States. Its offering centers on Chromatography resins for process purification. In the Precedence Research Companies Quadrant, it is positioned as an Innovator.
Companies Ecosystem
The North America bioprocessing technology ecosystem links raw material & component suppliers, bioprocess technology providers, distributors & integrators, manufacturers & CDMOs, and regulators, with each stage adding value before products reach end users. Enzymes and media components are key inputs for upstream processing.
| Ecosystem Stage | Role in the Market | Key Companies |
| Raw Material & Component Suppliers | Supply films, resins, media components, and sensors | Resin, polymer film and sensor makers |
| Bioprocess Technology Providers | Make bioreactors, filters, chromatography, and single-use systems | Thermo Fisher, Cytiva, MilliporeSigma, Sartorius, Repligen |
| Distributors & Integrators | Supply and integrate equipment | Avantor, Fisher Scientific, system integrators |
| Manufacturers & CDMOs | Run biologics production | Biopharma companies, CDMOs, CMOs |
| Regulators | Approve processes and facilities | FDA, Health Canada, COFEPRIS |
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database, and Precedence Research analysts.
Raw Material & Component Suppliers: Supply films, resins, media components, and sensors. Key participants include Resin, polymer film, and sensor makers.
Bioprocess Technology Providers: Make bioreactors, filters, chromatography, and single-use systems. Key participants include Thermo Fisher, Cytiva, MilliporeSigma, Sartorius, and Repligen.
Distributors & Integrators: Supply and integrate equipment. Key participants include Avantor, Fisher Scientific, and system integrators.
Manufacturers & CDMOs: Run biologics production. Key participants include Biopharma companies, CDMOs, and CMOs.
Regulators: Approve processes and facilities. Key participants include FDA, Health Canada, and COFEPRIS.
Value in the North America bioprocessing technology market flows from upstream material and technology suppliers to manufacturers and service providers, then through distribution partners to end users. Companies that integrate several stages or build long-term relationships with end users capture a larger share of this value.
Precedence Research Companies Quadrant
The Precedence Research Companies Quadrant positions key participants in the North America bioprocessing technology market by market strength, reflecting revenue scale, market share and geographic reach, and by innovation and growth strategy, reflecting product portfolio breadth, R&D intensity and partnerships. Positions reflect each company's estimated 2025 share of the North America bioprocessing technology market and our assessment of its product innovation, portfolio breadth and partnerships.
Sources: Company press releases, expert interviews, secondary sources, Precedence Research database and Precedence Research analysts.
Leaders: Thermo Fisher Scientific, Cytiva (Danaher), Merck KGaA (MilliporeSigma), Sartorius, Pall (Danaher), and Repligen combine high market share with broad portfolios and strong innovation.
Innovators: Avantor, Corning, Eppendorf, and Bio-Rad Laboratories bring newer technologies and specialized products.
Recent Developments
- April 2026: Thermo Fisher Scientific opened its flagship U.S. Bioprocess Design Center in Plainville, Massachusetts, adding 4,000 square feet of laboratory space. The facility provides hands-on support across media, cell line development, filtration, purification, chromatography, and analytics to help customers optimize bioprocesses and scale up biologics and advanced therapies.
- June 2025: Cytiva completed projects under its USD 1.6 billion global manufacturing investment, including capacity additions in the United States. The investments strengthen production capacity for chromatography resins, filtration systems, single-use bags, and cell culture media, supporting supply-chain resilience and growing bioprocessing demand.
North America Bioprocessing Technology Market Segments
By Product
- Consumables & Single-Use Systems
- Bioreactors & Fermenters
- Chromatography & Filtration Systems
- Process Analytics & Automation
- Services
By Process Stage
- Upstream Processing
- Downstream Processing
- Fill-Finish Support
By Application
- Monoclonal Antibodies
- Vaccines
- Cell & Gene Therapies
- Recombinant Proteins & Others
By End User
- Biopharmaceutical Companies
- CDMOs & CMOs
- Academic & Research Institutes
By Country
- U.S.
- Canada
- Mexico
Research Methodology: The North America bioprocessing technology market was defined as equipment, consumables, software, and services used to develop and manufacture biologics in the United States, Canada, and Mexico, including bioreactors and fermenters, cell culture media and reagents, chromatography and filtration systems, single-use assemblies, process analytics and automation, used in upstream and downstream processing by biopharmaceutical companies, CDMOs and CMOs, and academic and research institutes.
The 2025 base year was built bottom-up from demand volumes and average prices by product, process stage, application and end user, and region, and checked top-down against the market-specific revenues of leading companies and published estimates. Segment, country and company values were allocated from product, process stage, application and end user and country demand.
Key estimates were verified by cross-checking company disclosures, regulatory and industry data and published third-party estimates, and inputs that could not be reconciled were excluded. All segment, regional, and company figures were reconciled to the same 2025 base year, and the 2026-2035 forecast, which applies a constant CAGR from the 2025 base, was recalculated and validated.
Analyst View: The North America bioprocessing technology market is poised for sustained growth, driven by expanding biologics pipelines, increasing biopharmaceutical manufacturing capacity, and rising adoption of single-use technologies. Market demand is anticipated to be supported by ongoing investments in onshoring, CDMO growth, and cell and gene therapy production. While high capital expenditures, supply-chain limitations, and a lack of specialized labor continue to be major obstacles, developments in continuous processing, process automation, and viral vector production present additional growth potential.
Sources and References
- "Thermo Fisher opens flagship U.S. Bioprocess Design Center in Massachusetts". May 2026. News. (Source: corporate.thermofisher.com)
- BioSpectrum Asia. "Cytiva completes projects in Asia, U.S. & Europe with $1.6 B strategic investment". 2025. News. (Source: biospectrumasia.com)
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions





Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample



 sales@precedenceresearch.com
 Schedule a Meeting
